All posts by Financial Independence Hub

ETF investors sitting comfortably in the Balanced Growth sweet spot

By Dale Roberts
Special to the Financial Independence Hub

In October I penned this blog post, The Balanced Growth Portfolio. The Investor’s Sweet Spot. A Balanced Growth model with typically be in the area of 70-80% in stocks and the remainder in bonds. It’s a growth portfolio, but with a modest allocation to bonds to reduce the price risks. As I often write, those bonds work like shock absorbers through market volatility or market corrections. They help smooth out the ride.

I’d call this model the sweet spot as it might offer the best balance of very good total return potential with less risk compared to an all-stock portfolio. It many periods it will deliver the best risk-adjusted returns.

In fact, in many periods the Balanced Growth portfolio model can deliver the same returns as an all-stock model, while taking on less risk. Stock market corrections become the great equalizer. The pure equity model will certainly outperform in a long bull market run, but then the stock market corrections come along and bring the stocks down to earth while the Balanced Growth model then moves into the lead. They might play a game of tortoise and the hare for many years or decades.

See my above post link for charts on that comparison.

Let’s look at the ETF holdings of Canadians

Industry statistics are published by the Canadian ETF Association. You can access the December 2018 report and commentary here.

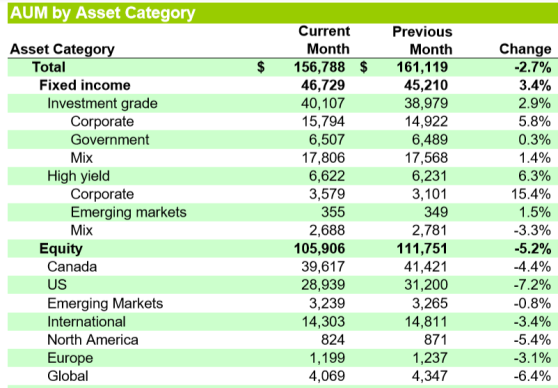
The chart at the top of this blog shows the monthly breakdown of assets held in ETFs. Current Month is month’s end December 2018, Previous Month is November, of course. Keep in mind that the assets will be affected by the total inflows and outflows (purchases and sells) and also the market variance. The stock markets fell in December and that will bring down the total stock assets number.


We see that Canadian ETF investors are in that sweet spot of near 70% equities and 30% bonds. And the good news is that while the stock markets were pulling their little December hissy fit, investors were adding new monies to their ETFs: both Fixed Income and Equities. And you’ll see that Canadian ETF investors are acquiring within the Balanced Growth band.
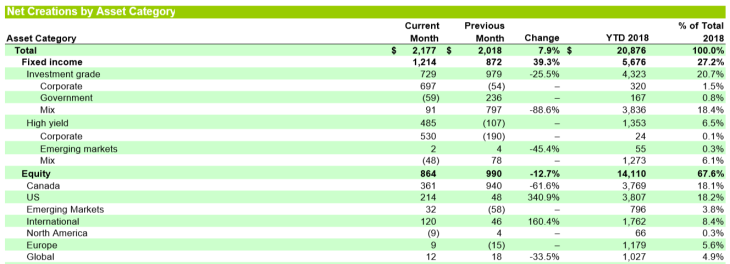
We see that investors did respond to the stock market price risks and moved more monies into the fixed income side of the ledger in December. No problem there. Sometimes Mr. Market gives us a little love tap and reminds us that markets can go down in a hurry. We get a very considerate warning shot across the bow. On that here’s my Seeking Alpha article from one year ago Mr. Volatility is Asking You, Taunting You – So You Wanna Go?

Many of us might be getting a little flabby with respect to our risk taking ability. We have not been tested much in the last decade coming out of the Great Recession. We should always remember that markets can be volatile and they can fall by some 30%, 40% or 50% or more in a major market correction. I reminded readers of those risks in my first post to the Tangerine Forward Thinking blog with Why You Might Still Want Bonds In Your Investment Portfolio.

Ensure that you know your risk tolerance level and that your portfolio is best matched to you risk tolerance level. Have a more than solid investment plan but consider that emotional risk. From that Seeking Alpha article and offered by the most ferocious heavyweight boxer of all time, Mike Tyson …

Everyone has a plan until I punch them in the face.

Yes, Mr. Market may punch you in the face one day. Are you ready? I can take a punch in the market and in the boxing ring. I grew up with a boxing ring in the backyard so that my older brother could practice punching someone in the face as he prepared for and kept in fighting shape for playing Junior ‘hockey’. He only ever lost one hockey fight. Me and my face take full credit. Mr. Market has thrown a few punches too.

All said, be prepared.

How are Robo-Advised Canadians putting monies to work? 

Keep in mind that many investors will create their own ETF Model Portfolios through their discount brokerage. But of course there’s a massive move to the Canadian Robo Advisors, where investors can access digital and human advice that will then lead to the recommendation of risk-appropriate ETF portfolios. That risk assessment is key. Continue Reading…
Pros and Cons of Vacation Timeshares  

By Becky Williams

(Sponsored Content)

If you are like nearly everyone, the time that you spend on vacation represents some of the most pleasant and days of the year. You may spend a good deal of time trying to decide what will be the most amazing type of vacation you can take. One option you may want to focus on is obtaining a vacation timeshare. There are a number of significant benefits associated with a vacation timeshare.

A timeshare may not be for everyone and there are some factors that may make this type of vacation property not the perfect choice for you. However, by weighing and balancing the pros and cons of timeshare ownership, you will be able to make an informed, educated decision as to whether this type of vacation property makes the most sense for you. You will be able to find a vacation timeshare that is perfect for you today and into the future as well.

Guaranteed, reliable vacation

A primary benefit associated with a timeshare is that you have a guaranteed, reliable location to spend your precious vacation days. You do not have to spend an inordinate amount of time trying to find an ideal place to spend a vacation. You need only undertake that task one time when you select a vacation timeshare property the first time.

With a vacation timeshare, you know precisely what to expect. You will never again face a situation in which you are uncertain about what your vacation destination and lodgings really will be like. The reality is that this type of uncertainty, which is completely eliminated with a timeshare, has been a major reason why so many people have experienced vacation disasters.

An ideal location for you

Another key benefit of going the timeshare route when it comes to a vacation property is that you will have a destination and location that is ideally suited to you. There is a significant array of different vacation timeshare options in many, many locations across the United States and around the world.

On a related note, you can enjoy another benefit of getting a vacation timeshare. Many timeshare companies offer you the ability to swap your timeshare location for a particular year. In other words, you can trade your timeshare location with someone else at a different location. This provides you with both reliability and consistency as well as a degree of flexibility should you elect to try something different one year.

Entertaining family, friends, and colleagues

Although your main purpose in purchasing a timeshare is to be able to have a set vacation location for yourself and your immediate family, other people in your life can benefit from the timeshare experience as well.

For example, you may not have the need to use your timeshare for a particular period of time set aside to you. As a result, you can offer your timeshare to extended family members, to friends, and to work or other types of colleagues. Often, the owner of a timeshare will donate a stay to a charitable organization. The stay is auctioned off to raise money for the organization. In short, there really is a tremendous amount you can do with a timeshare, not only for yourself and your immediate family but for a broad spectrum of other people who may be important in your life as well. Continue Reading…

The touchpoint: on being “Packaged” out from the Corporation

By Kevin Press

Special to the Financial Independence Hub

Since being restructured out of my 14-plus-year, rather comfortable position with a global insurance company, I’ve been asked one question more than any other.

Did you see it coming? The answer in my case is yes. I suspect that’s true for most 50- or 60-somethings who’ve found themselves accepting an invitation to “the touchpoint” from their boss, only to find that it’s been moved from their office to HR at the last moment.

Of course, if you’re anything like me (which is to say that you go to work every day like a Jimmy Stewart character in a Hitchcock movie) then nothing comes as a surprise.

I had two thoughts in quick succession when I received my summons. First, what day is it? Tuesday. Dreaded dead-man-walking Tuesday.

Second, how many documents can I email home between now and zero hour? (Nothing sensitive of course, for the record.)

It’s at this point that things began to turn a bit darkly comic. On my walk to HR, I’m stopped to commiserate with a colleague about the dumb email she just got from her boss. Smile and nod.

Young HR person hands me “The Package”

Turn the corner and my fears are realized. The boss is sitting with a too-young member of the HR team, both sporting the kind of sympathetic look that makes you wish you’d forgotten your glasses. I’m told I’ve “had a good run,” which makes me feel a good deal older than my 52 years. Continue Reading…

Why customizing a personal investment portfolio matters

By David Miller, CFP, RFP

Special to the Financial Independence Hub

As we say goodbye to a tumultuous 2018 and hello to 2019, it is time for you to review your investment portfolio strategy to ensure it is set up for success in the New Year and for the long-term.

Below are some questions you should ask yourself as you review your investment portfolio:

  • Is your portfolio suitable for your personal situation?
  • What is your overall investment strategy and has it changed given the level of volatility you likely have experienced?
  • Did you receive individualized investment advice from a qualified professional?
    • Is that qualified professional a portfolio manager or a salesperson?
  • Do you or your advisor look at the whole picture when it comes to managing your money?
  • Are your investments held in a ‘cookie cutter’ investment portfolio?

To ensure your portfolio is suitable, reliable, and catered to your situation, a customized investment portfolio, built by a portfolio manager, may be what you need.

The trend towards a ‘Model Portfolio’

Computers and the use of algorithms have made it easier for banks, institutions and, more recently, Robo-advisors to automate the investment process for the masses. Model portfolios are now common place because of the economies of scale; it’s just cheaper and easier to do. For some people this approach might help save on fees, but for someone with more unique financial planning and investment needs, a cookie-cutter portfolio just doesn’t cut it. You need a portfolio that is customized to your situation.

Why Custom Portfolio Management?

Let’s look at high-income earner John. John has saved faithfully through his big bank over the years, and along with his defined contribution pension/stock plan through his work, he has maximized his RRSP and TFSA. He has no debt and there are very few places he can now allocate his savings without having to worry about the tax implications. He’s in the prime of his earning years and has 10+ years until he’d like to retire.

John is increasingly aware of the high fees his bank is having him pay. He’s seen the advertising on the importance of keeping his fees low *there seems to be a race to the bottom for investment fees1*. He’s looked at the Robo-options and even at managing his own investments, but he’s not sure and a little stuck. It’s not his expertise.

Here are five big reasons why John may want a tailor-made portfolio: Continue Reading…

How does Real Estate ROI compare to other investments?

By Penelope Graham, Zoocasa

Special to the Financial Independence Hub

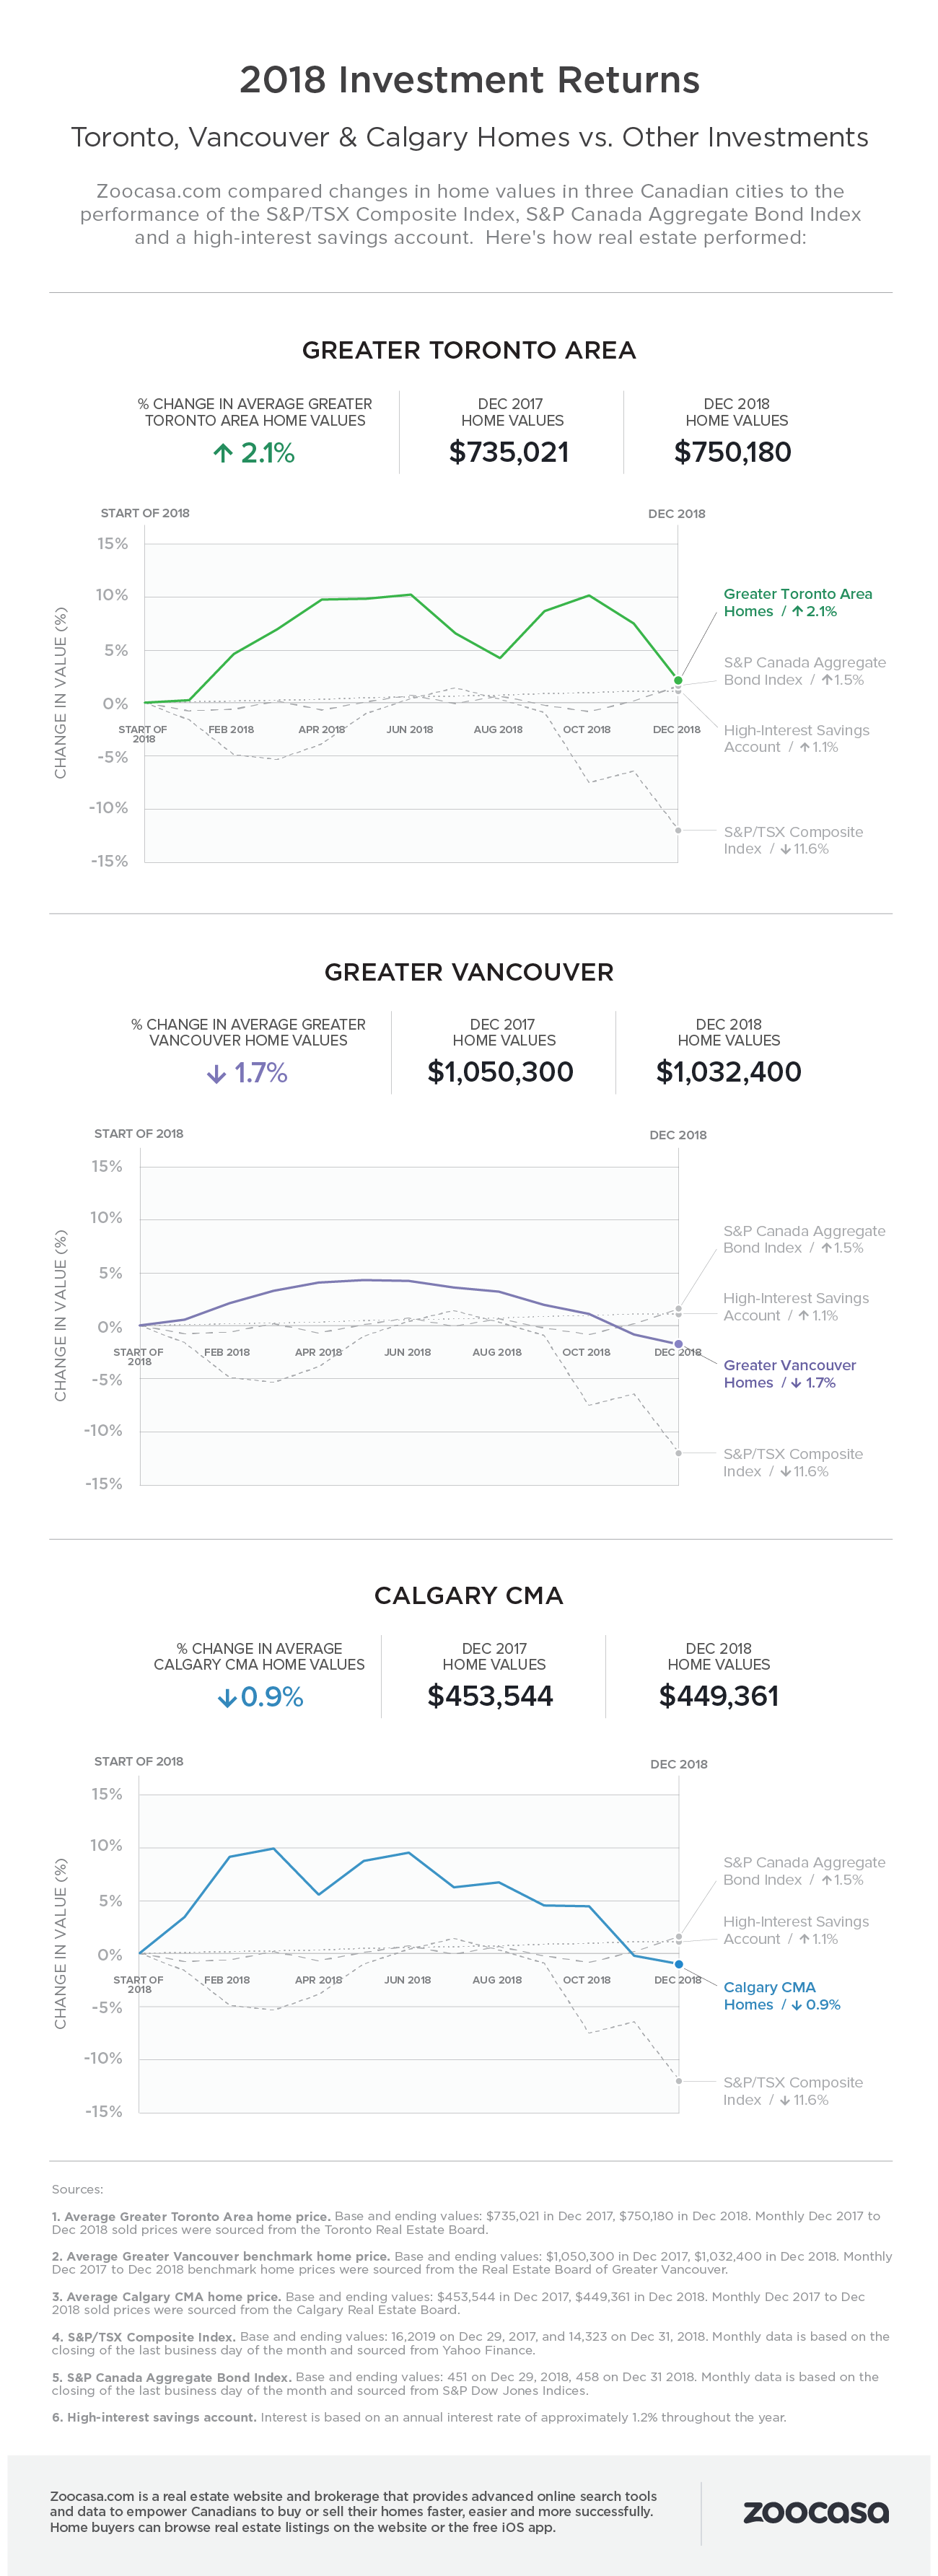
If you ask a long-term homeowner whether they feel their home purchase has turned out to be a worthy investment, chances are they’ll say it was; real estate continues to be considered a safe and effective way to grow your money, according to 68% of homeowners who’ve owned a home for 10 years or longer, according to data collected by Zoocasa.

However, the Canadian housing market is coming off of an admittedly quieter year, with steep declines in sales activity recorded in some of the nation’s largest markets: The Greater Toronto Area, Greater Vancouver, and Calgary have all seen the number of homes changing hands plunge by double digit percentages, mainly due to the impact of tougher federal mortgage rules.

That has subsequently trickled down into home values, with the west coast markets posting year-over-year price declines, while the GTA experienced only moderate, single-digit growth.

So, does the old adage of real estate being among the wisest of investments still hold true? To find out, Zoocasa.com compared average year-over-year price performance to that of three popular investments:

  • The S&P / TSX Composite Index (-11.6%)
  • The S&P Canada Aggregate Bond Index (+1.5% y-o-y)
  • And a high-interest savings account (+1.1%)

Let’s take a look at how real estate price gains (or lack thereof) compared to the returns on these investments in the adjacent infographic.

GTA only market to outpace investment comparison

The GTA (Toronto) housing market ended the year on a positive note, posting an increase of 2.1% for the average home price of $750,180, and the only market to outpace all three investment types.

However, the market lost a considerable bit of steam over the course of the year, unable to hold onto the 9.9% gains achieved at the market peak in June, when prices hit an average of $807,871. Year-over-year December sales clocked in 16% lower than in 2017, which the Toronto Real Estate Board attributes to the federal mortgage stress test. This hurdle, introduced last January, requires borrowers to qualify at a higher rate than their actual contract rate, resulting in a smaller mortgage amount and squeezing affordability in an already expensive market.

“Higher borrowing costs coupled with the new mortgage stress test certainly prompted some households to temporarily move to the sidelines to reassess their housing options,” said TREB President Garry Bhaura, in the board’s December report.

Vancouver values fall from last year

It has been an especially painful year for the Greater Vancouver MLS, as sales have dipped a whopping 31.6% from December 2017: the lowest level of activity since the year 2000. That’s translated into an average price decline of 1.7% to $1,032,400. Continue Reading…