No doubt about it: at some point we’re neither semi-retired, findependent or fully retired. We’re out there in a retirement community or retirement home, and maybe for a few years near the end of this incarnation, some time to reflect on it all in a nursing home. Our Longevity & Aging category features our own unique blog posts, as well as blog feeds from Mark Venning’s ChangeRangers.com and other experts.
The 4% rule was built on the luckiest jar on the shelf.
Image AI-generated by author with ChatGPT
By Hootan Nakhost
Special to Financial Independence Hub
The 4% rule is an American rule
The 4% rule is one of the best-known rules in personal finance. It originates from a 1994 study by financial planner William Bengen. He calculated the maximum safe withdrawal rate for every retirement start year since 1926. He found that withdrawing 4% or less of the starting portfolio in the first year, then raising that amount with inflation each year, lasted 30 years in every case he tested.
The 4% rule is useful because it is simple: you just need to remember one number. Take how much you spend each year, divide by 0.04 (or multiply by 25), and that is the money you need to retire.
One country is a small sample
The 4% number is based on a single country’s history that happens to be one of the best-performing markets in the world. Since 1926, the U.S. hasn’t had a war fought on its own soil, and since 1945 it has been the world’s major power. Retirees in other rich countries were not so lucky. Japan’s Nikkei index took 34 years to get back to its 1989 peak. In the UK, stocks fell about 73% in 1973–74, and inflation reached about 24% in 1975. German savers were wiped out twice: by the 1923 hyperinflation and again by the 1948 currency reform. None of this shows up in U.S. history.
What I tested, and what I found
My simulator uses the Dimson-Marsh-Staunton dataset, which covers stocks, bonds and inflation back to 1900 for most countries; I used the 25 of its countries that count as developed markets, each only from the year it became one (Japan from 1930, Spain from 1959), following Anarkulova et al. (2023) where the data allow.
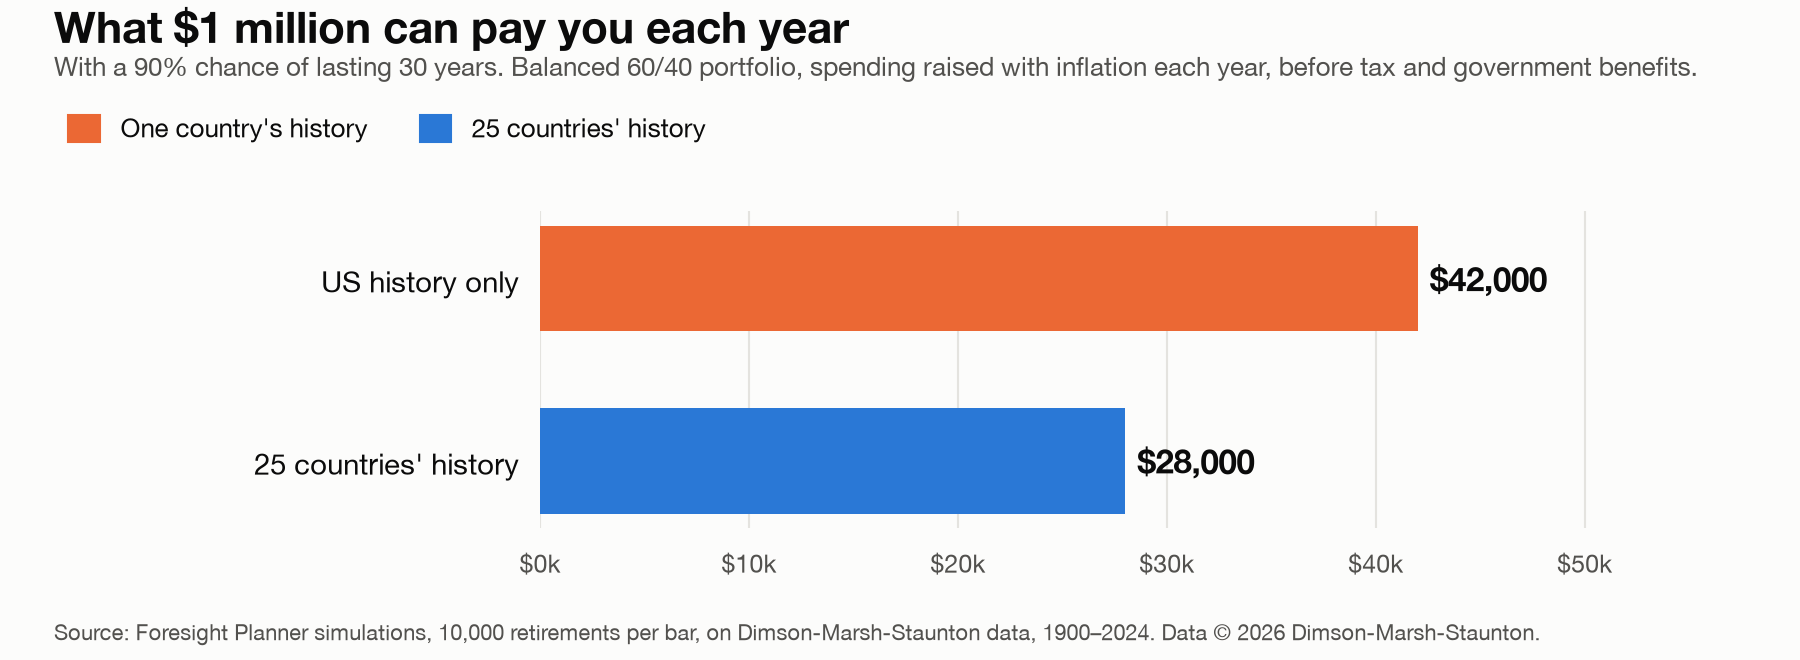
For this post I replayed the same 30-year retirement 10,000 times, stitched together from blocks of real history from 1900 to 2024: once with U.S. history only, and once with all 25. In the 25-country case, each block of history comes from a country drawn at random. This setup avoids the survivorship bias you get when you always pick the U.S. as the home country. The retiree holds either 100% stocks or a balanced 60/40 portfolio, and spends a fixed, inflation-adjusted amount. To keep it simple, there are no taxes, fees or government benefits.
Bengen asked for a rate that never failed in U.S. history. With thousands of simulated retirements, some will always fail, so I report the rate that lasted 30 years in 9 out of 10 of them.
Once each retiree’s home market can be any of the 25 countries, the rate that lasts 30 years 90% of the time falls by about a third.
What gets you back to 4%
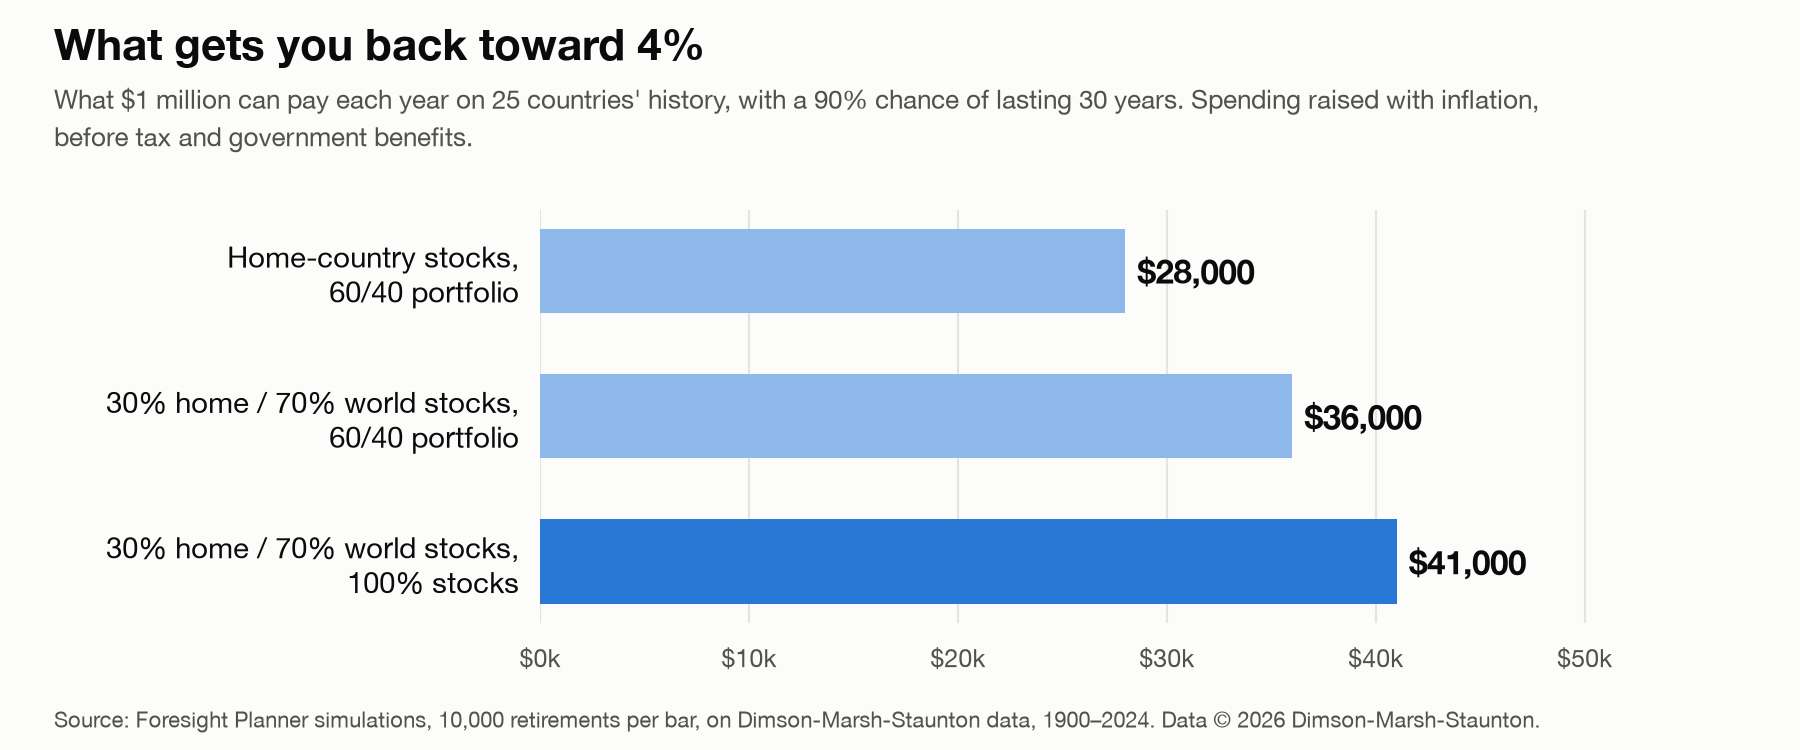
The weak 25-country result assumed each retiree held only their home market. With 30% of the stocks at home and 70% in the rest of the world, the same 60/40 portfolio’s rate rises from 2.8% to 3.6%. With 100% stocks, it reaches about 4.1%.
In this test, bonds lowered the rate. The simulation always uses the retiree’s own country’s bonds, the kind that inflation and war destroyed, so the finding is narrow: home-country bonds didn’t add safety. Global and real-return bonds weren’t tested.
One caveat: an all-stock portfolio can lose half its value in a crash, and the simulation assumes you never sell.
Do you even need 4%?
Benefits in Canada like CPP and OAS change the question. They’re indexed to inflation and paid for life, so your savings only have to cover the gap. Consider a 65-year-old couple with C$1 million in home-country stocks and maximum CPP and full OAS, about $54,500 a year at 2026 rates. Under the 25 countries’ history, their savings can add about $27,500 a year, 2.75% of the $1 million. Together that’s about $82,000 a year of spending, two-thirds of it from benefits. Maximum CPP is uncommon, and these figures are before tax and any OAS clawback. The number that matters is how much of the spending the portfolio has to cover.
What I take from this
On U.S. history alone, about 4.2% held up. Across 25 countries, a home-only 60/40 portfolio held up at about 2.8% and a balanced global one at about 3.6%. Only an all-stock portfolio spread around the world held up at 4%, and only for a retiree who could sit through a 50% drop without selling. Continue Reading…
Earlier this year, I wrote about our early retirement healthcare options in Canada, specifically options for extended health care in early retirement. The research behind that article took a while and I thought the data was quite interesting.
If you’re like me, you probably haven’t really thought about healthcare in early retirement until you get closer to this major milestone, because you just assume that, as a Canadian, universal healthcare is there to cover everything.
But that’s not the reality. Although our universal healthcare covers big expenses like doctor visits, surgery, hospital stays, specialized treatments, it doesn’t cover things like dental, prescription, physio, and vision. These “extra” treatments are usually covered by extended healthcare, which I discussed in my previous article on early retirement options.
Despite having universal healthcare, I believe it’s still important to keep in mind all the different provincial rules and benefits. My previous article primarily focused on BC, so I want to compare early retirement healthcare options in each province. Furthermore, I want to explore options like moving provinces to lower your cost of living, and what if you decided to live abroad most of the year… What happens to your healthcare coverage?
Let’s find out.
Health premium: most provinces phased it out
Many years ago, it was true that you paid for provincial health coverage. But fast-forward to today, that’s no longer true in most provinces.
Here in B.C., the government eliminated the MSP (medical service plan) premium back on January 1, 2020. The BC provincial healthcare is now funded through tax revenues. Similarly, Alberta got rid of the health premium in 2009. If you look across Canada, most provinces have removed the provincial healthcare premiums and provincial healthcare is now funded through general tax revenues.
But the two big Canadian provinces still charge premiums.
Ontario charges an Ontario Health Premium, collected through your income tax return and it is based on your income. If your taxable income is under $20,000, you do not have to pay anything. The premium scales up $0 to a maximum of $900 per year for high-income earners.
Quebec doesn’t charge a health premium, but it does have a mandatory prescription drug arrangement. The fee is collected at tax time if you don’t have private drug coverage.
So yes, for the most part, you don’t have to pay the monthly provincial health premiums anymore. Instead, you are paying via provincial income tax or other provincial taxes.
The gaps that universal healthcare doesn’t cover
The universal healthcare we have in Canada covers many things, especially the big expenses, but it doesn’t cover everything. Our universal healthcare falls short on the following:
Prescription drugs
Dental care
Vison
Paramedical services like physio, massage, chiropractor, counselling, etc
Out-of-country medical care
For these expenses, early retirees typically rely on either private extended healthcare plans, self-insurance for these expenses, or some level of government assistance.
Government-assisted plans for dental & prescription
Prescription drugs can be quite costly, but two provinces have programs to help with that.
Here in B.C., the Fair PharmaCare program covers prescription drugs with a deductible based on your family’s net income from two years ago. You have to pay a deductible first, then Fair PharmaCare covers 70% (or 75% if someone in your family was born before 1940). Once you hit the family maximum, Fair PharmaCare pays 100% of the eligible costs for the rest of the year. You can find the family deductible amount here. For early retirees in BC who need prescription drugs, the Fair PharmaCare program can be a good option.
In Quebec, prescription drug insurance is mandatory. So if you have access to a private plan, you must take it. If you don’t have a private plan, you are automatically enrolled and covered by the public plan. This public plan has a premium that’s income-based via your tax return. Interestingly, Quebec is the only Canadian province that legally requires you to have prescription drug insurance.
Outside of B.C. and Quebec, prescription drug coverage for early retirees is limited. The provincial prescription drug coverage is typically aimed at seniors and people with specific conditions. Below is the summary for the different provinces:
B.C.: Fair PharmaCare. Your deductible and family maximum are calculated from your net income. Lower-income households (including many seniors) have low or zero deductibles.
Alberta: Albertans 65+ have premium-free coverage for prescription drugs on the Alberta Drug Benefit list, administered by Alberta Blue Cross. The copayment is 30% to a maximum of $35. Outpatient cancer therapy and palliative-care patients have separate, copay-free or specialized coverage.
Saskatchewan: eligible seniors 65 and older pay $25 per prescription under the Seniors’ Drug Plan. To qualify, your net income must be $79,487 or less on your 2024 income tax return to be eligible for 2026. There is also coverage for palliative-care drugs and long term disability and illnesses.
Manitoba: Manitoba Pharmacare provides drug assistance to eligible Manitobans via an income-based deductible. Once your spending hits the deductible, the program covers eligible drugs. The Manitoba Enhanced Pharmacare Program covers most medications for residents with certain conditions who aren’t covered through other public programs.
Ontario: 65+ Ontario residents automatically qualify for the Ontario Drug Benefit program. Lower-income seniors can apply for the Seniors Co-Payment program, under which recipients pay no annual deductible and co-payment of $2 or less. The Trillium Drug Program supports lower and modest-income people by covering about 5,000 drugs plus about 1,000 more drugs through the Exceptional Access Program. You pay up to $2 per prescription. The deductible is capped at roughly 4% of household income. (Note, my additional research showed it may actually be more complicated. There’s a $100 annual deductible (Aug-Aug) after which most drugs on Trillium are covered fully, except for the $4.11 dispensing fee).
Quebec: universal/mandatory. Seniors automatically register for the public plan at 65, and many low-income seniors pay a reduced or zero premium.
Nova Scotia: the seniors’ Pharmacare program is open to residents 65+ with a valid health card who don’t have other drug coverage. Members pay an income-based annual premium plus an annual copayment, both with maximums, with the province covering the rest. Separate coverage exists for cancer patients and palliative care.
New Brunswick: The Prescription Drug Program covers low-income families and seniors.
Prince Edward Island: all eligible residents are automatically enrolled in the seniors’ drug plan the month they turn 65. The Family Health Benefit Drug Program and Financial Assistance Drug Program are available for low-income residents and families.
Newfoundland & Labrador: the 65Plus Plan covers residents 65 and older who receive Old Age Security and the Guaranteed Income Supplement. The Foundation Plan and the Access Plan cover low-income individuals and families.
So if you’re an early retiree and not yet 65 or older, you probably need to self-cover prescription drugs.
Dental care can be another big expense for families. Fortunately, as of 2026, the Canadian Dental Care Plan (CDCP) is available to eligible Canadian residents regardless of age, as long as your adjusted family net income is under $90,000 and you don’t have access to private dental insurance. For households under $70,000 net income, you will get full coverage with no co-pay. Between $70k and $90k, you get partial coverage. Therefore, for an early retiree without a group plan and a modest reported income, the CDCP may be able to cover dental care.
Out-of-country coverage: very important to consider
Many retirees will want to travel for an extended period, sometimes outside Canada. This begs the question: What should you do for out-of-country health coverage?
The provincial plan does cover emergency medical care outside Canada, but only at the rates it would pay in your home province. This may sound reasonable, but the reality is that many healthcare costs are way more expensive than in Canada (i.e. the U.S.) I have heard someone not wanting to go to the emergency room in the U.S. and driving back to Canada to get treatment, because of the outrageous US cost (and they didn’t have travel health insurance).
This is why, if you are travelling outside of Canada, it is critical to get travel insurance, regardless of your health conditions. It’s better to be safe than sorry.
Fortunately, many premium credit cards have travel insurance benefits. For example, TD Infinite Visa has a $2 million travel medical insurance for the first 21 days for holders 65 and under. Unfortunately, if you’re 65 or older, these credit-card travel insurance benefits drop significantly. In TD Infinite Visa’s case, the coverage drops to four days. Based on my research, if you are 65+, the best credit cards for travel insurance are the National Bank World Elite Mastercard and Desjardin Odyssey Visa Infinite Privilege (15 days up for seniors aged 65-75). The Scotiabank Platinum American Express and Scotiabank Gold American Express cards also offer 10 days of travel insurance for seniors 65 and older.
Since many early retirees go for extended trips longer than 21 days, it is better not to completely rely on credit-card coverage and get travel insurance. The cost of the travel medical insurance will depend on your age, duration, coverage tier, pre-existing conditions and deductible. For the most part, these travel insurances are quite cost-effective (anywhere from $70 to $500 based on my research).
Keep in mind the three-month gap
If you decide to move to another province to reduce your cost of living, you need to keep in mind the three-month requirement.
Provinces typically have a waiting period of up to three months before the “new” provincial health coverage kicks in. During that window, you will need to rely on your “old” province to continue to cover you. Basically, you need to make sure you register promptly once you settle in the new province so you don’t end up with no health coverage for a brief period.
Similarly, if you go out of the country for an extended time (i.e. more than six months), you are no longer eligible for provincial health coverage, so you will need to cover yourself via health insurance.
A province-by-province health coverage snapshot for early retirees
Here’s a simplified comparison of health coverage for the different provinces. Continue Reading…
Evidence over emotion. Process over prediction. Better decisions over better guesses.
Most financial decisions eventually tell you how they turned out. Choosing your executor never will.
You will not be there to see whether the person you named handled it competently, whether your children are still speaking to one another afterward, or whether the estate settled in eight months, three years or longer.
As I wrote in the first article in this series we judge decisions by their results almost automatically. Here no result is available to judge. The reasoning is the only thing you will ever have, which is a good argument for doing it properly.
What would have to be true for your choice to work?
Most people name an executor the way they would hand out an honour. The oldest child. The sibling who is good with money. The person who would be hurt to be passed over.
A better test is the one this series keeps returning to. What would have to be true for this person to be the right choice?
Three things. They need the time. They need the temperament to hold a position under pressure from people they love. And they need the willingness to pay for professional help rather than guess. Most executors are appointed without anyone testing a single one of those conditions.
How much time does being an executor take?
Estate practitioners commonly estimate 100 to more than 400 hours, spread over twelve to thirty-six months or sometimes longer. Treat that as practitioner judgment rather than a measured Canadian average, because no reliable average exists. At the upper end, 400 hours is ten full working weeks to fit around a job and a family, often while grieving.
The value of the estate tells you less than you would expect. An organised portfolio can be easier to administer than a modest estate with awkward complications. A family member or other beneficiary may need to be located if you have lost contact with them. One living outside Canada brings legal, tax, currency, and cross-border considerations. Property abroad may require local legal and real estate expertise. Complexity comes from family circumstances and where assets sit, not from the size of the balance.
The unpredictable demands are harder still. One beneficiary wants the cottage sold, another wants to keep it, and your executor referees while explaining why nobody is being paid as quickly as they expected.
Can an executor be personally liable?
Yes, and this is the part most people never hear before they agree.
If an executor distributes estate assets without obtaining a clearance certificate from the Canada Revenue Agency, and tax remains owing, the executor can be personally liable up to the value of what was distributed. That includes amounts assessed after the money is gone. CRA does permit distributions before a certificate is issued if enough property is held back to cover the liability, so an executor needs advice on how much to retain.
Picture explaining to your siblings that part of their inheritance has to wait, even though the investments are sold and the cash is sitting in the account. From where they stand there is no visible reason for the delay. Your executor confirms the estate’s tax position anyway, and absorbs the resentment while doing it.
This is why temperament matters as much as financial knowledge. The person needs to be comfortable keeping records, explaining decisions, and saying no to people who will not enjoy hearing it.
Is your executor paid for this work?
They are entitled to be, and that is worth knowing before you compare options.
Ontario uses a long-standing guideline of 2.5 per cent of capital receipts and 2.5 per cent of capital disbursements, with the same rates on revenue in and out, plus a care and management fee of up to 0.4 per cent per year on the average value of the estate. Add those together and you arrive at the rough five per cent of estate value that people usually quote.
It is a guideline, not an entitlement. Courts assess what is reasonable against the size of the estate, its complexity, the time and skill required, the results achieved, and the responsibility assumed, and they can award less. A family member may waive compensation. Many do not, and they are not wrong to claim it, because the work is real.
Estate administration tax, still widely called probate fees, belongs in the same conversation. In Ontario there is nothing payable on the first fifty thousand dollars, and roughly 1.5 per cent on the value above that. It drives both the cost of settling your estate and the timeline your executor will be defending to impatient beneficiaries.
Should you appoint a professional?
It is a reasonable option, particularly where wealth is passing to the next generation, and interest in it has been growing.
There is more than one way to do it. A trust company can be appointed executor outright. Firms also act as agents, handling the administrative work while a family member stays the named executor, which keeps your family in control of decisions while removing most of the paperwork.
Be clear eyed about cost. Fees are generally a percentage of the estate and can look startling next to a family member doing it for nothing. The honest comparison is fee against fee rather than fee against free, since a family executor is entitled to compensation too. What you are buying is experience, fewer expensive mistakes, and someone absorbing conflict that would otherwise land on your children. Pricing and scope differ meaningfully, so compare before committing.
What about your power of attorney for property?
The person you appoint under a power of attorney for property manages your financial affairs during your lifetime, and that authority ends when you die. An executor deals with your estate afterward.
The same person may suit both roles, but assess them separately. Managing bills, investments, and care costs can mean years of continuous decisions. Someone willing to settle your estate may not have capacity for that.
Is there an estate decision where you do see the result?
One, and it deserves more attention than it gets.
If you have wealth beyond your own lifetime needs, giving during your lifetime is a real alternative to leaving a larger estate. Once affordability and the tax position are worked through, money given while you are alive arrives when the people receiving it can actually use it, rather than decades later when they may not need it at all. Continue Reading…
Claiming Social Security early can provide immediate income, but it may reduce future benefits and limit financial flexibility. This article examines key factors such as debt, longevity, cash reserves, survivor protection, and income planning.
Insights from financial experts help readers compare options and make more informed timing decisions.
Preserve Flexibility amid Program Uncertainty
It depends on life stage. Younger clients may want to plan for 75% of benefits on the dollar. While scenarios for pre-retirees can range from reduced benefits to a flat non-inflation-adjusted benefit.
The decision making math remains the same. It’s still too early to tell exactly what will happen with Social Security. Pre-retirees should still consider income needs and longevity over how benefits might change.
To hedge this risk pre-retirees should build flexibility within their retirement plan. Locking income into guaranteed lifetime payments makes it harder to pivot if benefits change. — Samuel Resultan, Financial Consultant, Voyage Wealth Management
Postpone CPP and OAS for Raises
For Canadians who can keep working — or who have other income to bridge the gap — delaying CPP and OAS is one of the few guaranteed raises in retirement. According to Service Canada, CPP grows 0.7% for every month you delay after 65, up to 42% more at 70, and OAS grows 0.6% a month, up to 36% more at 70. Those larger payments are permanent and indexed to inflation, so delaying is really buying longevity insurance: the longer you live, the more it pays. It is not right for everyone. If you need the income now, have health concerns, or qualify for the Guaranteed Income Supplement, starting earlier can make sense. But if you are healthy, still working, and can cover expenses in your late 60s from savings or part-time income, run the numbers on waiting before you default to 65: 65 is just the standard age, not a deadline. — Rohit Dahiya, Founder, LearnLoonie.ca
Keep Cash Reserves for Deferral
The national debt and the Social Security trust fund get lumped together, and they’re separate problems. The trust fund is what matters here. The trustees project it runs short in the early 2030s, and after that incoming payroll taxes still cover roughly 80 per cent of scheduled benefits. That’s a cut. It isn’t zero.
So run the numbers with the cut baked in. If waiting to 70 still wins at 80 cents on the dollar, and for a healthy married person it usually does, the headline doesn’t change the answer. If a cut comes it would most likely be across the board, which means the person who claimed at 62 takes it on a check that was already about 43% smaller than the age-70 amount.
Claiming early does make sense with poor health, or for the lower earner in a couple whose check won’t become the survivor benefit. Taking it early to invest only works if it actually gets invested. In my experience it usually gets spent.
The better hedge is a cash reserve, so you’re never forced to claim early in a bad year. — Hans Goldstein, Founder, Structured Installment Sales & Exit Tax Planning, Hans Goldstein: Tax & Exit Planning
Stress-Test Income and Build Reserves
My numbers don’t change much. The US$40 trillion national debt is a separate problem from the Social Security trust fund shortfall. The biggest risk to me is that the retirement fund will be exhausted by 2033, at which time about 77% to 80% of scheduled benefits will continue to be paid from current payroll taxes. Any cut to benefits will be proportional, so that a reduced cheque at age 70 is still larger than a reduced cheque at age 62. For Canadians, the biggest risk to the plan is zero. But the CPP is a separately funded plan, and the chief actuary reports that it will be “sustainable” for 75 years.
There is some justification to taking your retirement benefits early, but the reward for waiting past full retirement age to take benefits is significant. Generally, one can earn 8% per year more in guaranteed, inflation-adjusted income by delaying retirement benefits past full retirement age. Waiting to take retirement benefits early is therefore justified by poor health, short family longevity, or no spouse to receive survivor benefits.
Calculate how much you need to have to run the plan at 75% of your projected benefit. If the number is still sustainable, then the rest of the news is irrelevant. Use your 401(k) or RRSP to “bridge” to 70. The effect of lowering your required withdrawals and taxes in retirement will be dramatic. Keep 2-3 years of required retirement spending in cash or very short-term bonds. The worst crash ever will not force you into early retirement. Pay off your mortgage before retirement. The worst fixed cost in retirement is yourself. — Ace Zhuo, CEO | Sales and Marketing, Tech & Finance Expert, TradingFXVPS
Let Longevity guide your Timing
Myth: Since the trust fund is running short anyway, I should “take it early and grow it.”
Social Security claiming age has little to do with markets or investment-return guesses, and a lot to do with longevity and breakeven. Will you, or a spouse who may rely on survivor benefits, live long enough for the delayed retirement credits (the increase you earn by waiting past full retirement age, up to 70) to outweigh the permanent reduction for claiming between 62 and full retirement age? That math does not need an investment-return assumption.
Trust fund shortfall talk changes the risk story, not the formula. According to the SSA trustees, if Congress takes no action, scheduled benefits can be paid until the OASI reserve is used up. After that, ongoing payroll tax revenue covers only a portion of scheduled benefits, and that cut applies to everyone, not just those who delay. So claiming earlier does not create a protected pocket outside the same rules.
Instead of “take it early and grow it,” model these:
Your primary insurance amount at full retirement age, then the reduction or delayed-credit bump at your claim age.
Spousal and survivor benefit interactions.
Taxes and Medicare: other income can make benefits taxable and affect IRMAA, and working before full retirement age can trigger the earnings test.
A cash-flow bridge if you delay, with a tax dry-run on withdrawals from other accounts.
Check your Social Security account often to keep your earnings record clean, and revisit your claiming age when health, work plans, or a spouse’s age changes. — Mehdi Zare CFA, Founder, Bina Capital
Clear Debt before you File
I’m Nick Avila, founder of United Debt Relief. I’ll leave the investment math to planners and add the part most claiming advice skips: your own debt.
First, the cut. The 2026 Social Security Trustees Report projects the combined trust funds will be depleted in 2034, with enough income at that point to pay 83% of scheduled benefits if Congress doesn’t act. That’s a real risk. It’s also a partial cut, not zero, and under current law it would apply to early and late claimers alike. So on its own, I think it’s a weak reason to lock in a permanently smaller check.
And the early-claiming penalty is permanent. For anyone born in 1960 or later, SSA says claiming at 62 pays 70% of your full benefit, and each year you wait past 67 adds 8% until 70.
Where I do see early claiming make sense is Debt. If someone reaches 62 carrying credit card balances, at the 22.15% average rate the Federal Reserve reports for accounts charged interest, and has no other way to pay them down, using early benefits to clear that debt can beat letting it compound for years while they wait. It’s an expensive fix, though. I’d much rather see people clear the cards from earned income in their late 50s and keep the option to delay.
The hedge I wish more people knew about is legal, not financial. The CFPB notes that when benefits arrive by direct deposit and a bank gets a garnishment order, two months of benefits are protected in the account, and Social Security is shielded from most private debt collectors. Government debts are different. Back taxes and defaulted federal student loans can be collected from benefits, and SSA says the IRS can levy up to 15% of payments for overdue federal taxes.
So the best hedge against a smaller cheque is entering retirement without federal tax debt or a defaulted federal student loan, because those can follow you straight into your Social Security payment. Everyone’s situation is different, so run your own numbers with a fee-only planner before you decide when to claim. — Nick Avila, Founder, United Debt Relief
Protect Survivors with Layered Coverage
We need to keep in mind that current warnings refer to reducing the benefits, not their elimination, and waiting to claim typically results in higher payments. Claiming early translates into a permanently lower benefit and introduces market risk, which may not outweigh the guaranteed increase from delaying.
While indeed this approach will work for some individuals, it should be reviewed with a licensed financial advisor case by case rather than applied broadly.
One critical factor families often overlook is the impact on the surviving spouse. After the higher-earning partner passes away, the survivor generally receives the larger Social Security payment. If the higher earner claims early, the surviving spouse may have to rely on a smaller benefit for many years.
Relying on a single income source is not advisable. In my 18 years in the insurance career, I have observed that retirees who feel most secure use multiple layers of protection, such as combining Social Security, savings, and life insurance designed to replace lost spousal income. When one income stream ends due to a spouse’s death, life insurance can help fill that gap, allowing the surviving spouse to remain in the home.
This is not an investment strategy per se, but a way to ensure that benefit reductions, market downturns, or loss of a spouse do not impact the same person all at once. — Jeremy Hewett, President and Chief Executive Officer, AccuQuote
Diversify Globally against Sovereign Risk
With over 20 years advising private equity and multinationals on capital advisory, I evaluate statutory retirement benefits through the lens of sovereign counterparty risk. When a public balance sheet faces severe long-term debt, relying entirely on static future payout models introduces regulatory uncertainty that you cannot control.
There is a sound strategic argument for claiming early if you systematically redirect that cash flow into liquid global equities and high-yield operational investments. Taking the liquidity immediately places capital allocation back under your direct governance rather than leaving it exposed to future legislative restructuring.
A strong hedge against single-country entitlement reform is geographic and jurisdictional diversification. By structuring assets across multiple international corporate entities and foreign-denominated holdings, you insulate your broader wealth plan from the fiscal pressures of any single government. –– Sebastien Gaddini, Principal, Corpiya
Delay Social Security despite Potential Haircuts
The $40 trillion debt headline is genuinely alarming, but let’s separate two distinct issues that often get conflated: the national debt is a real long-term fiscal challenge, while Social Security’s funding shortfall is a separate, more immediate, and more precisely quantifiable problem tied to payroll tax revenue versus benefit obligations, not general federal debt. The Trustees project trust fund depletion around 2033-2034, potentially triggering an automatic 20-25% benefit reduction if Congress takes zero action, which I consider unlikely but not impossible.
Does this change my calculation on delaying to 70? Not dramatically, and here’s the math explaining why. Delaying benefits still guarantees roughly 8% annual increases between full retirement age and 70. Even if benefits get reduced by 20-25% starting in 2034, that reduction would apply proportionally whether you claimed at 62, 67, or 70, since cuts would adjust the overall benefit formula, not penalize delayed claiming specifically. So delaying still produces a larger base benefit before any potential haircut, meaning you’d still come out ahead with delayed claiming even under reduction scenarios, just with a smaller total than originally projected.
The “take it early and invest for growth” argument does have some legitimate mathematical appeal, particularly if you’re disciplined enough to actually invest rather than spend the money, and if market returns cooperate. Historically, an 8-10% average stock market return could theoretically outpace the guaranteed 8% delayed retirement credit.
I recommend three approaches: first, build retirement income diversification beyond Social Security through IRAs, 401(k)s, and if available, guaranteed income products like annuities, reducing total dependence on any single income source. Second, maintain flexibility in your claiming strategy, some financial planners now recommend claiming slightly earlier than 70, perhaps at 67-68, splitting the difference between maximizing benefits and hedging against uncertainty. Third, stay politically engaged and informed, since historically Congress has always intervened before depletion deadlines through payroll tax adjustments or formula changes, meaning the doomsday scenario, while theoretically possible, remains historically improbable given the political consequences of inaction. — Loretta Kilday, DebtCC Spokesperson, Debt Consolidation Care
Model a Reduced Future before Claims
I would not treat the Social Security funding warning as an automatic reason to claim early. I would instead stress-test the retirement plan as though future benefits will be lower, then make the claiming decision based on longevity, cash needs, and risk tolerance. Continue Reading…
As we are getting closer and closer toward our goal of early retirement, we have been doing a lot of projections, calculations, and planning. While it’s somewhat easy to estimate our income and expenses in early retirement, one thing that has been creeping in the background that we may have ignored over the years is health coverage in early retirement.
To be more specific, what do we do with health coverage gaps in early retirement? Health coverage is one of the critical expenses that everyone must factor into his or her retirement budget.
Fortunately, thanks to universal health care in Canada, healthcare expenses aren’t as scary and uncertain compared to those in the U.S. But what happens to health expenses like prescription drugs, dental care, vision care, and paramedical care that aren’t typically covered by the provincial and territorial health care?
I thought it’d be worthwhile to do some research and find out what our options are.
Please note, this post is based purely on my online research and I will focus on coverage for BC specifically. For those readers who are retired or have done more research on healthcare coverage in early retirement in Canada, I would love to hear from you in the comments section below.
Our current situation
Unlike what many Canadians believe, our universal healthcare system doesn’t cover everything.
When you are working, your employer typically offers extended health benefits, which give you access to extended healthcare options.
Take our family, for example. Thanks to my full-time job, my employer offers extended health care insurance via SunLife. We have three different extended health care options to pick from: Your Choice, Traditional, and Enhanced, with each option covering a different amount of extended health care and each option has different premiums..
After some calculation, we picked the Enhanced coverage for our family and with this coverage, we pay $78.83 every two weeks, $170.89 per month, or $2,049.58 per year for extended health and dental benefits.
The Enhanced coverage gives us the following extended health coverages:
100% coverage on generic prescription drugs
Semi-private hospital room type
100% unlimited maximum, 60-day trip duration for out of country emergency coverage
$1,000 per year up to a combined maximum of $1,700 for various paramedical services (i.e. massages, naturopaths, acupuncture, chiropractors, counsellors, etc)
$1,500 per year for physiotherapists
$400 every 24 months for vision care for adults, $400 every 12 months for children
100% coverage for preventative dental care up to $2,000 for the benefit year, 65% coverage for major restorative, and 50% coverage for orthodontics for a $2,500 lifetime maximum
Since we’re paying for the extended healthcare, we try to take full advantage of our paramedical, vision, and dental benefits every year.
For the most part, we haven’t needed to use the prescription drug benefit. We have used the physio benefits here and there (as in a few years ago when my back was bothering me).
The BC Provincial Healthcare
The Medical Service Plan (MSP) is BC’s health insurance program that pays for required medical services. Here in B.C., the MSP covers the following medical benefits:
Doctor visits and hospital stays
Maternity care provided by a physician or a midwife
Medically necessary surgeries and procedures
Diagnostic tests and X-rays
Annual eye examination for children aged 0-18 and seniors aged 65+
I believe other provinces and territories have similar medical plans covering similar benefits as well.
When you live in B.C., you are required to enroll in the MSP. Years ago, you needed to pay MSP premiums based on your income. But the premiums were eliminated on January 1, 2020. In case you’re wondering, the MSP is now funded through general taxation. The fact that BC MSP has no monthly premium means it is one less expense to consider in early retirement.
However, as you can see, the BC MSP does not cover things like prescription drugs, dental care, vision care, paramedical care, and physiotherapy. This is where the extended health coverage may be necessary in early retirement.
When it comes to BC MSP, there’s not much you need to do when you retire. To qualify for the BC MSP, you just need to maintain B.C. as your primary residence and the coverage continues automatically as long as you remain a B.C. resident.
Extended Healthcare in early retirement Option 1: Self funding
The easiest way when it comes to extended healthcare in early retirement is to self fund all the different services. So instead of having extended health insurance covering dental care, vision care, and paramedical services, we would simply pay for these services as needed.
The nice thing with self funding these expenses is that most of these expenses like massages, physiotherapy, dental care, and vision care, are considered as eligible medical expenses so we can claim them on our tax return and potentially reduce the tax that we may have to pay.
Right now, since we’re paying extended health premiums, we are having dental, vision, and paramedical services like massage and acupuncture regularly to max out our eligible benefits. If we go with the self funding route in early retirement, perhaps we would reduce the overall extended healthcare expense amount by only spending on what we deem as essential services. For example, rather than going for a massage every month, perhaps we would go every two or three months instead.
Extended Healthcare in early retirement Option 2: Government & private coverages
Although self funding is an option, it might be better if we can get extended healthcare coverage via a combination of government benefits and private extended health insurance.
BC’s Fair PharmaCare
One thing that’s interesting for early retirees in B.C. is that the province offers an income-based drug coverage program called Fair PharmaCare.
Under Fair PharmaCare, all BC residents are eligible if they have MSP coverage and meet the income level requirements. The program covers some prescription drugs, medical devices, and pharmacy services. You can find more about what BC PharmaCare covers here. Basically, Fair PharmaCare is based on your family’s net income from two years ago. You have to pay a deductible first then Fair PharmaCare covers 70% (or 75% if someone in your family was born before 1940). Once you hit the family maximum, Fair PharmaCare pays 100% of the eligible costs for the rest of the year. You can find the family deductible amount here.
Fair PharmaCare is a good option for early retirees in BC if you need coverage for prescription drugs. In our case, this may not be as important (*knock on wood*).
The Canadian Dental Care Plan
For dental care, early retirees may be eligible for the Canadian Dental Care Plan (CDCP). The CDCP is a Canadian federal government program designed to provide access to affordable dental care for eligible Canadians who do not have access to dental insurance. Early retirees under the age of 65 are eligible if the household income is under $90,000.
The CDCP covers a variety of dental services:
Preventive care like cleanings
Diagnostic services like exams and X-rays
Restorative treatments
Surgical removal of tumours and cysts
Now, the CPCD will only cover over 100% of eligible dental expenses if the adjusted family net income is lower than $70,000. If your family’s net income is between $70,000 and $90,000, you will need to cover the co-payment portion.
Private Health Insurance Options
Another option is to go through private health insurance. This might make sense for our household to cover out-of-pocket costs for dental care, vision care, and paramedical services. If I look at our past extended health expenses over the last few years, I noted that we have spent anywhere between $5,000 and $8,000 (most of these expenses were reimbursed by our extended healthcare plan). Therefore, for our household, it may make sense to utilize the private health insurance option rather than self-fund these expenses.
Based on the market rates I found during my research, the average monthly premium per person is between $60 to $150. This is a wide range because the monthly premiums are based on your age. For someone in their 40s, the premiums are between $60 to $80 per person.
Again, these are the average ballpark figures. The actual cost will depend on age, health, location, and the level of coverage you choose.
For the most part, private health insurance options in Canada are offered by SunLife and Manulife.
SunLife’s private health insurance is called SunLife Health Insurance and there are three coverages – basic, standard, and enhanced. All of them are very similar to what my employer’s extended health offers (not a surprise since my employer uses SunLife). The per month cost, however, seems to be much higher than what we currently pay ($411.27 per month for the enhanced plan or $4,935.24, more than double the amount we’re paying under my employer’s extended health plan).
For both SunLife and Manulife, the cost of the extended health insurance plans varies depending on the coverage. However, from what I can find, the per month cost for our family is much higher than what we are paying right now.
Continue private health insurance via an existing employer plan
Interestingly, both SunLife and Manulife offer options to convert a group employer plan to an individual plan. Basically, if you’re leaving an employer group plan, you can do the conversion within 60-90 days without medical underwriting or testing.
This means we can convert our existing SunLife group extended health plan to an individual plan without answering any medical questions, health exams, and pre-existing conditions are covered.
Now, if you miss this 60-90 day window, you will need to face medical underwriting, higher premiums, or exclusions for pre-existing conditions. Obviously, this is not very desirable.
The group to individual conversion is highly attractive for us once we are in early retirement. I will need to follow up with my company’s HR team to find out more information without raising too many red flags… another option is to contact SunLife to find out more information.
Our current strategy for healthcare in early retirement
Looking at the different options available, here’s our current healthcare strategy when we retire early: Continue Reading…
 Posted By
 In this test, bonds lowered the rate. The simulation always uses the retiree’s own country’s bonds, the kind that inflation and war destroyed, so the finding is narrow: home-country bonds didn’t add safety. Global and real-return bonds weren’t tested.