Building Wealth

For the first 30 or so years of working, saving and investing, you’ll be first in the mode of getting out of the hole (paying down debt), and then building your net worth (that’s wealth accumulation.). But don’t forget, wealth accumulation isn’t the ultimate goal. Decumulation is! (a separate category here at the Hub).

Is the 4% annual Withdrawal Rule still safe? What 125 years of market history from 25 countries say

The 4% rule was built on the luckiest jar on the shelf.

Image AI-generated by author with ChatGPT

By Hootan Nakhost

Special to Financial Independence Hub

The 4% rule is an American rule

The 4% rule is one of the best-known rules in personal finance. It originates from a 1994 study by financial planner William Bengen. He calculated the maximum safe withdrawal rate for every retirement start year since 1926. He found that withdrawing 4% or less of the starting portfolio in the first year, then raising that amount with inflation each year, lasted 30 years in every case he tested.

The 4% rule is useful because it is simple: you just need to remember one number. Take how much you spend each year, divide by 0.04 (or multiply by 25), and that is the money you need to retire.

One country is a small sample

The 4% number is based on a single country’s history that happens to be one of the best-performing markets in the world. Since 1926, the U.S. hasn’t had a war fought on its own soil, and since 1945 it has been the world’s major power. Retirees in other rich countries were not so lucky. Japan’s Nikkei index took 34 years to get back to its 1989 peak. In the UK, stocks fell about 73% in 1973–74, and inflation reached about 24% in 1975. German savers were wiped out twice: by the 1923 hyperinflation and again by the 1948 currency reform. None of this shows up in U.S. history.

What I tested, and what I found

My simulator uses the Dimson-Marsh-Staunton dataset, which covers stocks, bonds and inflation back to 1900 for most countries; I used the 25 of its countries that count as developed markets, each only from the year it became one (Japan from 1930, Spain from 1959), following Anarkulova et al. (2023) where the data allow.

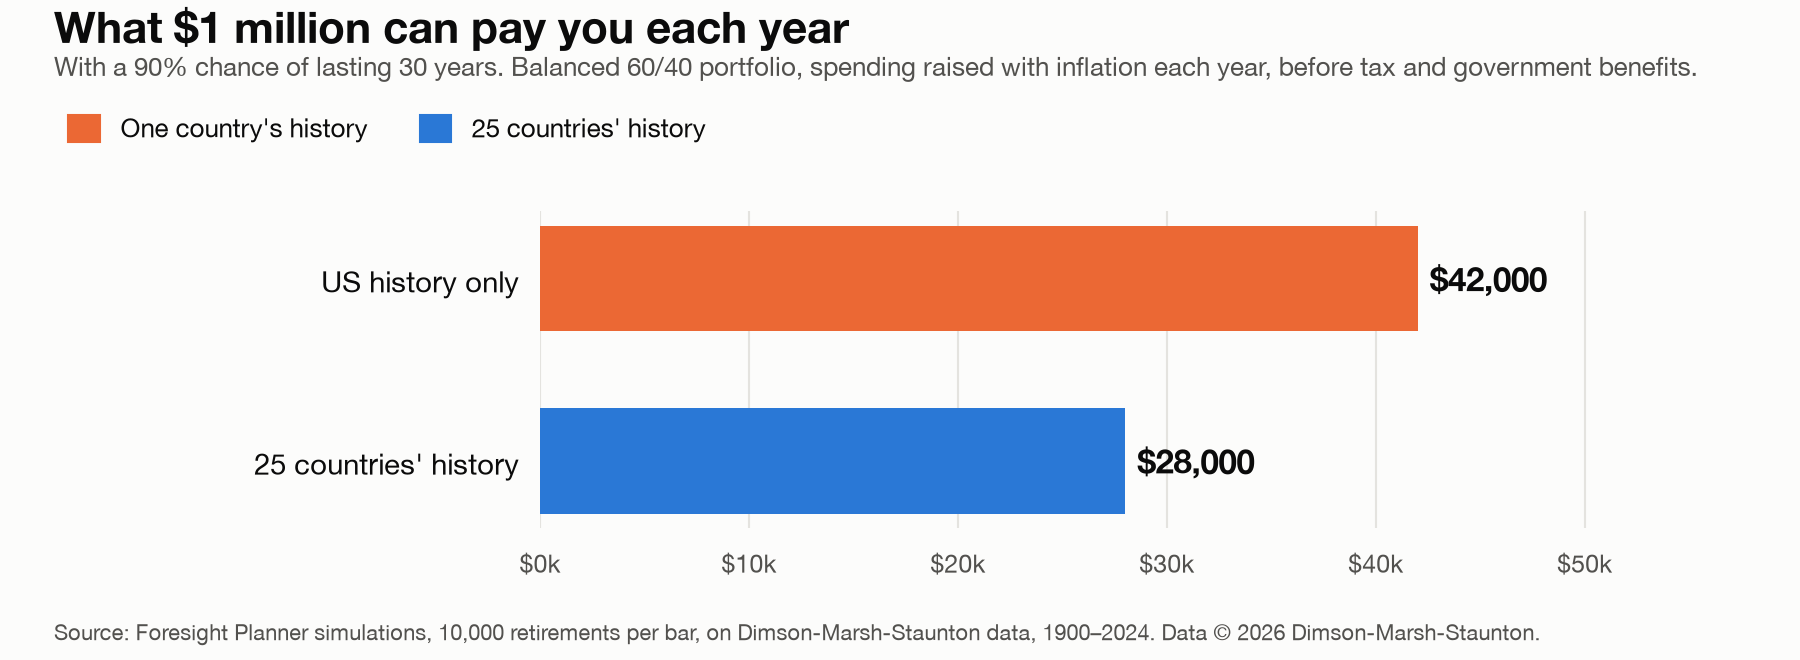
For this post I replayed the same 30-year retirement 10,000 times, stitched together from blocks of real history from 1900 to 2024: once with U.S. history only, and once with all 25. In the 25-country case, each block of history comes from a country drawn at random. This setup avoids the survivorship bias you get when you always pick the U.S. as the home country. The retiree holds either 100% stocks or a balanced 60/40 portfolio, and spends a fixed, inflation-adjusted amount. To keep it simple, there are no taxes, fees or government benefits.

Bengen asked for a rate that never failed in U.S. history. With thousands of simulated retirements, some will always fail, so I report the rate that lasted 30 years in 9 out of 10 of them.

Once each retiree’s home market can be any of the 25 countries, the rate that lasts 30 years 90% of the time falls by about a third.

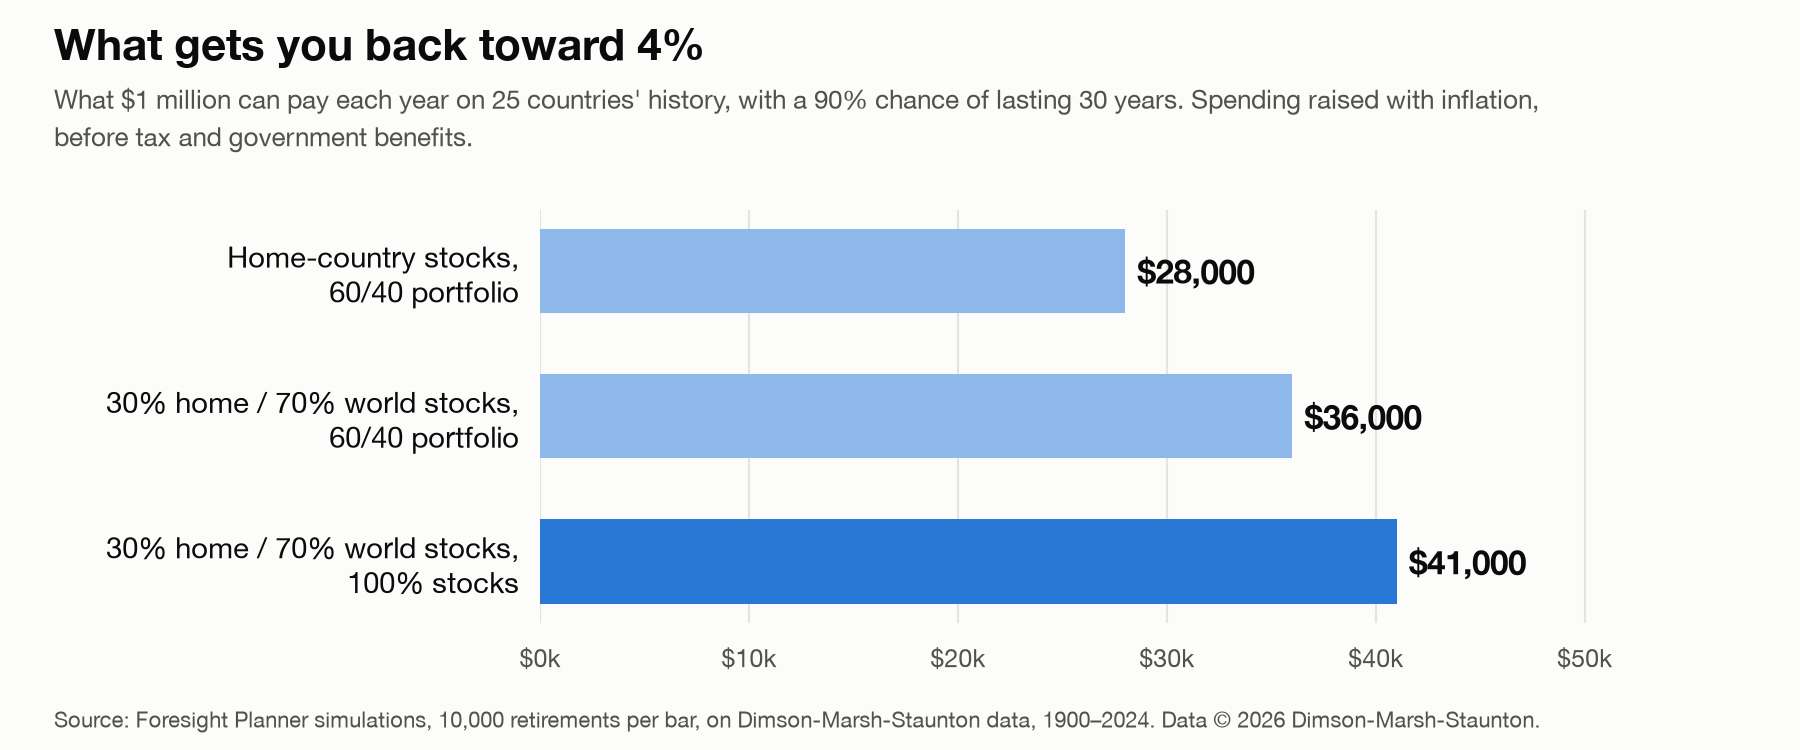
What gets you back to 4%

The weak 25-country result assumed each retiree held only their home market. With 30% of the stocks at home and 70% in the rest of the world, the same 60/40 portfolio’s rate rises from 2.8% to 3.6%. With 100% stocks, it reaches about 4.1%.

In this test, bonds lowered the rate. The simulation always uses the retiree’s own country’s bonds, the kind that inflation and war destroyed, so the finding is narrow: home-country bonds didn’t add safety. Global and real-return bonds weren’t tested.

One caveat: an all-stock portfolio can lose half its value in a crash, and the simulation assumes you never sell.

Do you even need 4%?

Benefits in Canada like CPP and OAS change the question. They’re indexed to inflation and paid for life, so your savings only have to cover the gap. Consider a 65-year-old couple with C$1 million in home-country stocks and maximum CPP and full OAS, about $54,500 a year at 2026 rates. Under the 25 countries’ history, their savings can add about $27,500 a year, 2.75% of the $1 million. Together that’s about $82,000 a year of spending, two-thirds of it from benefits. Maximum CPP is uncommon, and these figures are before tax and any OAS clawback. The number that matters is how much of the spending the portfolio has to cover.

What I take from this

On U.S. history alone, about 4.2% held up. Across 25 countries, a home-only 60/40 portfolio held up at about 2.8% and a balanced global one at about 3.6%. Only an all-stock portfolio spread around the world held up at 4%, and only for a retiree who could sit through a 50% drop without selling. Continue Reading…

Rich by Income or by Wealth? Household rankings by the Prehn Institute

Photo credit: Felix Nikolas Prehn

In 2025, the highest-earning fifth of U.S. households received 52.4 per cent of all household income, and the lowest fifth received 3.0 per cent, the Census Bureau reported 15 September 2026.

That is a ladder ranked by what households take in. A second ladder, ranked by what households own, gives a different picture, and it is the one The Prehn Institute chose for its September 2026 report.

Ranking by income and ranking by wealth

The Census release, “Income in the United States: 2025,” put the top 5 per cent of households at 23.5 per cent of aggregate income. Median household income was $87,460, the highest on record in a series that starts in 1967.

The Gini index, which runs from 0 when every household earns the same to 1 when one household earns everything, was 0.490. The bureau found it not statistically different from 2024. Household income rose 1.7 per cent at the 90th percentile and showed no statistically significant change at the 10th. Income at the 90th percentile, $261,300, was 13.06 times income at the 10th percentile, $20,010, the bureau said.

The institute’s report, “The Hidden Regressive Tax,” by Felix Nikolas Prehn, is posted on Zenodo. It sorts households by wealth, meaning everything a household owns minus everything it owes. Four groups result: the top 1 per cent, then the 90th to 99th percentiles, then the 50th to 90th, then the bottom half.

The report sets out why that ranking became possible. Since 2019, it notes, the Federal Reserve has published the Distributional Financial Accounts, a quarterly reconstruction of the balance sheet of each wealth group from the top 1 per cent to the bottom 50 per cent, going back to 1989. Combined with standard price and money series, the report states, those accounts make it possible to measure who captured the gains rather than assert it.

The Fed’s ranking by income

The Federal Reserve’s Distributional Financial Accounts sort households by wealth, and they also sort the same households by income. The second set is the Fed’s own work, not the report’s. The paper does not use income groups.

In the income-ranked files, the top 1 per cent of households by income held 25.2 per cent of US household wealth in the second quarter of 2026, up from 16.6 per cent in the third quarter of 1989. The bottom 20 per cent by income held 2.8 per cent.

Stocks are more concentrated still. Households in the top 1 per cent by income held 39.6 per cent of corporate stocks and mutual fund shares outside retirement plans, according to the same files.

The same files show the other side of the balance sheet. The bottom 20 per cent by income held 7.1 per cent of consumer credit, the Fed’s data show, a larger slice of the nation’s card and loan balances than of its household wealth.

Even when households are ranked by income, ownership is concentrated at the top. These are income groups, though, a different set of households from the wealth groups.

The report’s ranking

Ranked by wealth, the report places the top 1 per cent at 32.5 per cent of household wealth in the second quarter of 2026, using the Fed’s data, and the bottom half at 2.3 per cent.

Those figures should not be set against the income-group figures as if they measured the same thing. The top 1 per cent by income and the top 1 per cent by wealth are different lists of households, and a bottom fifth is a different slice of the country from a bottom half. Each number belongs to its own ladder.

The report ranks by wealth because of the question it asks. Its subject is the asset-poor, which the paper describes as households whose economic position rests on wages, cash and rented housing. Its argument is that money creation on the scale seen since 2000 transfers real resources from those households to households whose position rests on shares, property and other claims on future income.

The report’s own tally shows the size of the gap on its wealth ladder. Between the first quarter of 2020 and the second quarter of 2026, it states, the top 1 per cent by wealth gained $30.8 trillion and the bottom half $2.3 trillion.

Rising pay, slipping position

The report does not claim that incomes stood still. It notes that real median household income rose 19 per cent between 2000 and 2025, and that the real hourly earnings of production workers rose 20 per cent. It calls both true and important. Continue Reading…

Deja vu all over again: The case for Dividends and Low-Volatility stocks

Shutterstock (Yury Zap)

By Noah Solomon,

Special to Financial Independence Hub

You go back, Jack, do it again, wheel turnin’ ’round and ’round
You go back, Jack, do it again

— Do It Again, by Steely Dan


The Historical Track Record: What has Worked

Eugene Fama, an American economist and Nobel Laureate, is recognized for his work on portfolio theory. Fama is best known for his groundbreaking research on multi-factor models, which incorporate multiple variables to better explain portfolios’ risks and returns.

In collaboration with Kenneth French, Fama challenged the widely held belief that a portfolio’s beta (its sensitivity to overall market movements) is the sole determinant of its average return. Developed in 1992, the original Fama-French Three Factor model demonstrated that smaller companies tend to outperform larger ones, and that stocks with lower valuations tend to outperform those with higher ones.

Since Fama and French’s original findings, academic research has identified additional characteristics that further explain a portfolio’s return, including its dividend yield and volatility. Over the long-term, less volatile stocks have outperformed their more volatile counterparts, and stocks with higher dividend yields have outperformed those with no or lower ones. Moreover, both low-volatility and higher-yield stocks have exhibited considerably less volatility than the overall market.

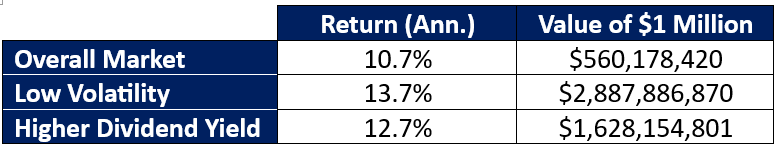
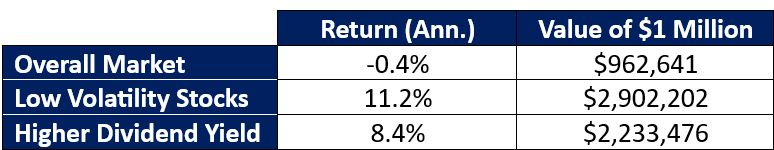
Low Volatility & Higher Dividend Yielding Stocks vs. Overall Market (1964-2025)

If only Life were so Simple

The above table implies that investors should simply hold low-volatility companies that have higher than average dividend yields, sit back, enjoy above-market returns, and accumulate significantly more wealth over the long term.

As is often the case with investing, things are not so simple. Although these characteristics have indeed delivered impressive long-term performance, the proverbial “ride” has entailed some painful bumps in the road.

In times when investors are most optimistic and speculative fervor is widespread, markets tend to underprice risk, which leads to a relative undervaluation of companies with defensive attributes vs. their more speculative peers. Such was the case in the dotcom-fuelled bull market of the 1990s, when both low-volatility and higher-yield stocks materially underperformed their more speculative counterparts.

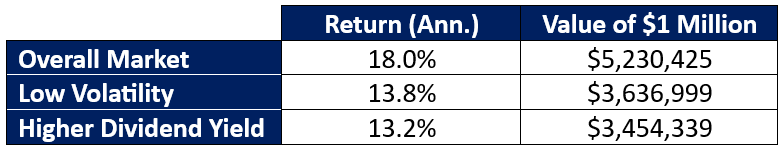
Low Volatility & Higher Dividend Yield Stocks vs. Overall Market (1990-1999)  

Notwithstanding the long-term outperformance of low volatility and higher dividend yielders, FOMO (fear of missing out) is a powerful force that can have perverse effects on behaviour. Many investors found it excruciatingly painful sitting with these holdings as they lagged the high-flying darlings of the day. None other than J.P. Morgan himself stated, “Nothing so undermines your financial judgement as the sight of your neighbor getting rich.”

Importantly, those who had the fortitude to stick with their low volatility and higher dividend yield holdings would have reaped significant rewards over the ensuing decade.

Low Volatility & Higher Dividend Yield Stocks vs. Overall Market (2000-2009)


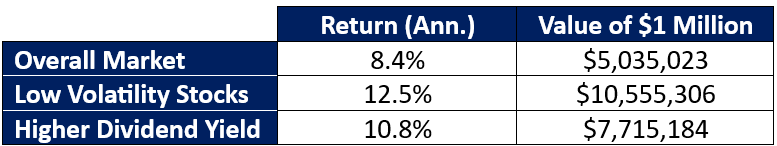
The trillion-dollar question is: When one incorporates the mechanics of compounding, how did low-volatility and higher-dividend-yield stocks fare over the entire twenty year “round trip” from 1990-2009? As the table below illustrates, investors who remained steadfast in the 1990s as their “boring” portfolios underperformed were more than compensated for their patience.

Low Volatility & Higher Dividend Yield Stocks vs. Overall Market (1990-2009)


Summing it all up, the historical data indicate:

  • Despite underperforming during periods of well above average returns that beget speculative fervor and unusually low risk aversion, low-volatility and higher-dividend-yield stocks have outperformed materially over the long term.
  • The relative performance of stocks with these characteristics is strongest in periods of market stress: they deliver outperformance and portfolio diversification when it is most needed.

Déjà Vu all over again

The outperformance of low-volatility and higher-dividend-yield stocks was particularly pronounced during the “lost decade” of 1999-2009, which is the only 10-year period since 1964 in which U.S. stocks had negative average annualized returns. However, these characteristics don’t need a highly unfavourable environment to shine, nor do rising markets necessarily cause them to underperform.

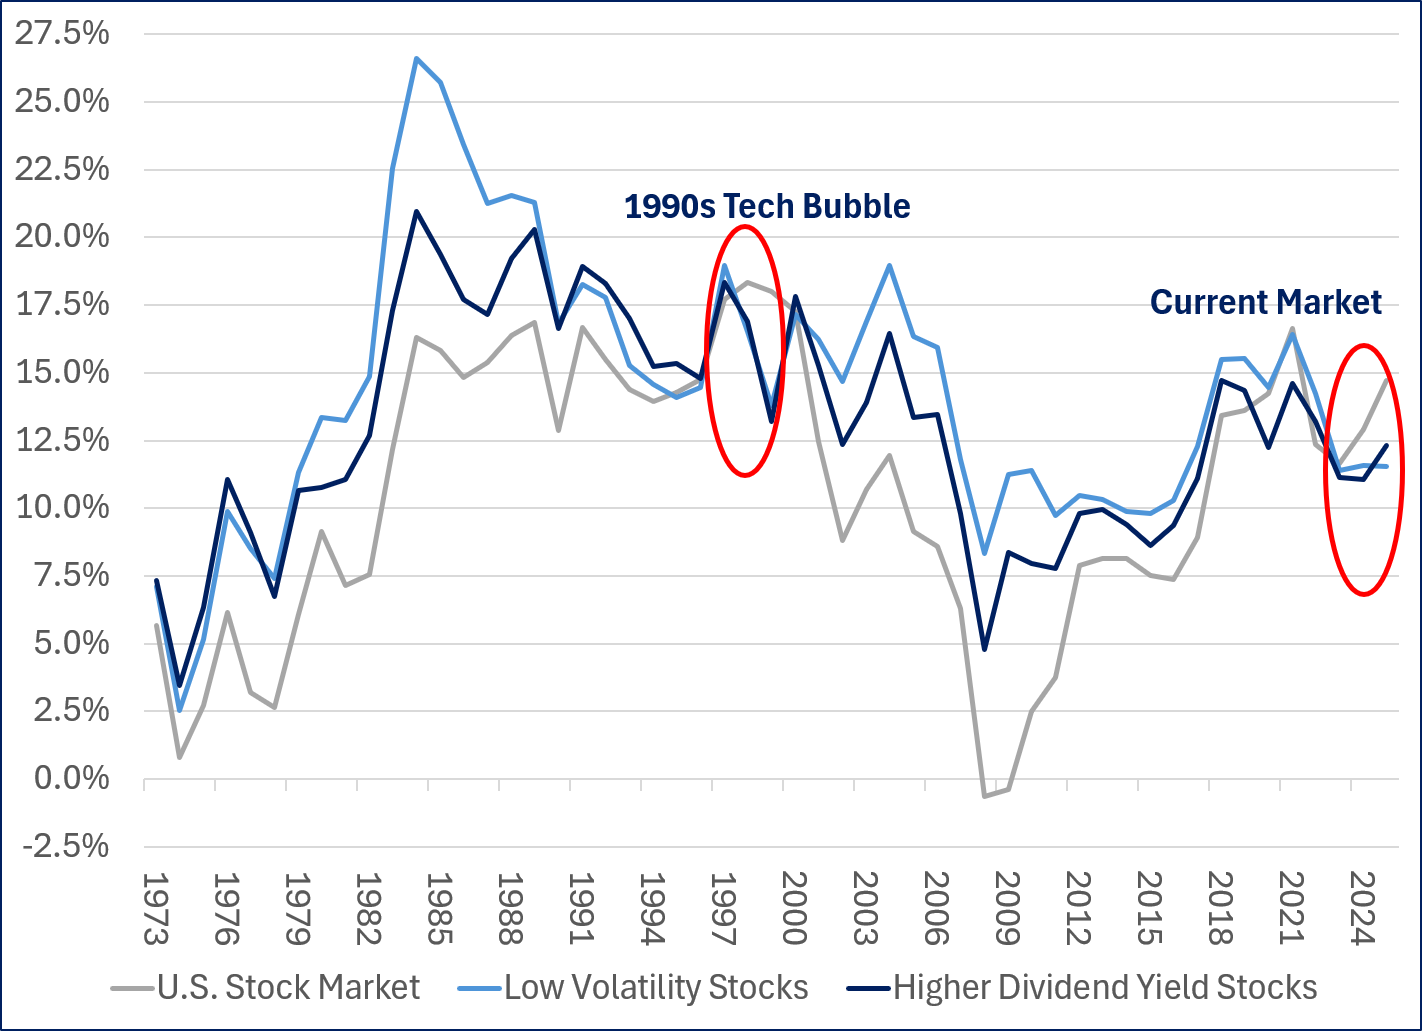
Low Volatility & High Dividend Stocks: Rolling 10-Year Annualized Returns (1964-2025)


From a historical standpoint, the underperformance of low-volatility and higher-dividend yield stocks over the past ten years is highly anomalous. The only other ten-year period that witnessed this phenomenon was the dotcom-based bull market of the 1990s, which was followed by an unusually strong period of outperformance for low-volatility and higher-dividend-yield stocks.

We can do this the Easy Way or the Hard Way

Since markets bottomed in March 2009 following the global financial crisis, the S&P 500 has delivered an annualized return of 16.4%, as compared to its long-term average of 10.2%. Continue Reading…

Part-Time Work in Retirement: Money and Purpose

Image created by Alain Guillot with ChatGPT


By Alain Guillot

Special to Financial Independence Hub

Most people think of retirement as the moment they finally stop working. But what if part-time work in retirement could make your life richer, not just financially, but socially, emotionally, and intellectually?

We spend decades saving and investing so that one day we can afford to stop working. Yet when that day arrives, many retirees discover something unexpected: having enough money doesn’t necessarily mean having a fulfilling life.

I believe there’s a better way to think about retirement. Instead of asking, “When can I stop working?” perhaps we should ask, “What kind of work would I enjoy doing if I no longer needed the money?”

That simple change in perspective can transform retirement.

My personal experience: Working because I want to

I’m approaching 60, and I consider myself financially independent. I’ve spent years saving and investing, and I’ve built enough financial resources that I don’t need employment income to support my retirement lifestyle.

Nevertheless, I continue working approximately 20 hours per week as a dance teacher, earning around $2,000 per month.

That’s $24,000 per year.

I don’t need this money to pay my bills. But I enjoy earning it, and I enjoy the work that produces it.

Teaching dance keeps me physically active. It allows me to meet people, maintain friendships, participate in my community, and feel that I’m contributing something valuable.

There’s also something deeply satisfying about getting paid to do something I genuinely enjoy.

My work gives structure to my week without dominating my life. I have plenty of time for reading, writing, investing, socializing, and pursuing other interests.

For me, this is an ideal balance between work and retirement.

And the additional income? That’s a wonderful bonus.

The Financial Power of Part-Time Work in Retirement

Let’s look at the numbers, because the financial benefits can be surprisingly large.

Financial planners frequently discuss the 4% rule, a retirement guideline suggesting that a retiree might initially withdraw approximately 4% of their investment portfolio annually, adjusting subsequent withdrawals for inflation.

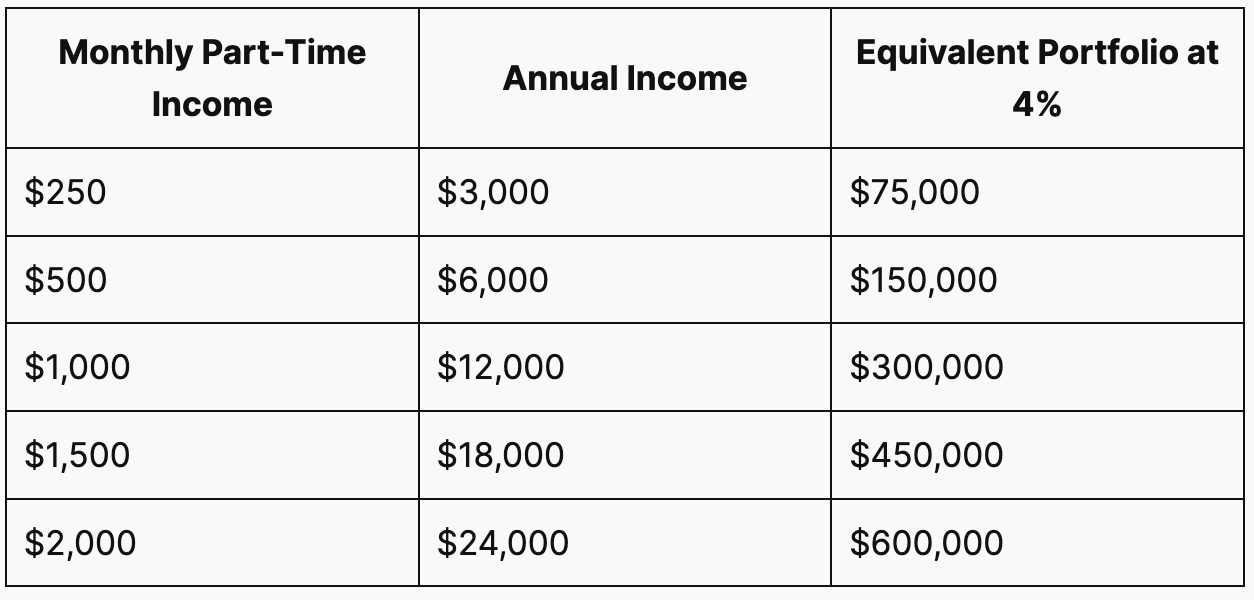
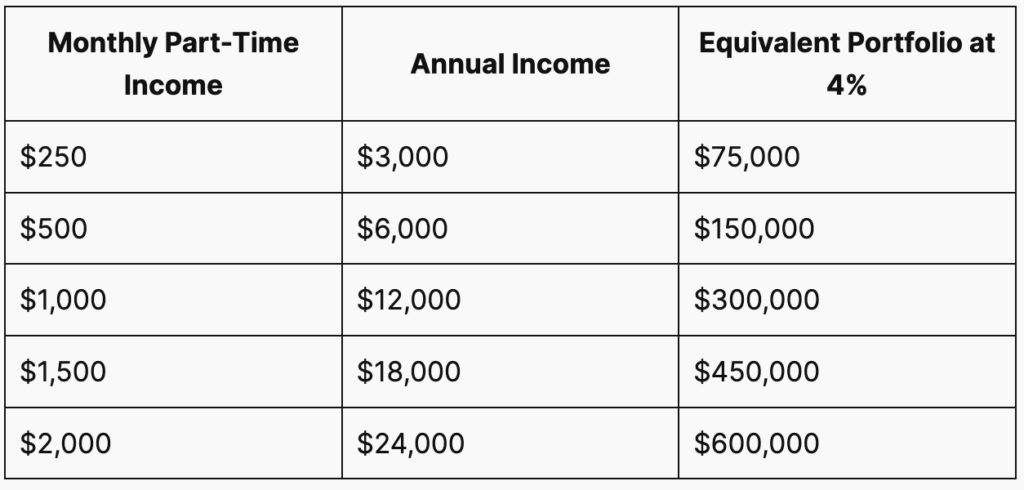
Under this framework, every $1,000 of annual retirement income is roughly equivalent to having $25,000 invested.

Consider the following examples:
Think about that last number.

By earning $2,000 per month teaching dance, I generate the same initial annual cash flow that a $600,000 investment portfolio would provide under the 4% guideline.

Of course, this doesn’t mean my part-time job is literally worth $600,000. Investment assets can appreciate, provide income without requiring work, and potentially be passed to heirs. Employment income depends on my continuing to work.

Still, the comparison illustrates how powerful even modest earnings can be.

You don’t need to Earn $2,000 per Month

Not everyone wants to work 20 hours per week.

Suppose you enjoy gardening and earn $500 per month helping neighbors maintain their gardens.

That’s $6,000 per year.

Using the same 4% comparison, this income is equivalent to the initial annual withdrawal from a $150,000 portfolio.

For someone concerned about having enough retirement savings, that additional income can make a meaningful difference.

The key isn’t to earn as much as possible. It’s to find an amount of work that improves your life rather than complicates it.

Four reasons to consider Part-Time Work in Retirement

1. Your Retirement Savings can Last Longer

One of the biggest financial concerns retirees face is outliving their savings.

Imagine two retirees, each with a $500,000 investment portfolio.

The first needs to withdraw $30,000 annually to cover living expenses.

The second has the same expenses but earns $12,000 annually from enjoyable part-time work. That person only needs to withdraw $18,000 from investments.

The difference is substantial.

By withdrawing less money, the second retiree gives their portfolio more opportunity to grow and recover from market downturns.

Over 10 or 20 years, this can meaningfully improve financial security.

The exact outcome depends on investment returns, inflation, taxes, and how long the person continues working.

2. You can Afford more Experiences

Not everyone wants to leave a large inheritance or accumulate the biggest possible investment portfolio.

Some people simply want to enjoy life.

An extra $500 or $1,000 per month could finance travel, restaurant meals, concerts, hobbies, or visits with family.

If your basic expenses are already covered by pensions and investments, part-time income can become discretionary spending money.

You might even create a simple rule: all earnings from your retirement gig go toward experiences rather than necessities.

Imagine paying for an annual vacation entirely with money earned from a hobby you enjoy.

That’s a pretty attractive arrangement.

3. Work provides Purpose and Social Connections

We often underestimate how much our professional lives contribute to our identities.

Work provides routines, challenges, relationships, and a sense of accomplishment.

When people retire, some lose these connections almost overnight.

Suddenly, there’s no workplace to visit, no colleagues to talk to, and no clear reason to get out of the house at a particular time.

For some retirees, that freedom is wonderful. For others, it can eventually lead to boredom, isolation, or a loss of purpose.

Part-time work offers a middle ground.

Retirement also gives us the freedom to explore new social activities and become more involved in our communities. For example, attending live comedy shows is a great way to meet people, enjoy an evening out, and support local performers. Whether through dancing, comedy, or other community activities, staying socially engaged can make retirement more fulfilling.

In my case, teaching dance gives me regular opportunities to interact with people. I meet students, share experiences, laugh, and participate in an active social environment.

I don’t think of those hours as an obligation. They’re an enjoyable part of my life.

The money matters, but the relationships matter just as much.

4. Work can keep your Mind and Body Active

Retirement shouldn’t mean withdrawing from life.

Depending on the activity, part-time work can provide physical movement, mental stimulation, and opportunities to learn new skills.

A retired accountant helping small businesses might enjoy solving financial problems.

A former teacher tutoring students might find satisfaction in watching young people improve.

A retiree working at a garden center might enjoy spending time around plants and other gardening enthusiasts.

As a dance teacher, I have the added benefit of staying physically active while working.

Of course, paid employment isn’t the only way to obtain these benefits. Volunteering, hobbies, community organizations, and family activities can be equally meaningful.

But when enjoyable work provides those benefits and generates income, it becomes especially attractive.

The Best Retirement Job is not necessarily the highest-paying One

During our working years, we often make career decisions based on salary, promotions, and financial obligations.

Retirement gives us the opportunity to change those priorities.

You might accept a lower-paying job because you enjoy the people, the activity, or the flexibility.

A retired executive who once managed hundreds of employees might be perfectly happy working two mornings per week in a bookstore.

Someone who spent decades sitting behind a desk might enjoy walking dogs.

A former engineer might discover that teaching mathematics to teenagers is more satisfying than managing large projects.

The goal is not to maximize income. The goal is to maximize life satisfaction.

That’s an important distinction.

If your retirement job creates stress, damages your health, or prevents you from enjoying your freedom, it may defeat the purpose.

(Affiliate link added by Editor: And if a health setback ever interrupts an income you’ve come to rely on, that’s the gap disability insurance exists to fill.)

Seven Part-time Jobs worth considering in Retirement

Here are some possibilities that can combine modest income with personal satisfaction:

  1. Teaching or tutoring: Share your expertise in languages, mathematics, music, dance, or another subject. My friend Cheryl teaches English as a second language and she loves it.
  2. Pet sitting or dog walking: Spend time with animals while earning additional income and staying active.
  3. Consulting: Offer your professional knowledge to businesses without returning to full-time employment.
  4. Tour guiding: Share your enthusiasm for local history, architecture, or culture with visitors.
  5. Freelance writing or editing: Work from home on a flexible schedule, especially if you enjoy communication.
  6. Gardening or home services: Help neighbors with landscaping, small repairs, or seasonal projects.
  7. Working in a bookstore, museum, or community center: Combine a pleasant environment with regular social interaction.

The possibilities are nearly endless.

You could also turn an existing hobby into a small business, although not every hobby needs to become a source of income.

The most important question is whether you would still enjoy the activity after it becomes a paid responsibility.

How to choose the Right Retirement Gig

Before accepting a part-time job or starting a small business, consider a few questions.

Would I enjoy doing this even if I didn’t need the Money?

This is my favorite test.

If the answer is yes, you’re probably moving in the right direction.

How much Time am I willing to Commit?

For me, 20 hours per week feels comfortable.

For someone else, five hours might be ideal.

There’s no universal answer. Your schedule should leave enough time for everything else you want to experience.

Will the Work Improve my Social Life?

Some jobs provide regular opportunities to interact with others.

Others, such as freelance writing, might involve working alone.

Neither is inherently better. Choose according to your personality and needs.

Will it Create Financial or Administrative Complications?

Additional income can affect taxes, income-tested government benefits, and eligibility for certain programs.

In Canada, for example, employment or self-employment income may affect benefits such as the Guaranteed Income Supplement. Old Age Security recovery tax rules may also matter at higher income levels.

Self-employed retirees should also account for business expenses, applicable pension contributions, and tax obligations.

The financial benefit should be evaluated using after-tax income, not just gross earnings.

Part-time Work can also Reduce Retirement Anxiety

One of the psychological challenges of Retirement is transitioning from accumulating money to spending it.

For decades, we develop the habit of saving.

Then suddenly we’re supposed to start withdrawing from our investments.

Even when the mathematics suggests that we have enough, spending down our savings can feel uncomfortable.

Part-time income can help ease that transition.

Knowing that money continues arriving every month may make it easier to enjoy retirement without constantly worrying about investment balances.

I find that my own earnings provide an additional sense of security, even though my financial plan doesn’t depend on them.

If markets decline, I have some income that doesn’t require selling investments.

That flexibility is valuable.

It doesn’t eliminate investment risk or guarantee financial security, but it creates another layer of protection.

Don’t Postpone Retirement just to keep Earning Money

There’s an important warning here.

I am not suggesting that everyone should continue working indefinitely.

Some people have spent decades doing physically demanding jobs. Others have health problems, caregiving responsibilities, or simply no desire to work anymore.

For them, retirement without employment may be the best possible choice.

And if you already have enough money, there’s no reason to sacrifice your freedom for additional income you don’t need.

The objective is not to turn retirement into another career.

It’s to recognize that work can be one of several enjoyable activities in a fulfilling retirement.

You should feel free to stop whenever the activity no longer brings you satisfaction. Continue Reading…
Theme Investing: Trendy stocks will often lead you into losses

Theme investing, particularly when snatched from the latest headlines, may seem appealing: but more often than not will lead to poor returns

TSInetwork.ca

Theme investors zero in on something that’s going on in the world — in business, politics, technology or society as a whole — and try to cash in on it, directly or indirectly. You can get lucky with trendy theme investing, but there’s a large element of risk. Interest in the theme may slump sooner than you expected. Or, your enthusiasm for the theme may lead you to drop your guard. It may spur you to put money in stocks or other investments that are drastically over-priced or fundamentally flawed.

Focusing on a theme that’s in the headlines can help you identify potentially high-profit investment and business opportunities. But trying to cash in on a theme is inherently risky.

An example of theme investing in the resource sector

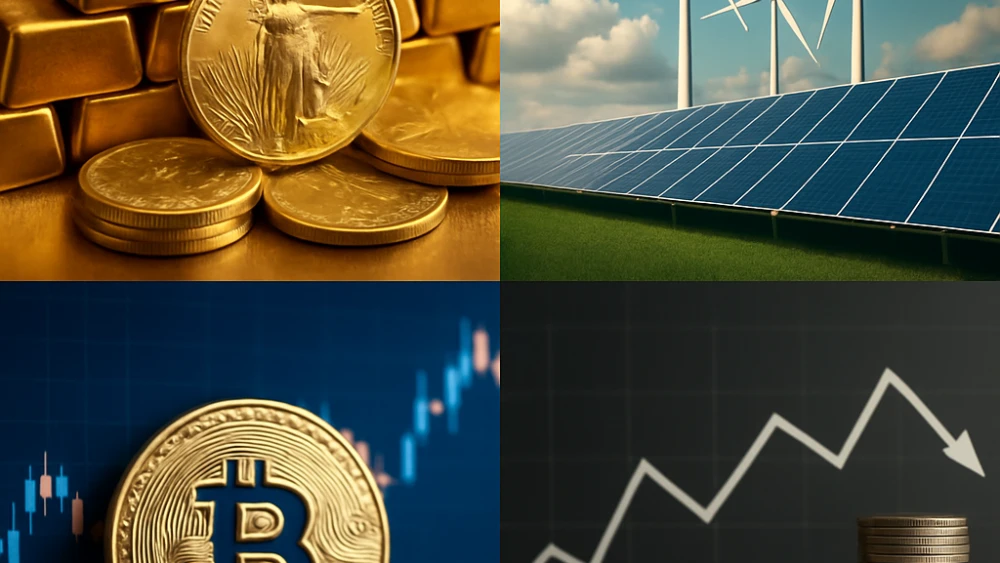
For example, the rising price of gold was a popular investing theme during much of the first decade of this century. As gold rose from under $300 to more than $1,800 per ounce, it presented a wide variety of profit-making opportunities. But the rising price of the metal was no guarantee of profit. Gold-themed investments — collectors’ coins, penny stocks, gold-based futures and options trading — gave promoters lots of ways to create low-quality investments to sell to gold-seeking investors.

Theme investing within the green energy market

Green energy comes from renewable resources like solar power, wind power, geothermal power and generating electricity from ocean waves. Green energy investing has become more popular in the past few years, as concern over the environment has grown.

Green energy can be considered to be an investment theme. However, as with all investment themes, we’ve always recommended that you choose green energy stocks very carefully to profit. That’s because many of these companies have only limited investment appeal.

Investors interested in green energy should know that these firms often need a long time to move from the research or concept stage to profitability. As well, governments often cut subsidies for renewable energy development when they struggle with high budget deficits.

To cut your risk, we recommend that you focus on green energy stocks that already have a sound base of other operations, preferably businesses that provide steady revenue streams. That helps offset the risks of expanding into renewable-power production.

Avoid theme investing in ETFs or mutual funds

If the ETF or mutual fund’s theme seems to be plucked from recent headlines, stay away. It pays to stay out of narrow-focus, faddish funds, all the more so if they’ve come to market when the fad dominates the financial headlines. Good examples are ETFs or other funds that invest in cryptocurrencies or related firms.

Trendy theme funds like these face a double disadvantage because they appeal to impulsive investors who pour in their money just as the fad hits its peak. This forces the manager to pay top prices —  perhaps to bid prices higher than they’d otherwise go — even if this goes against their better judgment. These same investors are also apt to flee when prices hit their lows, forcing the ETF or mutual fund manager to sell at the bottom and lowering the fund’s performance. But when a fad fades, as they all do, the fund’s liquidity dies out with it. The manager may have to dump the fund’s holdings when demand is at its weakest, forcing prices lower than they would otherwise go.

The appeal of theme investing tilts the odds against you in two ways

First, the appeal of hot themes attracts naïve investors. They, in turn, bid up the prices you have to pay to invest.

Second, the excitement surrounding the theme attracts opportunists who simply want to create investments and business ventures that are easy to sell, regardless of their chance of long-term success. This cuts the average quality of available investments. Continue Reading…