For young couples starting families, buying their first home and/or other real estate. Covers mortgages, credit cards, interest rates, children’s education savings plans, joint accounts for couples and the like.
Evidence over emotion. Process over prediction. Better decisions over better guesses.
Most financial decisions eventually tell you how they turned out. Choosing your executor never will.
You will not be there to see whether the person you named handled it competently, whether your children are still speaking to one another afterward, or whether the estate settled in eight months, three years or longer.
As I wrote in the first article in this series we judge decisions by their results almost automatically. Here no result is available to judge. The reasoning is the only thing you will ever have, which is a good argument for doing it properly.
What would have to be true for your choice to work?
Most people name an executor the way they would hand out an honour. The oldest child. The sibling who is good with money. The person who would be hurt to be passed over.
A better test is the one this series keeps returning to. What would have to be true for this person to be the right choice?
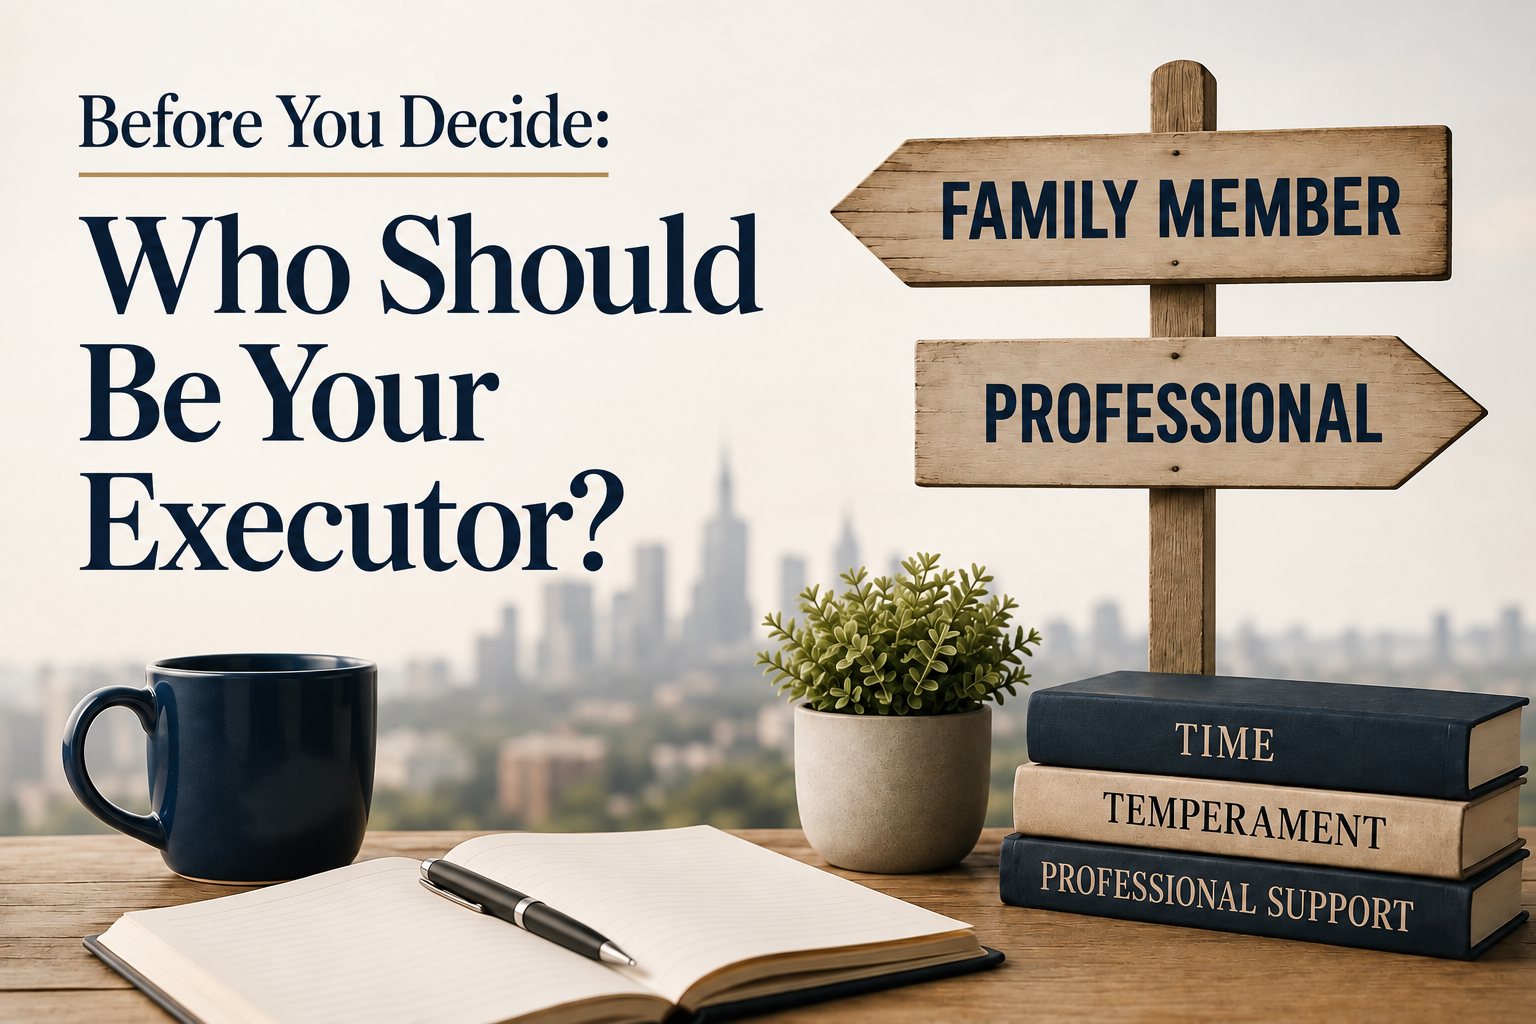
Three things. They need the time. They need the temperament to hold a position under pressure from people they love. And they need the willingness to pay for professional help rather than guess. Most executors are appointed without anyone testing a single one of those conditions.
How much time does being an executor take?
Estate practitioners commonly estimate 100 to more than 400 hours, spread over twelve to thirty-six months or sometimes longer. Treat that as practitioner judgment rather than a measured Canadian average, because no reliable average exists. At the upper end, 400 hours is ten full working weeks to fit around a job and a family, often while grieving.
The value of the estate tells you less than you would expect. An organised portfolio can be easier to administer than a modest estate with awkward complications. A family member or other beneficiary may need to be located if you have lost contact with them. One living outside Canada brings legal, tax, currency, and cross-border considerations. Property abroad may require local legal and real estate expertise. Complexity comes from family circumstances and where assets sit, not from the size of the balance.
The unpredictable demands are harder still. One beneficiary wants the cottage sold, another wants to keep it, and your executor referees while explaining why nobody is being paid as quickly as they expected.
Can an executor be personally liable?
Yes, and this is the part most people never hear before they agree.
If an executor distributes estate assets without obtaining a clearance certificate from the Canada Revenue Agency, and tax remains owing, the executor can be personally liable up to the value of what was distributed. That includes amounts assessed after the money is gone. CRA does permit distributions before a certificate is issued if enough property is held back to cover the liability, so an executor needs advice on how much to retain.
Picture explaining to your siblings that part of their inheritance has to wait, even though the investments are sold and the cash is sitting in the account. From where they stand there is no visible reason for the delay. Your executor confirms the estate’s tax position anyway, and absorbs the resentment while doing it.
This is why temperament matters as much as financial knowledge. The person needs to be comfortable keeping records, explaining decisions, and saying no to people who will not enjoy hearing it.
Is your executor paid for this work?
They are entitled to be, and that is worth knowing before you compare options.
Ontario uses a long-standing guideline of 2.5 per cent of capital receipts and 2.5 per cent of capital disbursements, with the same rates on revenue in and out, plus a care and management fee of up to 0.4 per cent per year on the average value of the estate. Add those together and you arrive at the rough five per cent of estate value that people usually quote.
It is a guideline, not an entitlement. Courts assess what is reasonable against the size of the estate, its complexity, the time and skill required, the results achieved, and the responsibility assumed, and they can award less. A family member may waive compensation. Many do not, and they are not wrong to claim it, because the work is real.
Estate administration tax, still widely called probate fees, belongs in the same conversation. In Ontario there is nothing payable on the first fifty thousand dollars, and roughly 1.5 per cent on the value above that. It drives both the cost of settling your estate and the timeline your executor will be defending to impatient beneficiaries.
Should you appoint a professional?
It is a reasonable option, particularly where wealth is passing to the next generation, and interest in it has been growing.
There is more than one way to do it. A trust company can be appointed executor outright. Firms also act as agents, handling the administrative work while a family member stays the named executor, which keeps your family in control of decisions while removing most of the paperwork.
Be clear eyed about cost. Fees are generally a percentage of the estate and can look startling next to a family member doing it for nothing. The honest comparison is fee against fee rather than fee against free, since a family executor is entitled to compensation too. What you are buying is experience, fewer expensive mistakes, and someone absorbing conflict that would otherwise land on your children. Pricing and scope differ meaningfully, so compare before committing.
What about your power of attorney for property?
The person you appoint under a power of attorney for property manages your financial affairs during your lifetime, and that authority ends when you die. An executor deals with your estate afterward.
The same person may suit both roles, but assess them separately. Managing bills, investments, and care costs can mean years of continuous decisions. Someone willing to settle your estate may not have capacity for that.
Is there an estate decision where you do see the result?
One, and it deserves more attention than it gets.
If you have wealth beyond your own lifetime needs, giving during your lifetime is a real alternative to leaving a larger estate. Once affordability and the tax position are worked through, money given while you are alive arrives when the people receiving it can actually use it, rather than decades later when they may not need it at all. Continue Reading…
Claiming Social Security early can provide immediate income, but it may reduce future benefits and limit financial flexibility. This article examines key factors such as debt, longevity, cash reserves, survivor protection, and income planning.
Insights from financial experts help readers compare options and make more informed timing decisions.
Preserve Flexibility amid Program Uncertainty
It depends on life stage. Younger clients may want to plan for 75% of benefits on the dollar. While scenarios for pre-retirees can range from reduced benefits to a flat non-inflation-adjusted benefit.
The decision making math remains the same. It’s still too early to tell exactly what will happen with Social Security. Pre-retirees should still consider income needs and longevity over how benefits might change.
To hedge this risk pre-retirees should build flexibility within their retirement plan. Locking income into guaranteed lifetime payments makes it harder to pivot if benefits change. — Samuel Resultan, Financial Consultant, Voyage Wealth Management
Postpone CPP and OAS for Raises
For Canadians who can keep working — or who have other income to bridge the gap — delaying CPP and OAS is one of the few guaranteed raises in retirement. According to Service Canada, CPP grows 0.7% for every month you delay after 65, up to 42% more at 70, and OAS grows 0.6% a month, up to 36% more at 70. Those larger payments are permanent and indexed to inflation, so delaying is really buying longevity insurance: the longer you live, the more it pays. It is not right for everyone. If you need the income now, have health concerns, or qualify for the Guaranteed Income Supplement, starting earlier can make sense. But if you are healthy, still working, and can cover expenses in your late 60s from savings or part-time income, run the numbers on waiting before you default to 65: 65 is just the standard age, not a deadline. — Rohit Dahiya, Founder, LearnLoonie.ca
Keep Cash Reserves for Deferral
The national debt and the Social Security trust fund get lumped together, and they’re separate problems. The trust fund is what matters here. The trustees project it runs short in the early 2030s, and after that incoming payroll taxes still cover roughly 80 per cent of scheduled benefits. That’s a cut. It isn’t zero.
So run the numbers with the cut baked in. If waiting to 70 still wins at 80 cents on the dollar, and for a healthy married person it usually does, the headline doesn’t change the answer. If a cut comes it would most likely be across the board, which means the person who claimed at 62 takes it on a check that was already about 43% smaller than the age-70 amount.
Claiming early does make sense with poor health, or for the lower earner in a couple whose check won’t become the survivor benefit. Taking it early to invest only works if it actually gets invested. In my experience it usually gets spent.
The better hedge is a cash reserve, so you’re never forced to claim early in a bad year. — Hans Goldstein, Founder, Structured Installment Sales & Exit Tax Planning, Hans Goldstein: Tax & Exit Planning
Stress-Test Income and Build Reserves
My numbers don’t change much. The US$40 trillion national debt is a separate problem from the Social Security trust fund shortfall. The biggest risk to me is that the retirement fund will be exhausted by 2033, at which time about 77% to 80% of scheduled benefits will continue to be paid from current payroll taxes. Any cut to benefits will be proportional, so that a reduced cheque at age 70 is still larger than a reduced cheque at age 62. For Canadians, the biggest risk to the plan is zero. But the CPP is a separately funded plan, and the chief actuary reports that it will be “sustainable” for 75 years.
There is some justification to taking your retirement benefits early, but the reward for waiting past full retirement age to take benefits is significant. Generally, one can earn 8% per year more in guaranteed, inflation-adjusted income by delaying retirement benefits past full retirement age. Waiting to take retirement benefits early is therefore justified by poor health, short family longevity, or no spouse to receive survivor benefits.
Calculate how much you need to have to run the plan at 75% of your projected benefit. If the number is still sustainable, then the rest of the news is irrelevant. Use your 401(k) or RRSP to “bridge” to 70. The effect of lowering your required withdrawals and taxes in retirement will be dramatic. Keep 2-3 years of required retirement spending in cash or very short-term bonds. The worst crash ever will not force you into early retirement. Pay off your mortgage before retirement. The worst fixed cost in retirement is yourself. — Ace Zhuo, CEO | Sales and Marketing, Tech & Finance Expert, TradingFXVPS
Let Longevity guide your Timing
Myth: Since the trust fund is running short anyway, I should “take it early and grow it.”
Social Security claiming age has little to do with markets or investment-return guesses, and a lot to do with longevity and breakeven. Will you, or a spouse who may rely on survivor benefits, live long enough for the delayed retirement credits (the increase you earn by waiting past full retirement age, up to 70) to outweigh the permanent reduction for claiming between 62 and full retirement age? That math does not need an investment-return assumption.
Trust fund shortfall talk changes the risk story, not the formula. According to the SSA trustees, if Congress takes no action, scheduled benefits can be paid until the OASI reserve is used up. After that, ongoing payroll tax revenue covers only a portion of scheduled benefits, and that cut applies to everyone, not just those who delay. So claiming earlier does not create a protected pocket outside the same rules.
Instead of “take it early and grow it,” model these:
Your primary insurance amount at full retirement age, then the reduction or delayed-credit bump at your claim age.
Spousal and survivor benefit interactions.
Taxes and Medicare: other income can make benefits taxable and affect IRMAA, and working before full retirement age can trigger the earnings test.
A cash-flow bridge if you delay, with a tax dry-run on withdrawals from other accounts.
Check your Social Security account often to keep your earnings record clean, and revisit your claiming age when health, work plans, or a spouse’s age changes. — Mehdi Zare CFA, Founder, Bina Capital
Clear Debt before you File
I’m Nick Avila, founder of United Debt Relief. I’ll leave the investment math to planners and add the part most claiming advice skips: your own debt.
First, the cut. The 2026 Social Security Trustees Report projects the combined trust funds will be depleted in 2034, with enough income at that point to pay 83% of scheduled benefits if Congress doesn’t act. That’s a real risk. It’s also a partial cut, not zero, and under current law it would apply to early and late claimers alike. So on its own, I think it’s a weak reason to lock in a permanently smaller check.
And the early-claiming penalty is permanent. For anyone born in 1960 or later, SSA says claiming at 62 pays 70% of your full benefit, and each year you wait past 67 adds 8% until 70.
Where I do see early claiming make sense is Debt. If someone reaches 62 carrying credit card balances, at the 22.15% average rate the Federal Reserve reports for accounts charged interest, and has no other way to pay them down, using early benefits to clear that debt can beat letting it compound for years while they wait. It’s an expensive fix, though. I’d much rather see people clear the cards from earned income in their late 50s and keep the option to delay.
The hedge I wish more people knew about is legal, not financial. The CFPB notes that when benefits arrive by direct deposit and a bank gets a garnishment order, two months of benefits are protected in the account, and Social Security is shielded from most private debt collectors. Government debts are different. Back taxes and defaulted federal student loans can be collected from benefits, and SSA says the IRS can levy up to 15% of payments for overdue federal taxes.
So the best hedge against a smaller cheque is entering retirement without federal tax debt or a defaulted federal student loan, because those can follow you straight into your Social Security payment. Everyone’s situation is different, so run your own numbers with a fee-only planner before you decide when to claim. — Nick Avila, Founder, United Debt Relief
Protect Survivors with Layered Coverage
We need to keep in mind that current warnings refer to reducing the benefits, not their elimination, and waiting to claim typically results in higher payments. Claiming early translates into a permanently lower benefit and introduces market risk, which may not outweigh the guaranteed increase from delaying.
While indeed this approach will work for some individuals, it should be reviewed with a licensed financial advisor case by case rather than applied broadly.
One critical factor families often overlook is the impact on the surviving spouse. After the higher-earning partner passes away, the survivor generally receives the larger Social Security payment. If the higher earner claims early, the surviving spouse may have to rely on a smaller benefit for many years.
Relying on a single income source is not advisable. In my 18 years in the insurance career, I have observed that retirees who feel most secure use multiple layers of protection, such as combining Social Security, savings, and life insurance designed to replace lost spousal income. When one income stream ends due to a spouse’s death, life insurance can help fill that gap, allowing the surviving spouse to remain in the home.
This is not an investment strategy per se, but a way to ensure that benefit reductions, market downturns, or loss of a spouse do not impact the same person all at once. — Jeremy Hewett, President and Chief Executive Officer, AccuQuote
Diversify Globally against Sovereign Risk
With over 20 years advising private equity and multinationals on capital advisory, I evaluate statutory retirement benefits through the lens of sovereign counterparty risk. When a public balance sheet faces severe long-term debt, relying entirely on static future payout models introduces regulatory uncertainty that you cannot control.
There is a sound strategic argument for claiming early if you systematically redirect that cash flow into liquid global equities and high-yield operational investments. Taking the liquidity immediately places capital allocation back under your direct governance rather than leaving it exposed to future legislative restructuring.
A strong hedge against single-country entitlement reform is geographic and jurisdictional diversification. By structuring assets across multiple international corporate entities and foreign-denominated holdings, you insulate your broader wealth plan from the fiscal pressures of any single government. –– Sebastien Gaddini, Principal, Corpiya
Delay Social Security despite Potential Haircuts
The $40 trillion debt headline is genuinely alarming, but let’s separate two distinct issues that often get conflated: the national debt is a real long-term fiscal challenge, while Social Security’s funding shortfall is a separate, more immediate, and more precisely quantifiable problem tied to payroll tax revenue versus benefit obligations, not general federal debt. The Trustees project trust fund depletion around 2033-2034, potentially triggering an automatic 20-25% benefit reduction if Congress takes zero action, which I consider unlikely but not impossible.
Does this change my calculation on delaying to 70? Not dramatically, and here’s the math explaining why. Delaying benefits still guarantees roughly 8% annual increases between full retirement age and 70. Even if benefits get reduced by 20-25% starting in 2034, that reduction would apply proportionally whether you claimed at 62, 67, or 70, since cuts would adjust the overall benefit formula, not penalize delayed claiming specifically. So delaying still produces a larger base benefit before any potential haircut, meaning you’d still come out ahead with delayed claiming even under reduction scenarios, just with a smaller total than originally projected.
The “take it early and invest for growth” argument does have some legitimate mathematical appeal, particularly if you’re disciplined enough to actually invest rather than spend the money, and if market returns cooperate. Historically, an 8-10% average stock market return could theoretically outpace the guaranteed 8% delayed retirement credit.
I recommend three approaches: first, build retirement income diversification beyond Social Security through IRAs, 401(k)s, and if available, guaranteed income products like annuities, reducing total dependence on any single income source. Second, maintain flexibility in your claiming strategy, some financial planners now recommend claiming slightly earlier than 70, perhaps at 67-68, splitting the difference between maximizing benefits and hedging against uncertainty. Third, stay politically engaged and informed, since historically Congress has always intervened before depletion deadlines through payroll tax adjustments or formula changes, meaning the doomsday scenario, while theoretically possible, remains historically improbable given the political consequences of inaction. — Loretta Kilday, DebtCC Spokesperson, Debt Consolidation Care
Model a Reduced Future before Claims
I would not treat the Social Security funding warning as an automatic reason to claim early. I would instead stress-test the retirement plan as though future benefits will be lower, then make the claiming decision based on longevity, cash needs, and risk tolerance. Continue Reading…
As those who follow me on social media may already know, financial guru David Chilton interviewed me on his popular The Wealthy Barber podcast, which dropped Tuesday on YouTube.com. You can find the full 39-minute clip here: try 1.5x speed if you’re pressed for time!
David is a good interviewer and got me to confess a few things I might not have coughed up otherwise. Mostly, we chatted about personal finance in Canada, retirement and retirement planning and — a particular concern for David — the plight of young Canadians priced out of the Canadian real estate market. This included a discussion of our own family’s situation and how the “Bank of Mum and Dad” may be enlisted to supplement down payments scraped up by some combination of TFSAs, the RRSP Home Buyers Plan and the new First Home Savings Accounts (FHSAs) that David is quite enthusiastic abøut.
Naturally we talked about Retirement. David himself is retiring at the end of this year soon after he turns 65, so he will have “beaten” me to Full Retirement by roughly eight years. I wrote about his looming Retirement recently in my MoneySense Retired Money column, which was also flagged here on Findependence Hub.
A Who’s Who of Canadian Personal Finance
I was David’s 71st interview on the podcast since he launched it two years ago: he says he plans to keep it going at least until the end of this year. As I comment in the interview, his many guests constitute a veritable “Who’s who” of Canadian personal finance, with a handful of Americans thrown in.
Glad to be part of it and to join such luminaries as Ben Felix, Preet Banerjee, Rob Carrick, Fred Vettese and many more. As David notes, a lot of his guests are younger newer voices known as “Finfluencers,” a group I also wrote about in Retired Money earlier this summer.
We also discuss other more “seasoned” financial commentators, including Bruce Cohen, Ellen Roseman, Jim Daw, Mike Grenby and other pioneers of the genre. Some of those veterans’ names came up in another Retired Money interview I did after Rob Carrick retired a year ago from his full-time job at the Globe & Mail.
The financial novels spawned by The Wealthy Barber
With an estimated 4- to 5- million copies of his books sold worldwide, it’s no surprize that Chilton’s pseudo-fiction financial format spawned many imitators. I fondly recall Jim Daw (retired from the Toronto Star) cracking a joke about the many financial novel knockoffs inspired by The Wealthy Barber. Rather than a “branch” of personal finance literature, Jim quipped in his review of my own Findependence Day that this specialized field consituted merely a “twig” of the genre.
While much of the interview was perforce about investing and retirement, good interviewer that he is David manages to coax some confessions about my own lifestyle and choices. For example, I tackled headon the fact that the title of my own similarly titled The Wealthy Boomer was not initially conceived as a ripoff of Chilton’s far more commercially successful The Wealthy Barber: that title was just a description of the possible demographic target for the book’s publisher.
We also talked about 12 Good Years, the blog that blogger Fritz Gilbert originally ran on his Retirement Manifesto blog. That article make she case that new or aspiring retirees should strive to make the best of the years between ages 60 and 72, whether for strenuous travel or demanding hobbies, physically or mentally. Continue Reading…
Avoid common estate planning mistakes that can complicate inheritance, taxes, and family decisions. Learn what Canadians should review before retirement.
Image Adobe Stock via Logical Position
By Dan Coconate
Special to Financial Independence Hub
Estate planning can feel like a task for another day, particularly when retirement already brings decisions about income, investments, housing, and lifestyle. Yet an estate plan affects far more than what happens to your assets after death. It can also shape who manages your finances during incapacity, how efficiently your estate moves to beneficiaries, and how much work falls on family members.
For Canadians approaching or enjoying retirement, the strongest plans usually come from looking at the entire financial picture rather than treating a will as a standalone document. There are many things people get wrong when planning their estate, from stopping at writing a will to choosing an executor solely due to familial ties. Avoiding these mistakes can help make your wishes clearer and reduce unnecessary complications for the people who eventually carry them out.
1.) Thinking a Will is the Entire Estate Plan
A will plays a central role in estate planning, but it does not cover every situation. A will generally takes effect after death. Other documents and arrangements address what happens while someone is still alive but unable to manage financial or personal matters. Powers of attorney, beneficiary designations, insurance policies, jointly held assets, and trusts may all form part of the larger picture.
It’s best to plan for both a will and appropriate powers of attorney as part of preparing financial affairs for later life. The distinction matters because an estate plan should address both asset distribution and continuity during incapacity.
2.) Assuming every Asset passes through the Will
A will does not automatically control every asset a person owns. Certain assets may transfer according to their ownership structure or beneficiary designation rather than instructions in a will. Registered accounts, insurance policies, jointly owned property, pensions, and other financial arrangements can require separate consideration.
That makes an asset inventory valuable. List financial accounts, real estate, insurance, business interests, investments, debts, and significant personal property, then determine how each item would transfer.
3. Choosing an Executor because they are the Closest Relative
Another thing many people get wrong when planning their estate is who they choose as an executor. Naming an executor can look like an honorary gesture, but it comes with serious responsibilities.
An executor may need to locate assets, protect estate property, deal with creditors, handle tax matters, complete legal procedures, and distribute property to beneficiaries. The executor is a key figure in administering the estate and carrying out the deceased person’s wishes.
The best choice may not be the eldest child or nearest family member. Consider financial ability, organization, availability, location, and willingness to handle the work.
4. Forgetting to Plan for Incapacity
Estate planning should not begin at death. Illness, cognitive decline, or an accident can leave someone unable to manage banking, investments, bills, or property. Without the correct legal authority in place, relatives may discover that family relationships alone do not give them the right to take control.
For example, in Ontario, even a spouse or family member does not automatically gain authority to manage another person’s property when that person becomes mentally incapable. The terminology and rules differ across Canada, so residents should review the appropriate documents for their province or territory.
5. Treating Beneficiary Designations as a One-time Decision
A beneficiary designation made many years ago may no longer reflect current intentions. Marriage, separation, divorce, deaths, births, retirement, and changes in family relationships can all alter what makes sense. A beneficiary on an old account can create an unpleasant surprise if the rest of the estate plan has changed, but the designation has not.
Review beneficiary information whenever a significant life event occurs. A periodic review during retirement can also reveal outdated forms before they create a conflict.
The important point is consistency. The will, financial accounts, insurance arrangements, and broader estate strategy should work together rather than point in different directions.
6. Assuming Trusts work the same way everywhere
Trusts can play an important role in some estate plans, but Canadians should be careful when reading general financial information in another country. Terms such as “revocable living trust” appear frequently in U.S. estate-planning discussions. Canadian tax treatment, probate rules, trust law, and estate administration can differ considerably by province and from American practice. Continue Reading…
Even when parents try to shield their children from financial worries, a new study suggests kids are hearing more than parents realize.
As the cost of living continues to squeeze Canadian households, a new survey from Vanguard Canada suggests the strain isn’t confined to parents’ bank accounts; it’s also shaping how their children think and feel about money too.
The survey of just over 1,000 Canadian parents of children under 18 found that households that talk openly about money raise more financially literate kids, while households that avoid the subject may be doing more harm than good.
The Instinct to Protect backfires
Many parents try to keep financial stress away from their kids. Among parents who describe themselves as financially stressed, more than two thirds said they feel pressure to hide their worries from their children, and roughly a third said they avoid discussing money at home altogether.
But the survey suggests that instinct doesn’t work the way parents hope. Seven in ten financially stressed parents said their children overhear money conversations anyway. In fact, those children were found to be nearly five times more likely to feel anxious about money than their peers.
Sal D’Angelo, Head of Vanguard Investments Canada, said children pick up on far more than parents assume, even when adults try to keep financial matters private. He framed early financial education as key to helping the next generation build healthy money habits.
A Literacy Gap that starts early and closes late
The survey also points to a timing problem. Households where money is discussed regularly produce children with markedly stronger grasp of core concepts like banking, debit and credit, which is nearly three times higher comprehension according to the findings.
Yet the majority of parents said substantive money conversations don’t begin until their child is between 15 and 18 years old, well after attitudes toward money have already started to form. Continue Reading…


 Posted By

 Posted By