Debt & Frugality

As Didi says in the novel (Findependence Day), “There’s no point climbing the Tower of Wealth when you’re still mired in the basement of debt.” If you owe credit-card debt still charging an usurous 20% per annum, forget about building wealth: focus on eliminating that debt. And once done, focus on paying off your mortgage. As Theo says in the novel, “The foundation of financial independence is a paid-for house.”

How to find the Money Leaks you don’t know about

Image created with Grok Imagine by Expense Canary

By Karla Castro

Special to the Financial Independence Hub

Most of us know roughly what we spend on rent, groceries and gas. The harder money to track is the money we never notice leaving. I call these money leaks. A streaming service you signed up for once and forgot. A free trial that quietly turned into a paid plan. A monthly account fee your bank charges every month. A charge from a merchant you don’t recognize.

None of these is large on its own. That is exactly why they last. A small charge that repeats every month can go unnoticed for a long time.

Here is how to find these leaks yourself, with or without an app.

Start with your statements

Pull up the last three months of statements for every chequing account, savings account and credit card you have. Every one. Look for three things:

First, recurring charges. Anything that shows up on the same day each month, or each year, is a subscription. Ask yourself whether you still use it.

Second, bank fees. Look for monthly account fees, overdraft fees, non-sufficient funds fees, foreign transaction fees and ATM fees. These often appear as short codes, so read each line.

Third, charges you don’t recognize. Some are merchants billing under a different name. Some are not. Either way, you want to know.

Check your app store subscriptions

Many subscriptions are billed through your phone, not directly by the company. On an iPhone, open Settings, tap your name, then Subscriptions. On Android, open the Google Play Store, tap your profile icon, then Payments and subscriptions. You may find apps you stopped using long ago still renewing.

Search your email

Search your inbox for words like “receipt,” “renewal,” “trial” and “subscription.” Receipts and renewal notices often arrive by email even when the charge is buried on a statement. When you start a free trial, put the end date in your calendar the same day.

Why leaks hide across banks

If you have one bank account and one credit card, a manual review is manageable. Many Canadians and Americans have more than that. A chequing account at one bank, a credit card from another, a line of credit somewhere else.

Each bank only shows you its own piece. A subscription on your travel card won’t appear in your main banking app. A fee on an old savings account you rarely log into can run for a long time. Leaks hide in the gaps between accounts.

What to do when you find one

Finding a leak only helps if you act on it. Here are the usual options:

Cancel it. If you no longer use a subscription, cancel it through the company’s website or your app store settings. Then check your next statement to confirm the charge stopped.

Ask for a refund. If you were charged for a renewal you didn’t want, contact the company and ask. Some will refund a recent charge, especially if you haven’t used the service since.

Ask your bank about fees. If you were charged an overdraft or account fee, call and ask whether it can be reversed. If fees keep coming, compare accounts. Some online banks and credit unions offer accounts with no monthly fee.

Report what you don’t recognize. If a charge is truly unfamiliar, contact your bank or card issuer right away.

Using a tool (full disclosure)

Disclosure: I built Expense Canary, so I am biased. You can do everything above by hand. I built an app because doing it across several banks every month is tedious.

Expense Canary links your accounts and cards from different banks into one view. There is no budget to set up. It flags monthly account fees, overdraft and other bank fees, recurring charges including free trials that turned paid, and unfamiliar or larger than usual charges. You can also turn on optional notifications when new charges post.

It connects read only through Plaid in the US and Canada. It never sees or stores your bank login and can never move or transfer money. It also won’t cancel anything for you. It shows you what it found, and you decide what to do. It provides information, not financial advice.

It is available on iOS and Android, with a 7-day free trial, then $4.99 USD a month (local pricing may vary). You can learn more at https://expensecanary.com.

Whatever method you choose, the habit matters more than the tool. Set a reminder to review every account once a month. The leaks you find are money you get to keep.

Karla Castro is the founder of Expense Canary, a read-only app for iOS and Android that helps people in the US and Canada spot forgotten subscriptions, hidden bank fees, and unusual charges across their linked banks. She is based in Vancouver. https://expensecanary.com

Part-Time Work in Retirement: Money and Purpose

Image created by Alain Guillot with ChatGPT


By Alain Guillot

Special to Financial Independence Hub

Most people think of retirement as the moment they finally stop working. But what if part-time work in retirement could make your life richer, not just financially, but socially, emotionally, and intellectually?

We spend decades saving and investing so that one day we can afford to stop working. Yet when that day arrives, many retirees discover something unexpected: having enough money doesn’t necessarily mean having a fulfilling life.

I believe there’s a better way to think about retirement. Instead of asking, “When can I stop working?” perhaps we should ask, “What kind of work would I enjoy doing if I no longer needed the money?”

That simple change in perspective can transform retirement.

My personal experience: Working because I want to

I’m approaching 60, and I consider myself financially independent. I’ve spent years saving and investing, and I’ve built enough financial resources that I don’t need employment income to support my retirement lifestyle.

Nevertheless, I continue working approximately 20 hours per week as a dance teacher, earning around $2,000 per month.

That’s $24,000 per year.

I don’t need this money to pay my bills. But I enjoy earning it, and I enjoy the work that produces it.

Teaching dance keeps me physically active. It allows me to meet people, maintain friendships, participate in my community, and feel that I’m contributing something valuable.

There’s also something deeply satisfying about getting paid to do something I genuinely enjoy.

My work gives structure to my week without dominating my life. I have plenty of time for reading, writing, investing, socializing, and pursuing other interests.

For me, this is an ideal balance between work and retirement.

And the additional income? That’s a wonderful bonus.

The Financial Power of Part-Time Work in Retirement

Let’s look at the numbers, because the financial benefits can be surprisingly large.

Financial planners frequently discuss the 4% rule, a retirement guideline suggesting that a retiree might initially withdraw approximately 4% of their investment portfolio annually, adjusting subsequent withdrawals for inflation.

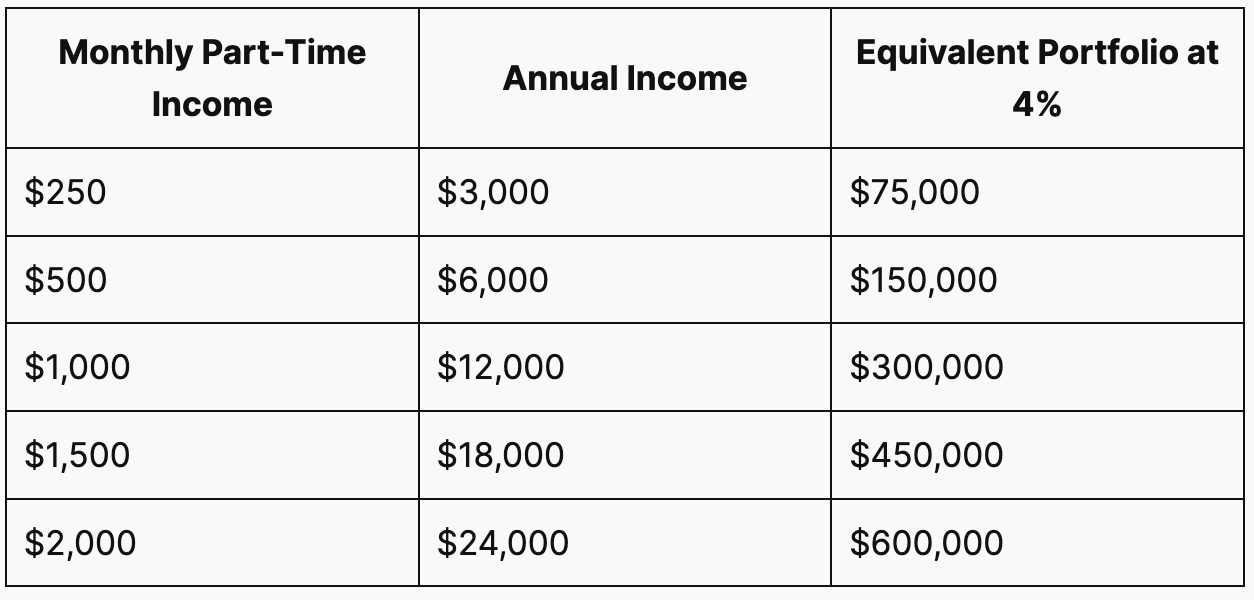
Under this framework, every $1,000 of annual retirement income is roughly equivalent to having $25,000 invested.

Consider the following examples:
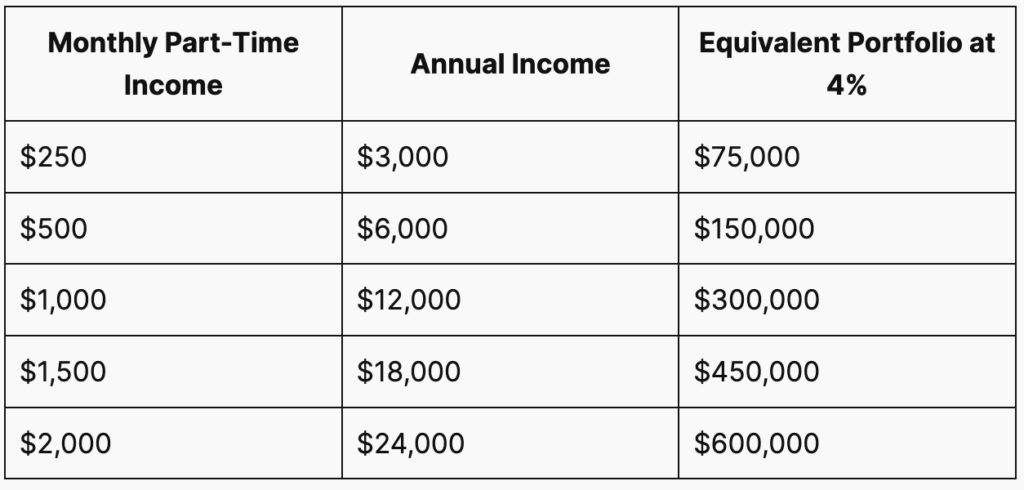
Think about that last number.

By earning $2,000 per month teaching dance, I generate the same initial annual cash flow that a $600,000 investment portfolio would provide under the 4% guideline.

Of course, this doesn’t mean my part-time job is literally worth $600,000. Investment assets can appreciate, provide income without requiring work, and potentially be passed to heirs. Employment income depends on my continuing to work.

Still, the comparison illustrates how powerful even modest earnings can be.

You don’t need to Earn $2,000 per Month

Not everyone wants to work 20 hours per week.

Suppose you enjoy gardening and earn $500 per month helping neighbors maintain their gardens.

That’s $6,000 per year.

Using the same 4% comparison, this income is equivalent to the initial annual withdrawal from a $150,000 portfolio.

For someone concerned about having enough retirement savings, that additional income can make a meaningful difference.

The key isn’t to earn as much as possible. It’s to find an amount of work that improves your life rather than complicates it.

Four reasons to consider Part-Time Work in Retirement

1. Your Retirement Savings can Last Longer

One of the biggest financial concerns retirees face is outliving their savings.

Imagine two retirees, each with a $500,000 investment portfolio.

The first needs to withdraw $30,000 annually to cover living expenses.

The second has the same expenses but earns $12,000 annually from enjoyable part-time work. That person only needs to withdraw $18,000 from investments.

The difference is substantial.

By withdrawing less money, the second retiree gives their portfolio more opportunity to grow and recover from market downturns.

Over 10 or 20 years, this can meaningfully improve financial security.

The exact outcome depends on investment returns, inflation, taxes, and how long the person continues working.

2. You can Afford more Experiences

Not everyone wants to leave a large inheritance or accumulate the biggest possible investment portfolio.

Some people simply want to enjoy life.

An extra $500 or $1,000 per month could finance travel, restaurant meals, concerts, hobbies, or visits with family.

If your basic expenses are already covered by pensions and investments, part-time income can become discretionary spending money.

You might even create a simple rule: all earnings from your retirement gig go toward experiences rather than necessities.

Imagine paying for an annual vacation entirely with money earned from a hobby you enjoy.

That’s a pretty attractive arrangement.

3. Work provides Purpose and Social Connections

We often underestimate how much our professional lives contribute to our identities.

Work provides routines, challenges, relationships, and a sense of accomplishment.

When people retire, some lose these connections almost overnight.

Suddenly, there’s no workplace to visit, no colleagues to talk to, and no clear reason to get out of the house at a particular time.

For some retirees, that freedom is wonderful. For others, it can eventually lead to boredom, isolation, or a loss of purpose.

Part-time work offers a middle ground.

Retirement also gives us the freedom to explore new social activities and become more involved in our communities. For example, attending live comedy shows is a great way to meet people, enjoy an evening out, and support local performers. Whether through dancing, comedy, or other community activities, staying socially engaged can make retirement more fulfilling.

In my case, teaching dance gives me regular opportunities to interact with people. I meet students, share experiences, laugh, and participate in an active social environment.

I don’t think of those hours as an obligation. They’re an enjoyable part of my life.

The money matters, but the relationships matter just as much.

4. Work can keep your Mind and Body Active

Retirement shouldn’t mean withdrawing from life.

Depending on the activity, part-time work can provide physical movement, mental stimulation, and opportunities to learn new skills.

A retired accountant helping small businesses might enjoy solving financial problems.

A former teacher tutoring students might find satisfaction in watching young people improve.

A retiree working at a garden center might enjoy spending time around plants and other gardening enthusiasts.

As a dance teacher, I have the added benefit of staying physically active while working.

Of course, paid employment isn’t the only way to obtain these benefits. Volunteering, hobbies, community organizations, and family activities can be equally meaningful.

But when enjoyable work provides those benefits and generates income, it becomes especially attractive.

The Best Retirement Job is not necessarily the highest-paying One

During our working years, we often make career decisions based on salary, promotions, and financial obligations.

Retirement gives us the opportunity to change those priorities.

You might accept a lower-paying job because you enjoy the people, the activity, or the flexibility.

A retired executive who once managed hundreds of employees might be perfectly happy working two mornings per week in a bookstore.

Someone who spent decades sitting behind a desk might enjoy walking dogs.

A former engineer might discover that teaching mathematics to teenagers is more satisfying than managing large projects.

The goal is not to maximize income. The goal is to maximize life satisfaction.

That’s an important distinction.

If your retirement job creates stress, damages your health, or prevents you from enjoying your freedom, it may defeat the purpose.

(Affiliate link added by Editor: And if a health setback ever interrupts an income you’ve come to rely on, that’s the gap disability insurance exists to fill.)

Seven Part-time Jobs worth considering in Retirement

Here are some possibilities that can combine modest income with personal satisfaction:

  1. Teaching or tutoring: Share your expertise in languages, mathematics, music, dance, or another subject. My friend Cheryl teaches English as a second language and she loves it.
  2. Pet sitting or dog walking: Spend time with animals while earning additional income and staying active.
  3. Consulting: Offer your professional knowledge to businesses without returning to full-time employment.
  4. Tour guiding: Share your enthusiasm for local history, architecture, or culture with visitors.
  5. Freelance writing or editing: Work from home on a flexible schedule, especially if you enjoy communication.
  6. Gardening or home services: Help neighbors with landscaping, small repairs, or seasonal projects.
  7. Working in a bookstore, museum, or community center: Combine a pleasant environment with regular social interaction.

The possibilities are nearly endless.

You could also turn an existing hobby into a small business, although not every hobby needs to become a source of income.

The most important question is whether you would still enjoy the activity after it becomes a paid responsibility.

How to choose the Right Retirement Gig

Before accepting a part-time job or starting a small business, consider a few questions.

Would I enjoy doing this even if I didn’t need the Money?

This is my favorite test.

If the answer is yes, you’re probably moving in the right direction.

How much Time am I willing to Commit?

For me, 20 hours per week feels comfortable.

For someone else, five hours might be ideal.

There’s no universal answer. Your schedule should leave enough time for everything else you want to experience.

Will the Work Improve my Social Life?

Some jobs provide regular opportunities to interact with others.

Others, such as freelance writing, might involve working alone.

Neither is inherently better. Choose according to your personality and needs.

Will it Create Financial or Administrative Complications?

Additional income can affect taxes, income-tested government benefits, and eligibility for certain programs.

In Canada, for example, employment or self-employment income may affect benefits such as the Guaranteed Income Supplement. Old Age Security recovery tax rules may also matter at higher income levels.

Self-employed retirees should also account for business expenses, applicable pension contributions, and tax obligations.

The financial benefit should be evaluated using after-tax income, not just gross earnings.

Part-time Work can also Reduce Retirement Anxiety

One of the psychological challenges of Retirement is transitioning from accumulating money to spending it.

For decades, we develop the habit of saving.

Then suddenly we’re supposed to start withdrawing from our investments.

Even when the mathematics suggests that we have enough, spending down our savings can feel uncomfortable.

Part-time income can help ease that transition.

Knowing that money continues arriving every month may make it easier to enjoy retirement without constantly worrying about investment balances.

I find that my own earnings provide an additional sense of security, even though my financial plan doesn’t depend on them.

If markets decline, I have some income that doesn’t require selling investments.

That flexibility is valuable.

It doesn’t eliminate investment risk or guarantee financial security, but it creates another layer of protection.

Don’t Postpone Retirement just to keep Earning Money

There’s an important warning here.

I am not suggesting that everyone should continue working indefinitely.

Some people have spent decades doing physically demanding jobs. Others have health problems, caregiving responsibilities, or simply no desire to work anymore.

For them, retirement without employment may be the best possible choice.

And if you already have enough money, there’s no reason to sacrifice your freedom for additional income you don’t need.

The objective is not to turn retirement into another career.

It’s to recognize that work can be one of several enjoyable activities in a fulfilling retirement.

You should feel free to stop whenever the activity no longer brings you satisfaction. Continue Reading…


Early retirement healthcare in Canada: a province-by-province comparison guide

If you’re like me, you probably haven’t really thought about healthcare in early retirement until you get closer to this major milestone, because you just assume that, as a Canadian, universal healthcare is there to cover everything.

Despite having universal healthcare, I believe it’s still important to keep in mind all the different provincial rules and benefits. My previous article primarily focused on BC, so I want to compare early retirement healthcare options in each province. Furthermore, I want to explore options like moving provinces to lower your cost of living, and what if you decided to live abroad most of the year… What happens to your healthcare coverage?

Let’s find out.

Health premium: most provinces phased it out

Many years ago, it was true that you paid for provincial health coverage. But fast-forward to today, that’s no longer true in most provinces.

Here in B.C., the government eliminated the MSP (medical service plan) premium back on January 1, 2020. The BC provincial healthcare is now funded through tax revenues. Similarly, Alberta got rid of the health premium in 2009. If you look across Canada, most provinces have removed the provincial healthcare premiums and provincial healthcare is now funded through general tax revenues.

But the two big Canadian provinces still charge premiums.

Ontario charges an Ontario Health Premium, collected through your income tax return and it is based on your income. If your taxable income is under $20,000, you do not have to pay anything. The premium scales up $0 to a maximum of $900 per year for high-income earners.

Quebec doesn’t charge a health premium, but it does have a mandatory prescription drug arrangement. The fee is collected at tax time if you don’t have private drug coverage.

So yes, for the most part, you don’t have to pay the monthly provincial health premiums anymore. Instead, you are paying via provincial income tax or other provincial taxes.

The gaps that universal healthcare doesn’t cover

The universal healthcare we have in Canada covers many things, especially the big expenses, but it doesn’t cover everything. Our universal healthcare falls short on the following:

  • Prescription drugs
  • Dental care
  • Vison
  • Paramedical services like physio, massage, chiropractor, counselling, etc
  • Out-of-country medical care
For these expenses, early retirees typically rely on either private extended healthcare plans,  self-insurance for these expenses, or some level of government assistance.

Government-assisted plans for dental & prescription 

Prescription drugs can be quite costly, but two provinces have programs to help with that.

Here in B.C., the Fair PharmaCare program covers prescription drugs with a deductible based on your family’s net income from two years ago. You have to pay a deductible first, then Fair PharmaCare covers 70% (or 75% if someone in your family was born before 1940). Once you hit the family maximum, Fair PharmaCare pays 100% of the eligible costs for the rest of the year. You can find the family deductible amount here. For early retirees in BC who need prescription drugs, the Fair PharmaCare program can be a good option.

In Quebec, prescription drug insurance is mandatory. So if you have access to a private plan, you must take it. If you don’t have a private plan, you are automatically enrolled and covered by the public plan. This public plan has a premium that’s income-based via your tax return. Interestingly, Quebec is the only Canadian province that legally requires you to have prescription drug insurance.

Outside of B.C. and Quebec, prescription drug coverage for early retirees is limited. The provincial prescription drug coverage is typically aimed at seniors and people with specific conditions. Below is the summary for the different provinces:

  • B.C.: Fair PharmaCare. Your deductible and family maximum are calculated from your net income. Lower-income households (including many seniors) have low or zero deductibles.
  • Alberta: Albertans 65+ have premium-free coverage for prescription drugs on the Alberta Drug Benefit list, administered by Alberta Blue Cross. The copayment is 30% to a maximum of $35. Outpatient cancer therapy and palliative-care patients have separate, copay-free or specialized coverage.
  • Saskatchewan: eligible seniors 65 and older pay $25 per prescription under the Seniors’ Drug Plan. To qualify, your net income must be $79,487 or less on your 2024  income tax return to be eligible for 2026. There is also coverage for palliative-care drugs and long term disability and illnesses.
  • Manitoba: Manitoba Pharmacare provides drug assistance to eligible Manitobans via an income-based deductible. Once your spending hits the deductible, the program covers eligible drugs. The Manitoba Enhanced Pharmacare Program covers most medications for residents with certain conditions who aren’t covered through other public programs.
  • Ontario: 65+ Ontario residents automatically qualify for the Ontario Drug Benefit program. Lower-income seniors can apply for the Seniors Co-Payment program, under which recipients pay no annual deductible and co-payment of $2 or less. The Trillium Drug Program supports lower and modest-income people by covering about 5,000 drugs plus about 1,000 more drugs through the Exceptional Access Program. You pay up to $2 per prescription. The deductible is capped at roughly 4% of household income. (Note, my additional research showed it may actually be more complicated. There’s a $100 annual deductible (Aug-Aug) after which most drugs on Trillium are covered fully, except for the $4.11 dispensing fee).
  • Quebec: universal/mandatory. Seniors automatically register for the public plan at 65, and many low-income seniors pay a reduced or zero premium.
  • Nova Scotia: the seniors’ Pharmacare program is open to residents 65+ with a valid health card who don’t have other drug coverage. Members pay an income-based annual premium plus an annual copayment, both with maximums, with the province covering the rest. Separate coverage exists for cancer patients and palliative care.
  • New Brunswick: The Prescription Drug Program covers low-income families and seniors.
  • Prince Edward Island: all eligible residents are automatically enrolled in the seniors’ drug plan the month they turn 65. The Family Health Benefit Drug Program and Financial Assistance Drug Program are available for low-income residents and families.
  • Newfoundland & Labrador: the 65Plus Plan covers residents 65 and older who receive Old Age Security and the Guaranteed Income Supplement. The Foundation Plan and the Access Plan cover low-income individuals and families.

So if you’re an early retiree and not yet 65 or older, you probably need to self-cover prescription drugs.

Dental care can be another big expense for families. Fortunately, as of 2026, the Canadian Dental Care Plan (CDCP) is available to eligible Canadian residents regardless of age, as long as your adjusted family net income is under $90,000 and you don’t have access to private dental insurance. For households under $70,000 net income, you will get full coverage with no co-pay. Between $70k and $90k, you get partial coverage. Therefore, for an early retiree without a group plan and a modest reported income, the CDCP may be able to cover dental care.

Out-of-country coverage: very important to consider

Many retirees will want to travel for an extended period, sometimes outside Canada. This begs the question: What should you do for out-of-country health coverage?

The provincial plan does cover emergency medical care outside Canada, but only at the rates it would pay in your home province. This may sound reasonable, but the reality is that many healthcare costs are way more expensive than in Canada (i.e. the U.S.) I have heard someone not wanting to go to the emergency room in the U.S. and driving back to Canada to get treatment, because of the outrageous US cost (and they didn’t have travel health insurance).

This is why, if you are travelling outside of Canada, it is critical to get travel insurance, regardless of your health conditions. It’s better to be safe than sorry.

Fortunately, many premium credit cards have travel insurance benefits. For example, TD Infinite Visa has a $2 million travel medical insurance for the first 21 days for holders 65 and under. Unfortunately, if you’re 65 or older, these credit-card travel insurance benefits drop significantly. In TD Infinite Visa’s case, the coverage drops to four days. Based on my research, if you are 65+, the best credit cards for travel insurance are the National Bank World Elite Mastercard and Desjardin Odyssey Visa Infinite Privilege (15 days up for seniors aged 65-75). The Scotiabank Platinum American Express and Scotiabank Gold American Express cards also offer 10 days of travel insurance for seniors 65 and older.

Since many early retirees go for extended trips longer than 21 days, it is better not to completely rely on credit-card coverage and get travel insurance. The cost of the travel medical insurance will depend on your age, duration, coverage tier, pre-existing conditions and deductible. For the most part, these travel insurances are quite cost-effective (anywhere from $70 to $500 based on my research).

Keep in mind the three-month gap 

If you decide to move to another province to reduce your cost of living, you need to keep in mind the three-month requirement.

Provinces typically have a waiting period of up to three months before the “new” provincial health coverage kicks in. During that window, you will need to rely on your “old” province to continue to cover you. Basically, you need to make sure you register promptly once you settle in the new province so you don’t end up with no health coverage for a brief period.

Similarly, if you go out of the country for an extended time (i.e. more than six months), you are no longer eligible for provincial health coverage, so you will need to cover yourself via health insurance.

A province-by-province health coverage snapshot for early retirees

Here’s a simplified comparison of health coverage for the different provinces. Continue Reading…

What happens to your FIRE Plan when your Net Worth becomes more than anticipated?

Image from Pexels: Gabby K/Monstera Production

By Tessa Dodson

Special to Financial Independence Hub

Exceeding your Financial Independence, Retire Early (FIRE) plan was the goal, but now that your net worth has surpassed what you needed to retire early, a new challenge emerges.

Most FIRE advice centers on frugality and disciplined accumulation, but crossing that finish line introduces advanced questions about wealth preservation, tax optimization and legacy planning.

You need new strategies to protect what you’ve built for the decades ahead.


Redefining Financial Independence after hitting your Target

The frugal lifestyle model that fueled your early retirement no longer serves your new reality. You need a more sophisticated approach to long-term financial management that accounts for decades of early retirement, shifting tax landscapes across North America and managing surplus capital. Your priority now shifts from building wealth to protecting it.

  • From accumulation to preservation: Your focus moves to shielding assets against inflation, market volatility and tax erosion over a retirement spanning 40 or 50 years.
  • From simplicity to complexity: Basic index funds and tax-deferred accounts got you here. Surplus capital demands trust structures, tax-loss harvesting and strategic asset location.

Philanthropy and Purpose beyond the Portfolio

Exceeding your goals introduces an opportunity many early retirees don’t anticipate. Finding your purpose becomes essential. Without the routine of work, directing excess capital toward meaningful causes provides both psychological satisfaction and strategic tax advantages. High-net-worth individuals can extend their impact by supporting scholarships, community programs or student organizations that align with their values.

Strategic charitable giving opens several pathways:

  • Build a legacy beyond wealth: Funding scholarships, endowments or community programs ensures your influence extends beyond your lifetime while aligning values with change.
  • Optimize tax efficiency: Donor-advised funds, charitable remainder trusts and direct gifting strategies reduce your taxable estate while supporting causes you care about.
  • Engage with purpose: Early retirement can feel directionless without a professional identity. Active philanthropy provides a framework, community connection and measurable results.

Estate Planning and Wealth Transfer Strategies

When you have surplus capital, you’re now planning for the next generation. This introduces challenges most FIRE adherents never anticipated. Estate planning tools, specifically trusts, operate as shields against probate delays and unnecessary taxation for those you leave behind.

When utilizing a grantor trust, the Internal Revenue Service considers the gift incomplete until death. This means assets receive a stepped-up basis at the time of your death. Your beneficiaries are only liable for capital gains taxes on appreciation after the date of death, rather than the original purchase price. This can save the next generation hundreds of thousands.

Key planning considerations include:

  • Trust structures for tax efficiency: Revocable living trusts, irrevocable life insurance trusts and charitable remainder trusts each serve different purposes depending on your financial situation, family structure and legacy goals.
  • Protecting beneficiaries from probate: Trusts bypass the costly, time-consuming probate process. Your beneficiaries receive their inheritance without court delays or public disclosure.
  • Cross-border complications: For Canadians and Americans with assets in both countries, planning becomes exponentially more complex due to differing tax treaties, thresholds and residency rules.

Navigating Advanced Tax Traps in Early Retirement

Outliving your original timeline by decades exposes you to tax vulnerabilities most conventional retirees never face. The blind spot emerges when you fail to sequence withdrawals from tax-advantaged versus taxable sources. This triggers penalties and unnecessary burdens. Understanding the withdrawal sequence from your accounts can mean the difference between preserving your portfolio and watching it erode.

Critical tax considerations include:

  • Roth conversion ladders: Converting traditional IRA funds to Roth accounts during low-income years minimizes lifetime liability. Timing and amounts require precision to avoid landing in higher brackets.
  • Capital gains management: Long-term capital gains rates favor patient investors. Realizing too many gains in a single year triggers additional levies on Social Security benefits or Medicare premiums.
  • Required minimum distributions: Even if you don’t need the income, Required Minimum Distributions begin at age 73 in the U.S. and can elevate your bracket if you haven’t strategically drawn down earlier.

Secure your Wealth for the Decades ahead

Managing an unexpectedly large net worth requires moving beyond the self-directed strategies that defined your journey. You’re no longer accumulating. You’re protecting, transferring and optimizing across generations. That demands expertise in tax law, estate planning and multi-generational transfer strategies.

Your FIRE plan got you to Financial Independence. Safeguarding what you’ve built requires an expert team. A tax professional, estate attorney and financial advisor who specializes in high-net-worth early retirees can update your plan for the decades ahead, directing your wealth toward your legacy instead of taxation.

Tessa Dodson is the senior writer of Classrooms.com and a former career coach with over five years of experience developing educational content and guiding diverse audiences, from new hires to business professionals, through career exploration, beginnings, transitions and retirement. She is passionate about financial literacy, budgeting and writing practical and actionable resources that lead to economic success.

From Building Wealth to Spending it: The Canadian Financial Summit returns October 21–24

By Kyle Prevost, Million Dollar Journey

Special to the Financial Independence Hub

One of the more interesting things I’ve learned from speaking with Canadians about retirement is that saving enough money is only half the battle. After spending 30 or 40 years accumulating investments, paying down mortgages, and generally trying to make responsible financial decisions, many people discover that actually spending their savings is more complicated than they expected.

After all, the financial rules that served you well during your working years don’t necessarily apply once the paycheques stop. Suddenly you’re juggling RRIF withdrawals, CPP and OAS decisions, investment income, tax brackets, and the possibility that your retirement could last another 30 years. Throw in the psychological adjustment of watching your investment accounts decline rather than grow, and it’s easy to see why retirement planning involves a lot more than reaching a magic number.

These are precisely the kinds of conversations I wanted to explore at this year’s Canadian Financial Summit, taking place online from October 21–24, 2026.

We’ve brought together more than 40 Canadian financial experts, with a particularly strong emphasis this year on retirement income, investment portfolios, tax efficiency, and making the transition from financial accumulation to financial independence.

The entire event is FREE to attend, with each presentation available to watch for 48 hours after its release.

Click here to reserve your free Canadian Financial Summit ticket.

What happens after you reach Financial Independence?

I was obviously pleased that Financial Independence Hub founder Jonathan Chevreau agreed to join us again this year. Jon has spent decades writing about financial independence, semi-retirement, pensions, investing, and the challenges of turning accumulated wealth into retirement income.

This year, however, we’re approaching the subject from a slightly different angle. Having made the transition from writing about retirement to experiencing it himself, Jon is sharing his perspective on what he got right, what surprised him, and what he might approach differently with the benefit of hindsight.

His session, From Retirement Columnist to Retiree: What I Got Right, Wrong, and Didn’t Expect, goes beyond the financial calculations to examine the actual experience of leaving employment behind. We’ll discuss the move from earning a paycheque to drawing on investments, the temptation to postpone spending, and why financial independence doesn’t automatically eliminate financial anxiety.

I suspect many readers here will find his observations especially interesting. After all, there aren’t many people who have spent as much time as Jon studying the theory of financial independence before testing it in their own lives.

Retirement Income & Taxes

Another major focus this year is what financial planners call decumulation: the process of converting your investments and other assets into money you can actually live on.

The challenge is that Canadians have several different sources of retirement income, each with its own tax treatment, withdrawal rules, and planning opportunities. Getting the sequence right can make a substantial difference over the course of retirement.

Here are some of the presentations I’m particularly looking forward to:

  • Robb Engen: What retirement spending and taxes actually look like, including the confusion surrounding RRSP withholding taxes and how retirees establish a sustainable withdrawal routine.
  • Nancy Grouni and Ed Rempel: Reducing lifetime retirement taxes, coordinating RRSP/RRIF withdrawals with CPP and OAS, and avoiding expensive tax surprises.
  • Dale Roberts: Building a retirement cash flow plan that connects your investments, government pensions, tax brackets, and spending needs.
  • James Gauthier: Adjusting your investment portfolio for retirement, with particular attention to sequence-of-returns risk and balancing growth with reliable income.
  • Isabelle Bernier and Mike Heroux: Why Canadians who have saved diligently for decades sometimes struggle to spend their money, and how to balance financial security with actually enjoying retirement.
  • Mark Seed and Kornel Szrejber: Firsthand perspectives on achieving financial independence, leaving traditional employment, and discovering what life looks like after reaching your savings goals.

We’ve also invited Jason Heath to explain how to evaluate the assumptions underlying professional financial plans, while Hannah McVean will demonstrate a step-by-step Canadian financial planning case study. Both sessions should be useful for anyone who wants to better understand the calculations behind their retirement projections.

Retirement Planning is about more than Investment Returns

One theme that runs through many of this year’s conversations is that the best retirement strategy isn’t necessarily the one that produces the highest possible net worth. Continue Reading…