All posts by Financial Independence Hub

Is Canada’s Housing market starting to cool?

By Gordon Powers, Zoocasa.com

Special to the Financial Independence Hub

Canadians’ confidence in the housing market hit an all-time high less than a month ago, but the mood across the country seems to have shifted significantly in recent weeks.

Home sales across Canada fell by 6.2 per cent in May 2017, largely due to a sharp drop in Toronto, according to the most recent figures from the Canadian Real Estate Association. The month-over-month percentage decline was the largest since August 2012.

In nearly two-thirds of all local markets across Canada, sales were off. The decline was led by a 6.7 per cent drop in the GTA, where potential home buyers seem to be moving to the sidelines, delaying their purchase decisions in the hope of a drop in runaway home prices.

Prices beginning to shift slightly

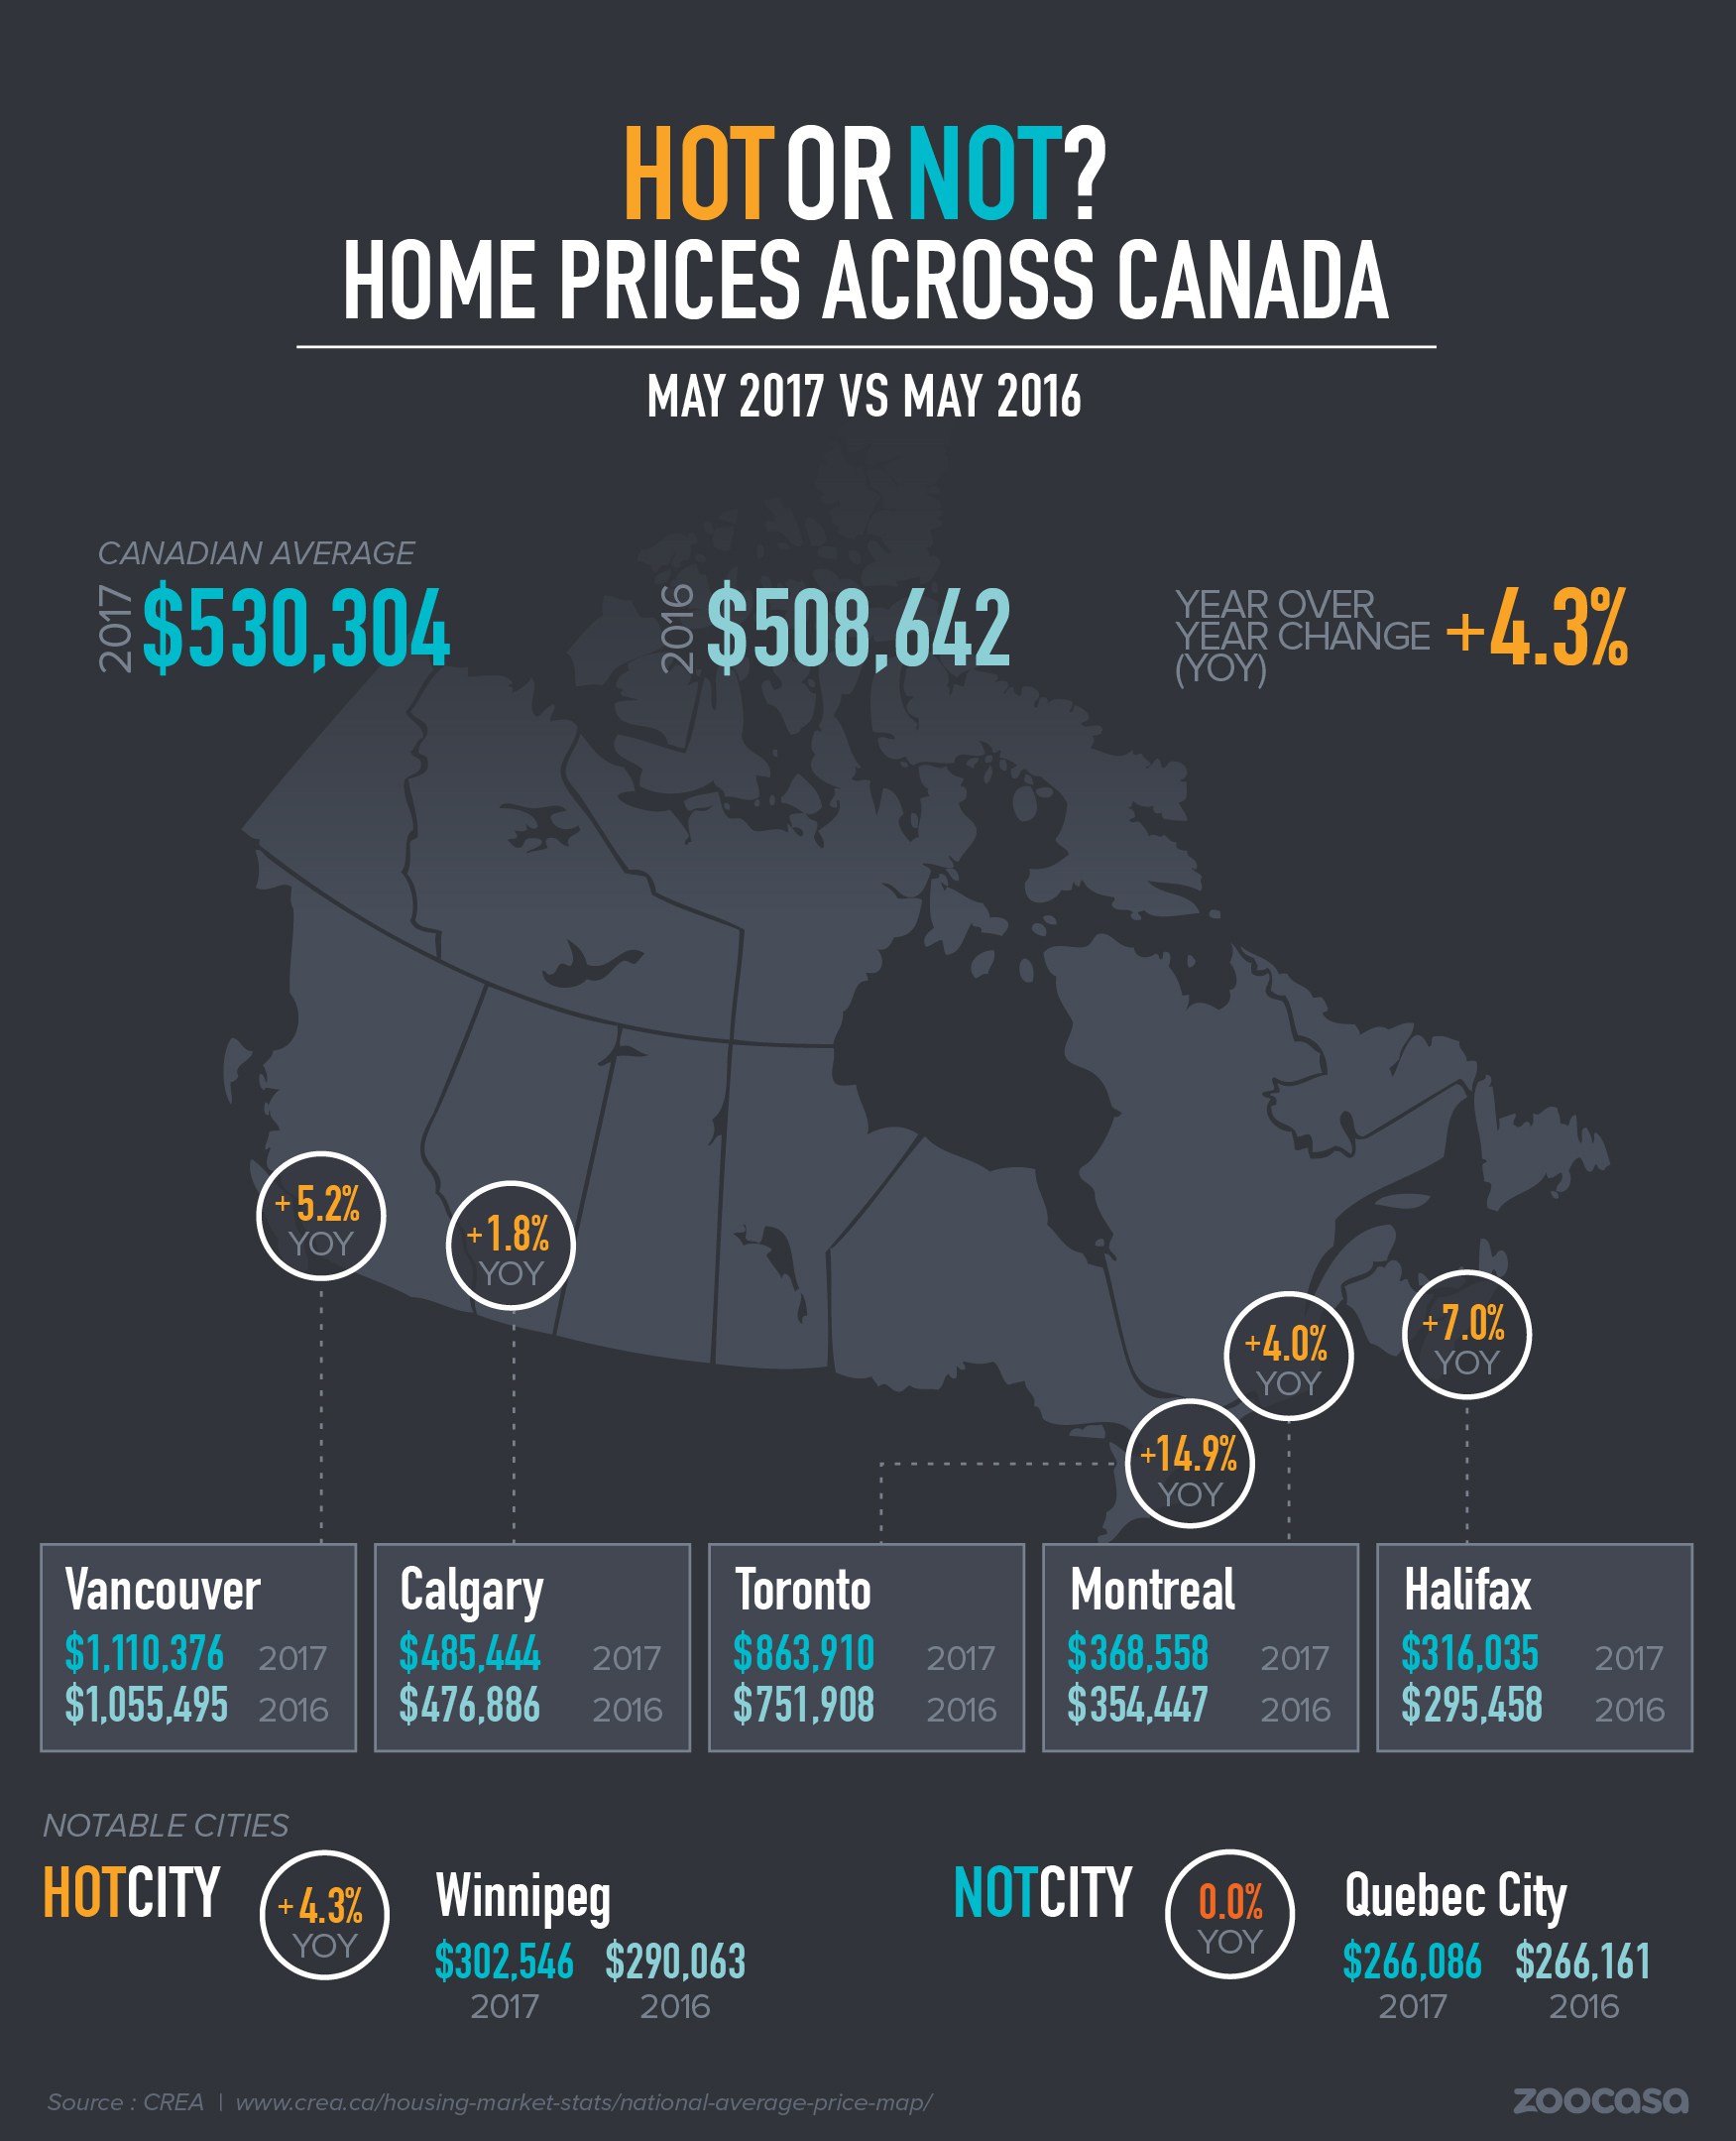
The national average price for homes sold in May was $530,304, up 4.3 per cent from where it stood a year ago. While that number has been pulled sharply upward by transactions in the GTA and Vancouver – excluding these two markets trims more than $130,000 from the national average price of $398,546 – there’s no question that prices have dropped off in certain areas of the country

Prices in the GTA declined in May for the first time in years, according to recent figures from the Toronto Real Estate Board.

While home prices in and about Toronto rose 14.9 per cent year over year, they were actually 6.2 per cent cheaper between April and May, the first full month-long period following the implementation of the Ontario Fair Housing Plan rules.

The TREB May resale numbers reveal GTA sales dropped 20.3 per cent year over year with detached home sales leading the slide at 26.3 per cent, Toronto condo sales backing off 6.4 per cent, and Toronto townhouse sales declining at 18.1 per cent. Continue Reading…
Retirement STILL Rocks

Heather Compton & Dennis Blas, coauthors of Retirement Still Rocks

By Heather Compton and Dennis Blas

Special to the Financial Independence Hub

Since retiring in 2004, we’ve learned a thing or two.  Foremost, a rockin’ retirement requires more than a bucket list: it’s not a given, it’s a statement of intention. A satisfying retirement requires finding new ways to satisfy our needs and utilize the skills and talents that give us the greatest satisfaction. Like a working career, a retirement career unfolds, develops, progresses and changes as life circumstances unfold. This doesn’t mean some front-end planning won’t be useful. Our cornerstones for a rockin’ retirement include Lifestyle, Relationship and Finances.

Go-Go to Slow-Go to (sigh) … No-Go

Many of us will have a third act lasting 30 plus years and few will plan for the full-stop retirement of a previous generation.  All play and no work also makes Jack a very dull boy! We may think of retirement as one long time frame, but those who study aging divide it into three distinct phases: the go-go, slow-go and no-go years. Certain Victory Lap careers, travel destinations and budding interests must be pursued in the go-go years; others might wait until the slow-go. Either way, you’ll want to mind-bank lots of great life experiences to relive in the no-go years! Continue Reading…

5 common mistakes when working with an advisor

Chris Ambridge

By Chris Ambridge, Transcend

Special to the Financial Independence Hub

Canadians are often faced with complex and nondescript investment products that can be overwhelming.  As such, most people need professional advice. With personal recommendations as one of the most common forms of referrals, selecting the right advisor should also be based on qualifications, fees that won’t gouge, and the advisors autonomy to act in the best interest of the customer.

However, many people are now spending a significant amount of time surfing the web and seeking advice online, where it can be difficult to distinguish expert advice from the inept.

In Canada, 96% of registered advisors are “dealing representatives,” which means they are salespersons not legally required to look after your best interests. On the other hand, just over 4,000 advisors are registered in categories where they must act as true fiduciaries and are legally required to deliver clients advice that must be in their best interest. While there are many financial advisors who look after their clients in the same way as true fiduciaries and deliver exceptional support and guidance, there are a whopping 118,000-plus advisors who do not have to adhere to such standards.

As an investor in search of an advisor, your goal should be to find the right person to help you reach your future financial goals. While you can correct a poor choice down the road, you would have wasted valuable time and may have actually suffered financial setbacks. It is therefore paramount you avoid the following mistakes:

Mistake #1

Don’t fall for the opening pitch. No matter how enticing the discussion and no matter how obvious the initial set of benefits are, chances are you are only seeing one side of the equation. No one wants to reveal their warts, especial right off the bat. So take your time to establish a rapport with the advisor. Trust comes with knowledge and clarity so make your first appointment about gathering information and creating a connection.

Mistake #2

If investments and products are the first subject of conversation before attempting to build a profile of you and your family, take a pass. Remember you are looking for someone that can give you personalized advice and not a canned spiel or off-the-shelf solution. If the advisor starts talking about investments before understanding your fears then you should think twice.

Mistake #3

Continue Reading…

Top 10 tips to Save on Car Insurance

By Anne Marie Thomas

Special to the Financial Independence Hub

Car insurance is one of those costs of owning a vehicle that everyone wants to save money on, and with these tips from InsuranceHotline.com you’ll be able to ensure that year after year, your premiums are the lowest they can be.

1.) Compare rates annually at renewal

For the sake of convenience, you may be tempted to simply renew with your current auto insurer when your policy is about to expire, but this could end up costing you big time. Rates often change and the insurer who offered you the best rate two years ago, or even last year, may no longer offer you the best deal today.

2.) Don’t wait for your renewal to shop around

A lot can happen over the course of a year, and as a rule of thumb, you should shop around anytime anything that could affect your insurance rate happens. For example, you should spot check your premiums when you move, get a ticket (or are involved in an at-fault collision), get married, change jobs or retire.

Tip: If you find a better rate when you shop around mid-policy, make sure the savings are more than the fee you’ll be charged for cancelling your policy. If the fees are higher than the savings, then it might be better to wait until your policy is set to expire before switching companies.

3.) Bundle it

We all know bundling phone and television services nets a lower bill, and the same is true for insurance. If you get your property insurance (home, condo, or tenant insurance) from the same company as your auto insurance then you’ll likely qualify for a discount that could save you from five to 15 per cent off of one, or even both of your policies.

4.) Review your deductibles Continue Reading…

The what, when and why on the new Debit Card Chips

By Jessica Kane

Special to the Financial Independence Hub

For years, we got used to swipe, type and go. Then, all of a sudden, we were forced to insert our cards and wait, like we’ve been thrown back to the Stone Age. Well, you will be pleased to know that it was not a step backward. This is real progress for the protection of the cardholder.

What makes the chip so different?

The difference between the chip and the magnetic strip is bigger than just your experience when you check out. When you swipe your card at the terminal, your personal information is vulnerable. We have seen this numerous times in major department stores over the years. All it takes is one good hacker, and all of the information on every card ever swiped within that database is up for grabs.

Yes, that means identity theft.

With the new chip, all of that information is encrypted before it is processed. What does that mean? In a nut shell, your information is transmitted as a one-time-use code. No more hanging your personal info out there for someone to grab a hold of. This doesn’t mean the codes are unbreakable, just that it takes a whole lot more to crack them.

In addition to that, the chip can’t be counterfeited. That magnetic strip on the back of your card, which you’ve been swiping forever, can easily be duplicated. If someone gets their hands on your card, that one strip could quickly turn into hundreds. If you have a chip card stolen, the culprit must have your personal identification number (PIN) in order to use it. And because it can’t be copied, there will only be one bad guy to track down.

When did the chip come into play?

The United States just adopted the more secure way to pay in 2015. But, believe it or not, the chip card has been around since 1994. Fraud was a huge problem in Europe, so they decided to change the way they make transactions by using this seemingly new technology. Since they made the change, Europeans have saved millions that would have been lost to fraud and counterfeiting. Slowly but surely, the rest of the world is following suit.

Why do I have to use them?

Continue Reading…