All posts by Financial Independence Hub

Graduating from College? Your financial future starts now

By Jackie Waters

Special to the Financial Independence Hub

Graduating from college is a huge milestone. You’re now ready to start your career, and you’re excited about getting a house or apartment, a car, a new work wardrobe, and more. But all of those things cost money. And don’t forget repaying student loan debt, insurance premiums, utility bills, food costs, and a long list of other expenses. Since you’re facing these new expenses, it’s essential to create a solid financial plan.

Make a budget and manage your debt

Experts recommend starting your monthly budget by thinking of the “50-30-20” rule. After receiving your first paycheck, you’ll know your net income, which is how much you receive after paying taxes and insurance premiums. From your net income, put 50 per cent towards needs such as rent, utilities, and food; another 30 per cent towards non-necessities or “wants;” and the final 20 per cent towards debt repayment and savings. However, if your student loan debt is substantial, flip the percentages so that 30 per cent goes towards debt repayment and savings, and 20 per cent goes towards wants.

Student loans are usually broken up into several loans with varying interest rates. The best way to tack them is to pay off the loans with the highest interest rates first. Pay the minimum towards the balances with the lowest interest rates, and make larger-than-the-minimum payments on the loans with the highest interest rates. “The biggest mistake you can make is paying the minimum into each loan and waiting until you make more money when you’re older to deal with them,” warns Time.

Look to the future

Life is full of unexpected surprises, so an emergency fund is crucial. If your car needed a major repair, if your laptop needed replacing, if you lost your job – what would you do? If you have an emergency fund, you’ll be able to pull from there instead of from your monthly budget. People often face going into debt because they have no way to cover unexpected expenses. To prevent this from happening to you, plan for the unexpected by putting a small amount of each paycheck into a savings account.
Continue Reading…

Choosing between Income Protection Insurance and a Savings Account

By Cathy Habas

Special to the Financial Independence Hub

If you became seriously sick or injured today, would you be able to afford all your bills? Think about not only your medical expenses, but also your monthly payments: utilities, mortgage, car, insurance, loan repayment, etc.

Health insurance might pay for your hospital bills, but if you’re unable to work for an extended period of time, would you feel the pain of lost income?

Most of us certainly would. Fortunately, income protection insurance is designed to help us carry on without too much disruption.

What Is Income Protection Insurance?

In exchange for a monthly premium, you get peace of mind through income protection insurance. If you were unable to work due to an injury or illness, income protection insurance essentially replaces your income.

Specific details will depend on each policy, but in general you can expect to claim your income protection insurance more than once. That means you can benefit from the payouts any time you get sick or injured, and not just the first time you experience a major setback.

Continue Reading…

It’s still possible for Singles to buy their own home: Here’s how

By Marc Kulak

Special to the Financial Independence Hub

Buying a home can be daunting, especially for people who want to buy on their own. And that number is growing. In fact, according to a survey we at TD Canada Trust recently conducted, single homeowners represent a quarter of Canadians buying or intending to buy a home.

A large part of this trend is driven by unexpected life circumstances: Canadian homebuyers who are divorced (69%) or widowed (35%) more likely to purchase solo, along with a growing number of single Canadians who say they’ll go it alone (67%).

From personal experience, I know that being creative –- and realistic –- on ways to afford to own a home is going to get you in one faster. Here are a few ideas to get you started:

Buying solo doesn’t mean living solo

Just over one-quarter (27%) of single Canadians who have or intend to purchase a home alone would consider having a tenant to make solo home ownership more affordable, while just under one-quarter (23%) said they would consider a roommate. Having rental income can help pay down the mortgage principal more quickly. Be sure to qualify for your mortgage without rental income so you have flexibility if you decide a roomie or tenant is not for you.

Think beyond the picket fence

Before you make any commitments, do your research and seek out professional financial advice to know what you can afford. For example, you can check out the TD Mortgage Affordability Calculator online to see what budget works best for your situation. Remember, it’s not just a mortgage payment you have to manage – other costs including property taxes, insurance, and ongoing maintenance will add up. Your mortgage payments should be low enough so you can take care of all your monthly expenses, meet your savings goals and still have some wiggle room. It’s also important to have slush funds set aside to cover emergencies and household maintenance.

Protect your investment

Continue Reading…

Generational Business Transition: The Apprentice

By Ian Campbell

Special to the Financial Independence Hub

Synopsis

Love, hate or tolerate U.S. President Donald Trump know that the business-focused reality show he personally hosted for some years was not named “The Apprentice” without careful thought. No doubt that also was true of his hiring several of his children into his businesses.

Over the past 50 years I have advised many “strong personality” owners of both small and very large privately held companies on matters involving business valuation and transition. That experience suggests business owners – likely in combination with more than one advisor – often work to include one or more of their children in management positions in their businesses.

While there are exceptions, in my experience nepotism infrequently works as well as it is planned. That said there are some sparkling successes, where the latter often lead to successful multi-generational business transition – and long-term family business legacies.

So what high-level reasons cause private business owners to hire younger family members – effectively creating an “apprentice environment” – and to often do that when they themselves are in their “prime business years?”

This commentary explores those reasons: none of which are particularly complicated, and none of which are hard to understand in the context of family business owner aspirations.

Family business transition defined

In this article “generational business transition” means the transition of business ownership – and often management – to one or more succeeding generations. Multi-generational business transition means business transition beyond two generations.

Principal “family hire” reasons summarized

There are always exceptions to generalities. Further, in the case of family business transition senior family generation members in control of a family business may make wrong-headed assessments of next generation children or make ill-conceived business management related decisions about one or more of them for over-emotional reasons or simply as a result of bad judgment.

Continue Reading…

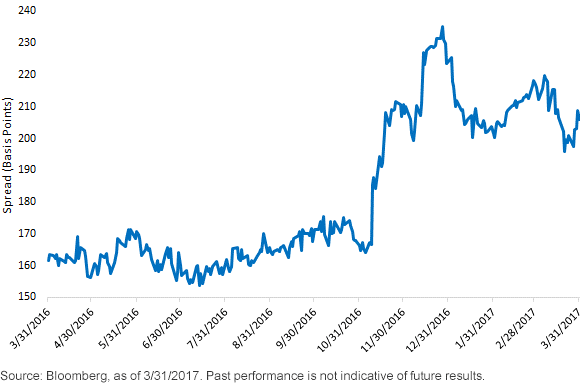
Do global bond yields matter any more?

U.S. 10-Year vs. 10-Year German Bund

By Kevin Flanagan, WisdomTree Investments

Special to the Financial Independence Hub

Do global bond yields matter anymore? Following the results of Election Day and the subsequent response in the U.S. bond market, this was certainly a valid question. Indeed, with U.S. Treasury (UST) yields ascending rather visibly, a key investment force (relative yield advantage vs. the rest of the G7 universe) that had helped keep UST yields in check, if not push them even lower, seemed to fall off the fixed-income radar.

With the first quarter of 2017 now in the books, and the markets almost five months removed from the U.S. election, we thought it would be useful to provide some insight as to where the UST 10-Year yield resides now, and consider whether the relative yield advantage still exists.

While it has not always been a one-way street to the upside, G7 10-year yields have all risen to varying degrees, with the one notable exception being the UK, where gilts have actually seen a decline of 6 basis points (bps) since November 7. Italian 10-year yields fall on the other end of the spectrum, as the 10-year has experienced an increase of 61 bps, while the gain in France has been pegged at 50 bps. To put this in some additional perspective, the rise in the UST 10-Year was +56 bps. Rounding out the 10-year yield tallies: Canada +41 bps; Germany +18 bps and Japan +12 bps.

It should also be noted that the experience thus far in 2017 seems to have been a bit more country/region specific and not just the kind of broader move in global rates that investors have witnessed before. To be sure, here in the U.S., Treasury yields have been responding to developments in Washington D.C., such as the Fed pushing up its first rate hike three months earlier than expected and continued political headlines in the first few months of the Trump administration.

Continue Reading…