All posts by Financial Independence Hub

How to choose the best investments for children

patmckeough
Patrick McKeough

By Patrick McKeough, TSInetwork.ca

Special to the Financial Independence Hub

Investors sometimes ask us how to select the best investments for young children. If children are under the age of 18, they cannot yet invest as adults. However, there are a couple of savings and investment options available.

The first option is for you (or the child) to open a bank account in the child’s name. Interest paid on small balances may range from zero to, say, 1.05% annually, paid monthly. All of the major banks have special bank accounts for children, usually without service fees on basic transactions. However, once the child has accumulated $500, he or she could move the money into an interest-paying guaranteed investment certificate (GIC).

In-trust accounts offer low cost, flexibility

If you want to build up an investment portfolio for a child, then an informal in-trust account is a low-cost and flexible option. Continue Reading…

The real cost of bad habits

MarieEngen
Marie Engen, Boomer & Echo

by Marie Engen, Boomer & Echo

Special to the Financial Independence Hub

This is the time of year when people take stock of their lives and vow to start the new year with a change of habits: stop smoking, exercise, eat better, take care of finances. And yet the majority will fail to keep up with the changes within the first month. Bad habits have both a financial cost and a personal cost, but they also have personal benefits that make them so hard to change.

Being Overweight

Obesity is becoming the norm in North America. It’s partially the result of bad eating habits aided and abetted by fast food supersizes and the cheapness of the least healthy grocery choices. Yes, it’s easy to turn into the fast-food drive-thru when you’re stressed, busy and haven’t taken out anything for supper. Continue Reading…

Vanguard applauds Fed’s move to hike short-term interest rates

Fed funds rate-2By Joe Davis

Special to the Financial Independence Hub

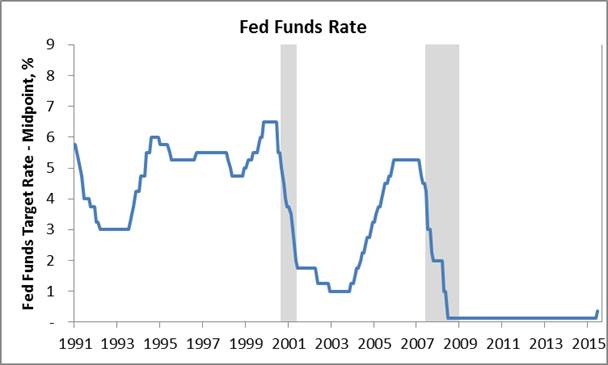
Vanguard applauds the Federal Reserve’s decision to raise short-term rates by 25 basis points. It marks the beginning of the normalization for a U.S. economy, which has made considerable progress over the past six years. Very rarely (if ever) have central banks successfully exited the zero bound and quantitative easing; we believe today’s U.S. Federal Reserve will ultimately prove the first to do so.

Dovish tightening cycle expected

We expect a “dovish tightening” cycle that will likely leave the fed funds rate below the rate of trend inflation for at least a year. Specifically, our non-consensus view is that we will likely see an extended pause near 1%, regardless of the near-term outlook. Reasons for an extended pause in the fed funds rate would include slower-than-expected growth—given still-fragile global economic conditions and the self-limiting impacts of further U.S. dollar appreciation—and the need and desire for the Fed to begin tapering the size of its balance sheet.

An unequivocal positive for savers and long-term investors

As this has been a widely anticipated decision, we do not expect any material impact on financial conditions in the short term. Indeed, we view the Federal Reserve’s decision as an unequivocal positive for both long-term investors and for savers.

In our opinion, those who claim that raising rates is a “policy mistake” that may derail the U.S. recovery underappreciate the still-accommodative stance of monetary policy and the resiliency of the U.S. economy. There is little to no empirical support showing a strong and material link between a 25 basis point rate hike and future U.S. economic conditions given the still-negative real fed funds rate.

Low-rate environment is secular, not cyclical

For bond investors who fear a marked rise in long-term U.S. interest rates, we believe that the low-rate environment is secular, rather than cyclical, and that credit risk in bond portfolios may be a more important factor in 2016 than duration or interest-rate risk.

Davis_Joe_10_aJoe Davis is Chief economist and global head of Vanguard Investment Strategy Group. 


Video: How to Win the Loser’s Game, Part 3

unnamed

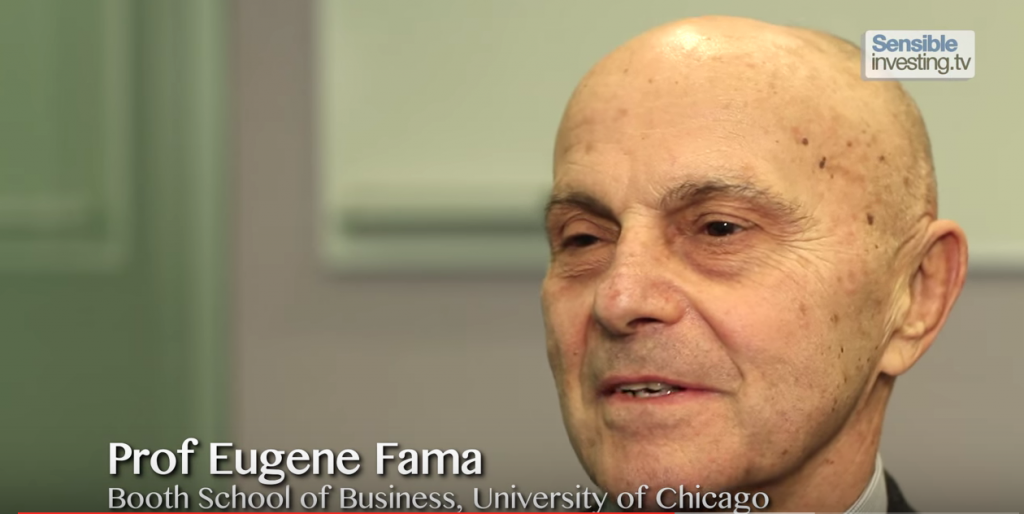
The latest FWB TV video has been posted at FWBSecurities.com and will be archived at Findependence.TV. This 10-minute video is the third of ten installments we’ve been running every other week at the Hub. The title, of course, derives from Charles Ellis’s classic book on indexing, Winning the Loser’s Game. In addition to a clip from Eugene Fama, pictured above, there are interviews with Vanguard founder John Bogle, the IMA’s John Godfrey and a disillusioned former fund manager, Alan Miller. All in all, it’s a pretty compelling indictment of the high costs of active security selection and the benefits of low-cost “index” investing, whether implemented with index mutual funds or exchange-traded funds (ETFs.) For a video primer on ETFs, see this Hub post from last week. Below is Financial Wealth Builder president Paul Philip’s take on this latest instalment:

By Paul Philip
paul_2-1500x994Speak to index/passive investors and if you ask them to explain how they generate the returns the answer is simple and arithmetic: You start with the return of the market, you subtract the costs (usually lower than active investing) and you end up with your net return.

Investors should appreciate this approach for two reasons, the first is that it’s low cost, the second is that it’s evidence-based; it can be proven; there is a formula.

Ask this same question to an active manager and the answer is likely going to be, “I can do better.”

It would have to be their answer because they are getting paid to try and beat the market. It would be absurd to pay anyone to underperform, well at least intentionally. It would be even more absurd for someone to say they are trying to underperform in their job.

Underperformance is not just a symptom of trying to outguess the market or trying to predict the future but is also due to costs eating away at returns.  Active management not only means high trading costs, but also means large marketing budgets — as these investing leviathans spend money trying to convince advisors that their way is better than their competitors. It means spending money developing a brand so that when the advisors recommend these funds to their clients, the clients will feel a comfort level investing in the brand.

Brand and marketing don’t yield a market-beating return.  Simple index and more importantly strategic index investing will more often than not produce the returns that investors seek and will outperform active management.

Paul Philip is president of Financial Wealth Builders Securities, a team of independent wealth advisors providing holistic financial planning, investments and strategies to well informed Canadians. Visit  www.fwbsecurities.com for more investor education and resources.

Car Insurance may never go on sale, but there are discounts

Anne Marie Thomas
Anne Marie Thomas

By Anne Marie Thomas

Special to the Financial Independence Hub

If you install winter tires and live in Ontario, you’re in for some savings next time you renew your car insurance policy or shop around for coverage.

Ontario recently announced that auto insurers must offer drivers who change their tires seasonally a Winter Tire discount come January 1, 2016. To qualify for the discount, you typically have to install a set of four winter tires (with the three-peak mountain snowflake logo) and have the tires on your vehicle between November and April.

The Winter Tire discount, however, is not new. Many insurance providers already offer the discount to policyholders who usually end up saving around 5 per cent off their premiums. The companies that did not offer the discount in the past, must now do so to the benefit of their policyholders who swap out their all-season tires for winter wheels.

This isn’t the first discount to be made mandatory in Ontario. A while back (about 15 to 20 years ago) insurers were required to offer a Retiree discount too. Aside from these two mandated discounts, there are many others that can help you lower your premiums.

Although discounts vary by insurance provider (and sometimes province) they’re a great way for drivers to keep their auto insurance rates in check, but sometimes it’s simply a matter of knowing about them.

Multi-line discount

Probably the most well-known discount is the Multi-line discount. Continue Reading…