Hub Blogs

Hub Blogs contains fresh contributions written by Financial Independence Hub staff or contributors that have not appeared elsewhere first, or have been modified or customized for the Hub by the original blogger. In contrast, Top Blogs shows links to the best external financial blogs around the world.

What is Asset Allocation really?


By Tony Porcheron

Special to the Financial Independence Hub

What everyone wants is for their money to grow without any risk. This is of course impossible, especially over a short time period.

Risk is usually measured by volatility, however risk and volatility are not exactly the same.

Risk for most investors is the chance that they lose money or do not meet their long term financial goals.

Volatility is the amount that your investments go up and down over a certain time period.

sigma  is the usual definition of Volatility

Beta  defines how much a return is based on an underlying index or other investment

Alpha   is your return earned above your index and volatility.

This is the holy grail of investing.

What methods do professional investors use so that volatility does not turn into risk? Asset Allocation.

You may have heard the term, “Don’t put all of your eggs in one basket”, this is Asset Allocation.

In most investment research, 80 to 90% of your investment returns are from you asset allocation, not your individual investment picking. Given this fact, this is what you should be paying attention to more than picking your winning investments.

Asset Allocation is deciding on what percentage of your portfolio should go into asset classes. Generally this is broken up by:

  1. Asset Type (Equity, Fixed Income, Alternative)
  2. Size of the underlying company (Large, Mid and Small)
  3. Geographic Region (USA, Canada, Western Europe, Asia, Emerging Markets)

You then make the decision:

  1. Manager type (Index, Active, Hedge)
  2. What are your financial goals? How close are you to them? Are you contributing or withdrawing money?
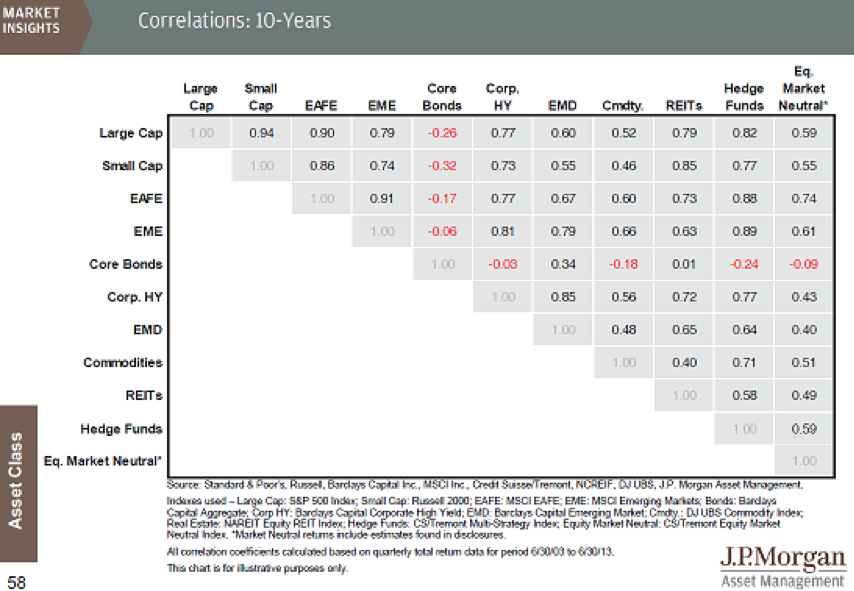
  3. What is the correlation between the different asset classes (how much do they go up and down together

The chart at the top of this blog shows a correlation analysis.

Strategic and Tactical Asset Allocation

The 2 main types of Asset Allocation are Strategic and Tactical. The adjustments to asset allocation are called rebalancing.

Strategic Asset Allocation is determining your asset allocation based on your long term investment return goals, volatility acceptance based on historical investment returns, volatility and correlation. Continue Reading…

G&M: 3 programs to chart your Retirement income & spending

The Globe & Mail newspaper has just published a column by me describing our family’s experience with three Canadian retirement planning programs available to consumers. You can find the full article by clicking on the highlighted headline here: Three online programs to help plan out your finances in Retirement.

These programs vary in price from $85 to more than $800 but just a single insight from any one of them will likely recap the modest fees. I found all three (or four actually) quite useful, seeing as I have already turned 65 and my wife Ruth will follow suit next summer, at which point she too will abandon full-time employment for the kind of semi-retirement or financial independence that this website focuses on.

Some of the planning packages are designed for financial advisors to work with their clients but all can be obtained by individual consumers. They are all strong on the financial side and the first step with any of them is to enter data into your personal computer (PC or Mac, or any device via the cloud). You’ll need your brokerage statements, pension benefits statements if any, tax returns and a good grip on your monthly expenses, which means credit-card and bank statements, and maybe charitable contributions and any other regular expenses not gathered by the foregoing.

Just as important, you need to have at least a rough picture of what your future golden years will be spent doing once you’re no longer tethered to full-time employment.

Decumulation can be more challenging that Wealth Accumulation

All these programs are good at projecting your future retirement income and taxes, factoring in the many moving parts of CPP payments, OAS clawbacks and the other minutae that make the “Decumulation” phase of retirement planning perhaps even more challenging than what the long Wealth accumulation process was.  As Retirement Navigator creator Doug Dahmer (a regular contributor to the Hub) often says, tax is perhaps the single biggest expense in Retirement.

There’s an art to deciding which income sources to drawn down upon first (registered, TFSAs, non-registered), or to deciding whether to defer corporate or government pensions till 70, while drawing on savings in the meantime.

But it’s not just about money: these programs help you identify how you’ll navigate the three major phases of retirement: the early “go-go” years where you may indulge in expensive travel and other hobbies; the “slow-go” years where you pull in your oars a bit and stick closer to home; and finally the “no-go” years where one or both members of a couple start to confront their mortality and deal with rising healthcare costs and perhaps a shift into a retirement or assisted living facility.

Here’s the capsule summary of the strengths and weaknesses of each. The highlighted text in Red will take you to the respective websites: Continue Reading…

How decluttering your Home Office can raise your Productivity

By Melanie Saunders

Special to the Financial Independence Hub

Thinking about boosting your productivity in your home office? Decluttering your office space and creating a tidy working environment might just do the trick. Let’s take a look at some of the benefits of cleaning up your home office.

You won’t get distracted

Working in a clean office means you are less likely to be distracted by different items cluttering up your workspace. It’s quite easy to get distracted by unnecessary objects lying around your desk, so why not remove everything that is not needed and that may distract you from being productive? The truth is that clean offices also make people less stressed simply because mess and clutter can have a bad influence on your focus and make your stress levels jump up to the roof. By making your desks sparklingly clean and moving all the unnecessary stuff to another room, you will definitely see the difference between an organized space and a cluttered work office.

You’ll save time and resourses

If you decide to organize all of your files, you won’t have trouble finding that document you’ve been searching for a week now. Continue Reading…

How the USMCA affects Canadian homebuyers

By Jordan Lavin, Ratehub.ca

Special to the Financial Independence Hub

Goodbye NAFTA, hello US-Mexico-Canada Agreement (USMCA).

The new trade deal with our neighbours to the south will have wide-reaching effects across all areas of our economy, and housing is no exception. While the agreement is said to be good for our economy overall, it’s not necessarily good news for your ability to afford a home.

What is the USMCA?

Canada recently reached an agreement with the United States and Mexico to replace NAFTA, the decades-old trade agreement that has stood since it was signed by Brian Mulroney, Bill Clinton and Carlos Salinas de Gortari.

The new agreement looks much like the old one, with some changes. Key differences include changes to the way the three countries approach auto manufacturing, fewer restrictions on trade of dairy products, and stronger measures against counterfeiting and media piracy. Like NAFTA, the USMCA makes it possible for the three countries to exchange goods without barriers.

For now, the US, Mexico and Canada will continue trading under the rules of NAFTA. The USMCA will come into effect once it’s ratified by its members, a process that could take months. In the United States, congress won’t vote on ratification until some time next year due to that county’s mid-term elections. Here in Canada, the looming Federal election means that if the USMCA isn’t made official by June, it could be delayed until 2020.

How does this affect Canadian housing?

If you’re wondering how having access to American milk at your local Superstore can possibly affect how much mortgage you can afford, you’re not alone. The implications for home affordability are driven by the market’s reaction to the uncertainty of the negotiation period, the removal of uncertainty brought by a signed agreement, and the actual economic growth that’s expected to occur because of the USMCA once it’s in force.

When the Trump administration demanded to renegotiate “the worst trade deal” ever, the market got spooked. As the trade war intensified, the US threatened to (and did) impose significant tariffs on imports from Canada. With repeated threats from our largest trading partner, there was a real chance that the Canadian economy could be jeopardized. Even though our economy was growing during that time, the Bank of Canada (BoC) was reluctant to raise interest rates, which it would normally do in that situation. Continue Reading…

How (not) to trade US midterm elections: you can’t Trump staying the course

Investors should avoid making major portfolio changes in advance of the US midterm elections, says former advisor Dale Roberts

By Dale Roberts

Special to the Financial Independence Hub

When I was an advisor at Tangerine Investments I would have many more-than-interesting conversations with clients about short-term economic and political events; especially over Donald Trump. For those of you who do not live under a rock, Donald Trump is the more than controversial President of The United States. Mr. Trump went from real estate magnate and reality TV show host to the most important chair in the world. Many will write and say that the President who resides over the world’s largest and most influential economy and the world’s most powerful armed forces (by many times over) is the most ‘powerful person’ in the world.

So as investors, and for those who manage money, we should pay attention to what the most powerful person on earth does and says, right?

Nope.

As investors, we don’t invest in Presidents or Prime Ministers, we invest in economies and the companies that help drive those economies. With respect to investing in the U.S. the world’s greatest investor, Warren Buffett, often writes …

Never bet against America.

And heading into the Presidential elections of 2016 Mr. Buffett (a vocal Democrat and Hillary Clinton supporter) offered in a Nasdaq interview …

“America works … I’ve said this before, it’ll work wonderfully under Hillary Clinton, and I think it’ll work fine under Donald Trump … For 240 years it’s been a terrible mistake to bet against America, and now is no time to start.”

Ahhh, and there’s the very powerful and destructive key phrase tucked into that sentience; the two words “bet against.” If you make a short-term move, make a guess on a short term event, you’ve just turned investing into betting/gambling. You’ve turned investing into trading. As the saying goes, on the list of the world’s most successful investors you won’t find any traders.

Successful investors have a long-term outlook and a long-term holding period. Boring works. Excitement is for the casino. When asked what is his favourite holding period for a stock or investment Mr. Buffett will reply “forever.”

So don’t listen to me, but you might listen to the word’s greatest investor: who often states that he has never invested based on a short-term economic event or economic prediction or political event or political commentary.

An investor with a well-balanced portfolio will likely invest in US and International markets. When we invest in America we often own market-leading companies such as Apple, Microsoft, Johnson & Johnson, Walmart, Home Depot, McDonald’s, Coke and Pepsico, Costco, Amazon, Google, Netflix, AT &T, Exxon Mobil, Clorox, Facebook, Colgate-Palmolive, Goldman Sachs, and even Mr. Buffett’s conglomerate Berkshire Hathaway.

You’re not investing in Donald Trump, you’re investing in McDonald’s.

Investors can ignore the midterm elections

If you now understand that you don’t need to pay attention to the current President of the United States, you also do not need to pay attention to the next President of the United States, nor do you need to pay attention to the next group of Congresswomen and Congressmen and Senators who will fill the seats of The House of Representatives. You can ignore the midterm elections on Tuesday November 6th, 2018. You can ignore the Presidential election that will follow two years later. Continue Reading…