Most of your investing life you and your adviser (if you have one) are focused on wealth accumulation. But, we tend to forget, eventually the whole idea of this long process of delayed gratification is to actually spend this money! That’s decumulation as opposed to wealth accumulation. This stage may also involve downsizing from larger homes to smaller ones or condos, moving to the country or otherwise simplifying your life and jettisoning possessions that may tie you down.
Life is uncertain. We are living our day-to-day lives with a certain level of uncertainty, but that’s part of the fun. Some people don’t like having too many uncertainties, so they take actions and precautions to reduce uncertainty.
The same thing can be said for early retirement and living off one’s investment portfolio. There are many steps you can take to increase the margin of safety of your investment portfolio to ensure it can sustain your lifestyle and you don’t run out of money.As we draw closer to achieving Financial Independence through dividend income, also known as living off dividends, we are spending more time on the steps needed to prepare ourselves for this significant financial and life milestone.
I thought it would be interesting to explore the steps we are taking in 2026 when it comes to our early retirement planning.
Building up our Cash Reserve
Along our Financial Independence journey, we have been extremely focused on building up our dividend portfolio. As a result, we have been working hard to grow our savings gap and invest the saved-up money to buy dividend stocks and index ETFs.
For the most part, we don’t keep a lot of cash in our chequing and savings accounts, because we see too much cash sitting around as opportunity cost.
But as we get closer to Financial Independence, it is important to start building up our cash reserve. Cash reserve is important because it provides flexibility and prevents us from having to sell off our investments during a sudden market crash because of some unexpected need.
Last year, we managed to save enough money so that we had over $25,000 in our Long Term Savings for Spending account. Unfortunately, at the time of writing, we are below that number because of the yearly RESP contributions and having to buy a new fridge. Since one of our financial goals is to have more than $35,000 in our cash reserve, this means we need to save up more to first bring the amount in our LTSS account to above $25,000 first, then try to save more to hit the $35,000 market.
But building up our cash reserve is more than just having cash sitting around in our bank account. It’s also about having cash available in our investment accounts, too, as I’ll explain in the next section.
Turning off DRIPs
We are currently investing 100% of our dividend income. We enroll in dividend reinvestment plans (DRIPs), so dividends are automatically used to get additional shares. Years ago, when fractional DRIPs weren’t available, we could only drip full shares (i.e. dividends received were more than the share price). We’d let the remaining dividends accumulate in our accounts until we had over $1,000 before we bought more dividend stocks or index ETFs (we did this so the trading commission was less than 1% of the overall transaction).
Nowadays, with the existence of fractional DRIPs from brokers like WealthSimple and TD, most of our dividends are reinvested right away. Before fractional DRIPs were enabled with TD, and because TD charges $9.99 per trade, we would move the remaining dividends collected in our taxable account with TD to WealthSimple to take advantage of the no-commission trading. We no longer have to do this.
Questrade still doesn’t support fractional DRIPs (and only fractional share purchase on certain securities), so we can only drip full shares and the remaining dividends get deposited in our accounts. Since Questrade no longer charges trading commissions, we don’t need to wait for dividends to accumulate to over $1,000 before reinvesting the money. Lately, we would use dividends to buy more stocks & ETFs when there’s a red day in the markets.
As we get closer to Financial Independence, we plan to change the way we utilize DRIPs. We want to drip selectively. We plan to turn off drip in our taxable accounts and RRSPs by the middle of this year (or by Q3). We will keep DRIP on in our TFSAs to allow investments/dividends to compound.
That’s step one in building up a cash wedge in our taxable accounts and RRSPs for the eventual withdrawals when we do live off dividends. But we certainly don’t want money sitting in cash and not doing anything for us.
So what’s our plan with the dividends received in taxable accounts and RRSPs?
This is where investing in safe Cash Alternatives comes in.
Investing in safe Cash Alternatives
For dividends received in taxable accounts and RRSPs, we want to put them to work. But we don’t want to reinvest them into dividend-paying stocks, then have to sell stocks when we start withdrawing. Nor do we want to be waiting for dividends to accumulate before withdrawing.
Turning off DRIPs will allow us to start accumulating cash. Ideally, we want to accumulate enough money to cover 100% of our expenses for the next year, so we don’t need to sell any stocks. This is one way to increase our margin of safety in early retirement. Another benefit to having sufficient cash for next year’s expenses is that it is easier to budget, since we would know how much money we would have at the beginning of the year.
With the money accumulating in our taxable account, RRSPs, and savings account, we need to look at alternative ways to grow the money so we are not losing purchasing power due to inflation.
Since distributions from these high-yield HISA ETFs are taxed as 100% interest income, they are not overly tax-efficient. Therefore, it makes sense to invest in these HISA ETFs inside of our RRSPs.
Note: I know that withdrawals from RRSPs are taxed as working income as well so there may not be too much of a difference, but income inside RRSPs is tax-deferred so we can let the interest grow until withdrawals. This is a lot better than taking the tax hit in the same year as when you receive the interest.
For dividends sitting in our taxable accounts, if we invest in “safer” investments like GICs, HISAs, HISAs ETFs, bond ETFs, or even money market, all the interest earned would be taxed as 100% interest income, and not very tax efficient. Unfortunately, there’s no other way around it. If we really want, I suppose we can invest the money in dividend-paying Canadian stocks, but that’d go against the idea of building up a cash reserve in our taxable accounts.
Therefore, it probably makes the most sense for us to just take the tax hit and invest dividends in our taxable accounts in one of the HISA ETFs or move the money and start building a GIC ladder if the rates are attractive. (Knowing the low interest rates environment we’re in, probably hard to find attractive rates for short term GICs).
What would we do with the cash sitting in our LTSS? Well, we may consider parking some of it in cash inside a flexible high-interest savings account for planned expenses. To make sure money is working hard for us, it probably makes sense to invest the money in a high-yield HISA ETF.
Our plans with money in taxable accounts and LTSS aren’t 100% decided. More tax calculation and planning is needed, considering I will be working full-time and earning income in 2026 and Mrs. T is generating income via her side hustles.
If any readers have other suggestions or recommendations on what to do with cash in our LTSS and taxable accounts, I would love to hear them.
Alternatively, we can consider turning DRIP off first in our RRSP and invest the money in one of the HISA ETFs. Then, in the latter half of 2026, turn off DRIP in our taxable accounts to minimize tax consequences. This approach, however, means we won’t have as big a cash reserve.
It’s complicated to plan everything and that’s part of the fun of planning for early retirement!
Planning extended healthcare coverage
We currently have extended healthcare benefits through my employer. The extended healthcare benefits allow us to get coverage on prescription drugs, out-of-country trip medical coverage, paramedical services like massage, acupuncture, counselling, physiotherapy visits, vision care, and dental care. Continue Reading…
Regular readers of this site are probably well aware of ETFs (Exchange Traded Funds). Indeed, many blogs here have covered their role either as Core holdings of Retirement portfolios or portfolios still in the Wealth-building phase. Some espouse ETFs as a Core holding but play around at the fringe with so-called “Explore” investments either in high-conviction individual stocks or in more tactical specialized ETFs. Many espouse a “hybrid” strategy of mixing ETFs with individual stocks, perhaps by “skimming” the same ETFs for particular stocks that appeal at some level, whether for income, growth or other reasons.
Roughly once a month for much of the existence of this site, Featured.com has provided useful content on investing and retirement. In the past year, it changed its strategy so editors like myself could have more input into the creation of its blogs. Now the process is one of posting a question or general request to its site, soliciting input from a wealth of largely US-based financial experts and business owners.
Today’s blog focuses on various strategies on ETFs and variants of using them as Core or Explore holdings, plus the pros and cons of the “hybrid” approach mentioned above. Most of these experts are on LinkedIn, as you may see by clicking on their company names below each entry.
Here’s how we posed the opening question for respondents:
When it comes to managing your personal Retirement Funds or that of clients, what role do ETFs (Exchange Traded Funds) play: Core, Explore, Tactical or what? If you do use ETFs, do you prefer to use them exclusively or do you like hybrid strategies where you also pick individual dividend-paying or growth stocks; or do you also cherry-pick individual stocks from favorite ETFs?
So with no further ado:
Hybrid Strategies of mixing ETFs with individual stocks can lead to trouble
When it comes to the role of ETFs, for the vast majority of people — especially the ones I see in my practice trying to build stable long-term wealth — they belong in the “Core” position. ETFs are a brilliant legal and structural innovation: they provide instant diversification, they are incredibly low-cost, and they are tax-efficient. They allow you to own the market rather than trying to guess which individual company will win, which is essentially an impossible game for most humans to play consistently over 30 years.
The hybrid strategy — mixing ETFs with individual dividend or growth stocks —is tempting, but it is often where people get into trouble. “Cherry-picking” individual stocks is not investing; it is gambling with better marketing. I have represented clients who lost their retirement savings because they became over-concentrated in a single “favorite” stock that cratered. When you cherry-pick, you aren’t just betting on the company; you are betting against the market, the sector, the economy, and your own lack of inside information.
If you are a professional investor with the time to research, the discipline to rebalance, and the stomach for volatility, go ahead. But for the average person, or even the professional focused on their own career, the most successful strategy is usually the simplest: Core, boring, broad-market index ETFs.
The most successful retirement portfolio is often the one you forget you own, not the one you tinker with every week based on a “hot tip” or a gut feeling. I’ve never seen a client file for bankruptcy because they were too boring with their index funds. I have seen clients file because they tried to get clever with individual stocks and got decimated by a market downturn. Complexity is rarely your friend in long-term wealth building. Keep it simple, keep costs low, and let time do the heavy lifting. That isn’t just good investment advice; it’s sound risk management. — Lyle Solomon, Principal Attorney, Oak View Law Group
ETFs are foundational to my plan for retirement. The consistency and broad market exposure that they represent allow them to be at the core of all of my other investment decisions. I use a blended model. In order to achieve this blend, I have selected low cost indexed products (that provide for consistency) in addition to specific dividend producing stock selections to provide additional income. — Zack Moorin, Founder, Zack Buys Houses
ETFs as Core with individual Satellite positions like Crypto
My personal approach to retirement portfolio construction uses ETFs as the core, with a satellite allocation to individual positions including crypto assets.
The core ETF layer serves a specific purpose: broad market exposure at near-zero cost, with automatic rebalancing and no single-company risk. For U.S. equity exposure, a total market or S&P 500 ETF handles this. For international exposure, a developed-markets ETF. For bonds, a total bond market ETF scaled by risk tolerance and time horizon. This core doesn’t require active management or conviction: it just needs to capture beta.
The satellite layer is where I allocate capital I’m willing to analyze actively and hold with genuine conviction. For me, this includes individual positions in companies I’ve studied deeply and blockchain assets backed by whitepapers I’ve read and evaluated (through ChainClarity’s own research process). The satellite allocation is sized so that a complete loss wouldn’t materially affect the core goal.
Why I don’t go pure ETF: I find that having no individual positions reduces my engagement with the market as a learning mechanism. Tracking companies or protocols I own forces me to read earnings reports, understand industry dynamics, and notice when my thesis was wrong. That active attention makes me a better analyst, which has compounding value beyond the direct investment return.
The hybrid strategy I’d caution against: owning both an S&P 500 ETF and individual U.S. large-cap stocks. The ETF already owns those companies: you’re just adding concentration risk and management overhead without meaningful diversification. If you’re going to pick stocks, pick categories the ETF doesn’t cover adequately.
Roman Vassilenko is the founder of ChainClarity (chainclarity.io), an AI platform that makes blockchain whitepapers accessible to investors and developers. — Roman Vassilenko, Founder, ChainClarity
Active Strategies only work if you a demonstrable Edge
The statistics don’t favor an active equity allocation strategy. Over the 10 years ending 2021, 84% of U.S. large-cap growth funds lost to their benchmark, the S&P 500. Even if we add back some of those funds to the universe that died along the way, the failure rate only drops to 91%. You might still have to explain why you’d invest money for a 0.66% expense ratio, which is what active equity funds average compared with 0.03% for their passive alternatives (SPY, VOO). On $500K invested for 30 years that grows at a real rate of 7% annually, you can expect to have spent nearly $387K in fees over your investment horizon. Half of this goes to the active funds manager, whether they perform well or poorly.
The exception to this advice comes if you feel an edge exists. Perhaps you work in Silicon Valley and have insight into Netflix or perhaps have engineer-level technical understanding on why a company’s underlying product will prevail over competitors, but unless you genuinely possess such an asymmetric advantage, most of the advice below comes from investing in low-cost ETF cores, keeping a few per cent in cash or cash alternatives and picking one or two individual stocks that you’re willing to lose money entirely, without jeopardizing your Financial Independence. I think anything beyond that could fit onto one side of a sheet of paper. — Jere Salmisto, Founder, CalcFi
ETFs remove the big risk of your own Decision-Making
Most investors treat ETFs as a convenience tool, but their real power is that they quietly remove the biggest risk in portfolios: your own decision-making.
I think of ETFs as a “behavioral anchor.” In most retirement strategies, they should be the core, not because they outperform everything else, but because they reduce the chances of overtrading, emotional decisions, and concentrated mistakes. They create a stable base you’re less tempted to interfere with.
In practice, I’ve seen this play out repeatedly. Clients who built portfolios purely on individual stock picks often drifted into overexposure or reactive selling during volatility. In contrast, those with ETF-heavy cores made fewer impulsive changes and stayed aligned with long-term goals. When we added individual stocks, it was deliberate and limited, more of a satellite layer than a competing strategy.
The takeaway is simple. ETFs are not just about diversification, they’re about discipline. Use them as your foundation, then layer in individual stocks only where you have conviction and a clear reason. The goal isn’t to outperform the market every year, it’s to avoid the mistakes that quietly destroy returns over time. — Omer Malik, CEO, ORM Systems
ETFs are my core. Period.
ETFs are my core. Period. I don’t have the time or the ego to think I can outpick the entire market with every dollar I own. My retirement strategy is built exactly like our risk models at Insurance Panda: you need a massive, diversified base to survive the outliers. I put the vast majority of my capital into broad-market index funds and let them ride. It’s the only way to ensure you actually have a pile of cash when you’re ready to exit the game.
But I’m a business owner, so I can’t help but look for an edge. I use a hybrid model. I keep the boring foundation in ETFs, then I pick individual growth stocks in sectors I actually understand: specifically digital infrastructure and software. I don’t bother “cherry-picking” individual names from a favorite ETF. That’s just over-analytical busywork. If I see a company we’re actually using in our own tech stack that’s clearly dominating its niche, I buy the stock directly.
And here is the hard truth. Most people mess this up by being too tactical with money they can’t afford to lose. They treat their Retirement fund like a casino. Don’t do that. Secure the base layer first with low-cost funds. Then, and only then, use your actual industry knowledge to take a few shots on individual winners. If you don’t have a clear information advantage, stay in the index. — James Shaffer, Managing Director, Insurance Panda
ETFs should be the core 70 to 80% of your Retirement Portfolio
To any of our MintWit readers who are saving for retirement, my advice will be to build the bulk of your retirement portfolio using ETFs because they provide instant diversification and very low fees. In essence, ETFs will form the basis, or the bread and butter, as part of your investment strategy, making up 70%-80% of your retirement portfolio. The message we always preach is that you use the ETFs as a safety measure; then you explore by buying a few stocks, such as those paid by dividends from companies such as Johnson & Johnson and Coca-Cola, to make up the remaining 10%-20%. –– Scott Brown, Founder, MintWit
ETFs as Core help maintain Target Allocations
ETFs are most useful as core holdings in a retirement portfolio because they offer broad exposure and make it simple to maintain a target allocation. I recommend using ETFs to establish the backbone of a portfolio, then layering in individual dividend or growth stocks only when they serve a clear, specific purpose. Relying exclusively on ETFs can work for many investors, but a hybrid approach lets you target income or single-stock opportunities without losing diversification. Keep the overall asset allocation aligned with your risk tolerance and time horizon. Automate contributions and set a regular rebalancing schedule so ETFs and any individual holdings stay within your intended ranges. Consult a qualified advisor for tax and account-structure considerations before making changes. — Amir Husen, Content Writer, SEO Specialist & Associate, ICS Legal
Hybrid Strategy uses indexing and select individual stocks
I view EFTs (Exchange Traded Funds) as my base of operations for overall market exposure and stability. I prefer to implement an index fund or hybrid strategy which incorporates both index investing and selected individual stock investments into my portfolio. The Hybrid Strategy will allow me to maintain broad based investment diversification by utilizing index fund(s), and also pursue greater returns on investment via selected individual equities. At times, I review the top holdings in the most popular EFTs to see if they are among my potential long-term investment options. — Mike Otranto, Founder, Wake County Home Buyers
ETFs belong in the Retirement core bucket but not a fan of Index Skimming
I’m coming at this as someone who’s been in estate planning since 2008 and now leads operations at Safeguard in Arizona, where retirement planning and asset protection are part of the same conversation every day. My view is that ETFs usually belong in the core bucket because retirement money needs clarity, liquidity, and a structure that’s easier to coordinate with the rest of the estate plan.
What matters most to me is not “ETF vs stock” in isolation, but whether the investment setup works cleanly with beneficiary designations, trust funding, and the reality of incapacity or death. A simple ETF-based core is often easier for a spouse, successor trustee, or family to understand and manage than a scattered collection of hand-picked positions.
I’m generally more comfortable with a hybrid only when there’s a clear purpose for it, not because someone wants more activity. For example, if a family has a living trust and wants long-term retirement assets organized so a successor trustee can step in smoothly, broad ETF holdings tend to create fewer administrative headaches than a portfolio full of one-off stock ideas.
I’m not a fan of cherry-picking names out of favorite ETFs just because they showed up on a list. In retirement and wealth preservation, I’d rather see a plan that accounts for inflation, Social Security timing, healthcare costs, and smooth transfer to heirs than a portfolio that becomes harder to administer when the family needs simplicity most. — Julie Jewett, Director of Operations, Safeguard.
ETFs should have a clear purpose, like Targeted Income or Tactical Exposure
I view ETFs as core building blocks of retirement portfolios, especially for taxable accounts, given their tax characteristics. Asset location is critical, so I often favor index ETFs in taxable brokerage accounts to help control when gains and income are realized.
Dividend-paying stocks and corporate bonds are typically better held in tax-advantaged accounts to avoid current taxation on dividends and interest. ETFs that do not distribute frequent income also give more control over timing because you generally recognize gains when you sell.
However, I do not use ETFs exclusively. I treat them as the foundation and layer individual securities when they serve a clear purpose, such as targeted income or tactical exposure. The precise mix depends on a client’s tax situation, income needs, and retirement phase, with asset location guiding those choices. — Clint Haynes, Financial Planner, NextGen Wealth
The point of ETFs is to provide exposure to an idea without taking single-stock blowup risks
ETFs are immensely diverse, that’s the first thing to clear up. Income ETFs, dividend-growth ETFs, low-volatility ETFs, broad-market index ETFs, growth ETFs, and speculative covered-call funds (YieldMax, Roundhill) are all ETFs, but they serve fundamentally different roles. Their shared job is to express an investment thesis with diversification. The point of an ETF is to give you exposure to an idea without taking the single-stock blowup risks (management, execution, etc.) that come with picking individual names.
For Retirement, low-volatility and dividend-growth ETFs are the natural fit, because they prioritize stability of distributions and capital preservation, which is what matters when you’re drawing down rather than accumulating. Speculative income products like YieldMax or Roundhill weekly-pay funds can play a role, but they’re a speculative income tilt, not a core retirement holding. The high headline yields often come at the cost of NAV erosion that trailing yield figures don’t show. A retiree leaning on these without understanding the option-writing mechanics underneath can find their principal halved over five years even while collecting “income.”
Growth ETFs are a different beast entirely. Their volatility and lower (or zero) distributions don’t suit the liquidity and income needs of someone in retirement, but they’re the right call for accumulators in their 20s, 30s, or 40s with decades-long time horizons. Different season, different tool.
On methodology: the right way to think about an ETF is bottom-up, not top-down. If you research the underlying stocks and like what you see, the businesses, the dividend track records, the valuations … you buy the ETF as a convenient, low-cost container for that thesis. It’s not a common or advised investment strategy to cherry-pick individual stocks out of an ETF you like, without having done the individual fundamental work. That’s reverse-engineering: you’ve already paid for the diversification, picking out individual names just adds concentration risk while losing the structural benefit. If you want concentrated exposure to one or two names, buy the stocks directly. If you want diversified exposure to a thesis, hold the ETF that expresses that thesis.
Across age cohorts and goals, the principle is the same: an ETF is a way to express a stock thesis efficiently, not a substitute for having one. — Ignacio Planas Gonzalez, Founder, YieldMaxCalc Continue Reading…
By Dana Anspach for Fritz Gilbert and The Retirement Manifesto
Special to Financial Independence Hub
Like many teenage girls, I had my high school bedroom walls covered in posters. Actor Rob Lowe took center stage, with a bit of Matt Dillon sprinkled in. (Ladies of the ’80s … any of you relate?)
Mixed in with the heartthrobs were glossy posters of red sports cars. Ferrari. Lamborghini. Later, in college, an Acura NSX.
Looking back, it’s strange. I’ve never been much of a car person: especially not sports cars. I don’t see well out of them. They’re low to the ground. I scrape rims, bump curbs, and the quick handling leaves me feeling slightly queasy.
So why the fascination?
I think those cars represented success. Flashy. Fast. The kind of thing people ‘oohed’ and ‘ahhed’ over.
Defining success by external standards is dangerous business. Thankfully, I outgrew that particular distortion: though I’m sure plenty of others remain.
As an adult, I gravitate toward practical, balanced cars. What I think of as the all-weather vehicle. I don’t need to go 200 mph down the autobahn. But I do want traction in heavy rain. I don’t care about making a statement at the valet. I care about glancing in the rearview mirror and seeing my dog’s smiling face as we head to his favorite place on earth: the park.
That preference for balance turns out to matter far beyond cars. It’s also the way I believe we should approach retirement planning and investing.
The Case for an All-Weather Approach
In hindsight, those sports car dreams and investing have something in common. Sometimes, it’s hard not to hop into the shiny red sports car and drive away.
In investing, a shiny investment (like the shiny red sports car) promises speed and excitement. It may not be as reliable, but for a brief moment, it makes us feel brilliant. Powerful. Maybe even a little invincible. In touch with our inner James Bond. And who doesn’t want to feel like a secret service spy just once in their lifetime?
Often, it shows up as a single stock. Sometimes it’s a real estate deal. Or a business venture. It feels adventurous. Sophisticated. Like we’re seeing something others don’t.
In the late 1990s, tech stocks were the shiny red sports car.
The firm I worked for at the time offered a Science and Technology Fund that rose 99% in twelve months. One day, a middle-aged couple came in and asked me to move their entire portfolio into it.
Durability vs. Speed
Their portfolio had been built for durability:
blue-chip stock funds,
international exposure,
a few bond funds,
and a small allocation to the Science and Tech Fund.
They had spent a year watching the tech fund soar, while everything else stood still.
I balked at their request. I explained the logic of balance. Sure, in perfect weather, the shiny red sports car looked great. But the weather wouldn’t always be so accommodating.
My logic sounded silly to them: like a mom insisting you put on your helmet to ride your bike down the street.
They insisted on the change. I acquiesced on one condition: they sign a disclosure acknowledging that this was against my recommendation. They signed without hesitation.
I left that firm before the dot-com crash and the miserable weather that followed. I’ve often wondered what happened to that couple. The allure of speed was too strong.
Today, I see that allure creep in when retirees keep a “play” account. They go all in on a few stocks and attribute their success to their stock-picking prowess.
You can go all in with a play account. But a professional financial advisor can get sued if they do the same thing with your entire life savings. That should give you pause. Risk and return are sides of the same coin. But each time you flip, if it’s several years of heads, it is all too easy to forget that the coin even has another side.
Beware the Slight Upgrade
Not everyone is tempted by flashy sports cars. Sometimes the pull is subtler.
We start to think maybe a small upgrade will help. Something just a little faster. A little more responsive. Even if it doesn’t handle storms quite as well.
I watched this at the end of 2024 when a long-time client, whose retirement plan and portfolio were in solid shape, left because they felt they should be earning higher returns. Continue Reading…
Why I do not recommend them — private or liquid — and what most investors do not fully understand
Unsplash: Markus Winkler
By Steve Lowrie, CFA
Special to Financial Independence Hub
I am often asked about alternative investments. My first response is always the same: alternative to what?
Because most of what is being presented as “alternative” is not something new or better. It is often the same wine in a different bottle.
I do review alternative strategies, as I look at all types of investment strategies, but from a high-level, evidence-based perspective. Not by spending time on the individual deals and marketing pitches that arrive almost daily.
Let me be direct. Despite the heavy marketing push behind private credit, private equity, liquid alternatives and similar strategies, I do not recommend them. I have not recommended them in the past, and I do not recommend them now.
In my experience, investors in these structures often do not fully understand what they own, how they are priced, when they can access their money, or the underlying risks.
Those are not minor details.
A recent reminder
At a portfolio manager roundtable a few months ago, one advisor shared that more than half of his clients’ assets were invested in private alternative structures. It was presented as a sign of sophistication.
Only a few months later, U.S. press coverage began highlighting private-credit funds facing large redemption requests. In response, many of these funds have been limiting withdrawals or placing restrictions on how much investors can redeem.
Closer to home, several large, well-known Canadian alternative asset managers have recently halted redemptions, leaving investors unable to access their money for extended periods. If you have lived through that, you already know how it feels. If you have not, the experiences of those investors are worth taking seriously before you ever considered investing.
None of this should be surprising. If you invest in illiquid assets, there will be limits on liquidity. The underlying investments, such as private loans or real estate, cannot be sold quickly. That is how the structure is designed.
The concern is that this reality is often lost in how these investments are presented.
When new information becomes available, it should shape how we think about risk.
It raises a more important question. Is this actually improving outcomes for clients, or is it introducing risks that have not yet surfaced?
Concentrating that much of a portfolio in illiquid, opaque investments is not sophistication. It is risk, just not the kind you see right away.
What are alternative or private investments?
Alternative investments are investments that are not publicly traded. They include private credit (lending directly to businesses), private equity (ownership in private companies), direct real estate or infrastructure assets held in pooled structures.
The key difference is not what they invest in, it is how they are structured. These investments vehicles are:
Not continuously priced
Not easily sold
Not fully transparent
The underlying exposures, corporate lending, real estate, business ownership, can all be accessed through public markets. The issue is the structure, not the asset class. I have made this point before in the context of real estate, where publicly traded REITs offer a cleaner path than direct property ownership, and in the context of gold, where exposure already exists indirectly through the broader market.
Why are these strategies being sold so aggressively to individual investors?
The pitch typically centres on three claims: better diversification, lower volatility, and higher expected returns. These claims do not naturally go together. Higher expected returns typically come with higher risk, not less.
There is some historical basis for this, but only in a very specific context, and one that is not usually explained clearly.
What about the endowment model?
A common argument from advisors recommending alternative investments is that large U.S. university endowments, such as those at Harvard, Princeton, and most famously Yale, have used meaningful allocations to private investments for decades and have generated strong long-term returns.
A bit of background: The Yale Endowment, under the late David Swensen, became the most well-known example of what is sometimes called the “endowment model” – a portfolio approach that allocated heavily to private equity, hedge funds, real assets, and other alternatives, rather than to traditional stocks and bonds. The strategy delivered strong results over an extended period, and many other institutions tried to copy it.
That history is real. But two things are worth noting before applying it to an individual investor’s portfolio.
First, those results depended on advantages most individuals cannot replicate: first-look access to the very best private fund managers, negotiated fee structures, multi-decade time horizons that genuinely do not need liquidity, and full-time investment teams to perform deep due diligence.
Second, the asset class itself has changed. As private investments have been packaged for broader distribution, more capital is chasing the same opportunities, the return advantage has narrowed, and the best managers are generally not the ones marketing to retail and mass-affluent investors. Even some of the original endowment-model institutions have been reassessing their allocations.
What has worked well in the past is often difficult to repeat going forward.
In some cases, sophisticated investors are reducing exposure while less experienced investors are being encouraged to step in. Whether intentional or not, that raises an important question. Is this about better investing, or better marketing?
Is the illiquidity a problem?
Yes, it can be.
There is a concept known as the illiquidity premium. If you give up access to your money, you should expect a materially higher return in exchange.
For that trade-off to make sense, two things must be true. You actually receive the higher return, and you fully understand and accept the loss of liquidity.
What we are seeing now raises questions about both. Liquidity rarely feels important until the moment you need it and that is typically when it matters most.
As an example, several large alternative asset managers, including in Canada, have had to limit withdrawals, delay redemptions, or fully gate funds. Gating means you ask for your money back, but you cannot get it on your timeline. You get it at the manager’s discretion. And this often happens at the same time the underlying investments are under pressure, which is usually the reason for the restrictions in the first place.
Why do private investments appear so stable?
Because they are not priced in real time.
Private investments are typically valued periodically, often using models rather than actual transactions. That creates the appearance of smoother returns. But smoother does not mean safer.
Lower reported volatility often reflects how the investment is priced, not what is actually happening underneath.
It often just means changes in value are being reported more slowly.
A recent Dimensional article makes this point clearly. Without continuous pricing, it is difficult to assess the true condition of private credit investments, and publicly traded proxies may provide a more current signal. Exhibit 1 in the Dimensional piece shows that while broad stock and bond markets were positive over the past year, a publicly traded proxy for private credit declined by more than 13 per cent.
That difference is not trivial, and it highlights how private valuations can lag what is happening in real markets.
What about liquid alternatives?
A common response to the liquidity concerns above is: “But what about liquid alternatives, the ones offered as ETFs or mutual funds with daily liquidity?”
These products solve the liquidity problem on the surface. You can buy and sell them like any other fund. But they do not solve the underlying problem with the strategy.
The fees are still high, often well above what you would pay for traditional equity or fixed income exposure. The strategies inside are often complex, opaque, and difficult to evaluate. And the long-term net-of-fees track records of many liquid alt strategies have been weak or negative.
There is also a more subtle issue. When a fund offers daily liquidity for strategies whose underlying instruments are not themselves daily-liquid, the wrapper is promising something the underlying cannot reliably deliver. Under normal conditions, this is not visible. Under stress, it can be.
Changing the wrapper does not change the strategy. If the underlying approach is expensive, complex, and unlikely to add value over time, putting it in a more liquid package does not fix that. It just makes it easier to buy.
So no, I do not recommend liquid alternatives either.
A simple framework for evaluating any investment
When clients ask me about a new investment idea, I encourage them to ask three questions before going further:
Does it produce a reliable expected return that compensates me for the risk?
Can I access my money when I need it?
Can I clearly understand what I own and how it is priced?
Most alternative investments, private or liquid, struggle to meet all three.
There is also a common belief that access to private investments provides an advantage. In reality, broader access often comes after the most attractive opportunities have already been captured.
That does not make them useless in every context. But it does make them difficult to justify as a meaningful holding in a long-term portfolio. Continue Reading…
That blog inspired me to reach out to multiple financial experts and business owners, with the assistance of Linked In and Featured.com, which has been supplying this site with quality content for several years.
Here’s how we posed the question:
Can you pursue Financial Independence (or Retirement or Semi-Retirement) without giving up Travel? See this blog for one opinion on this topic:
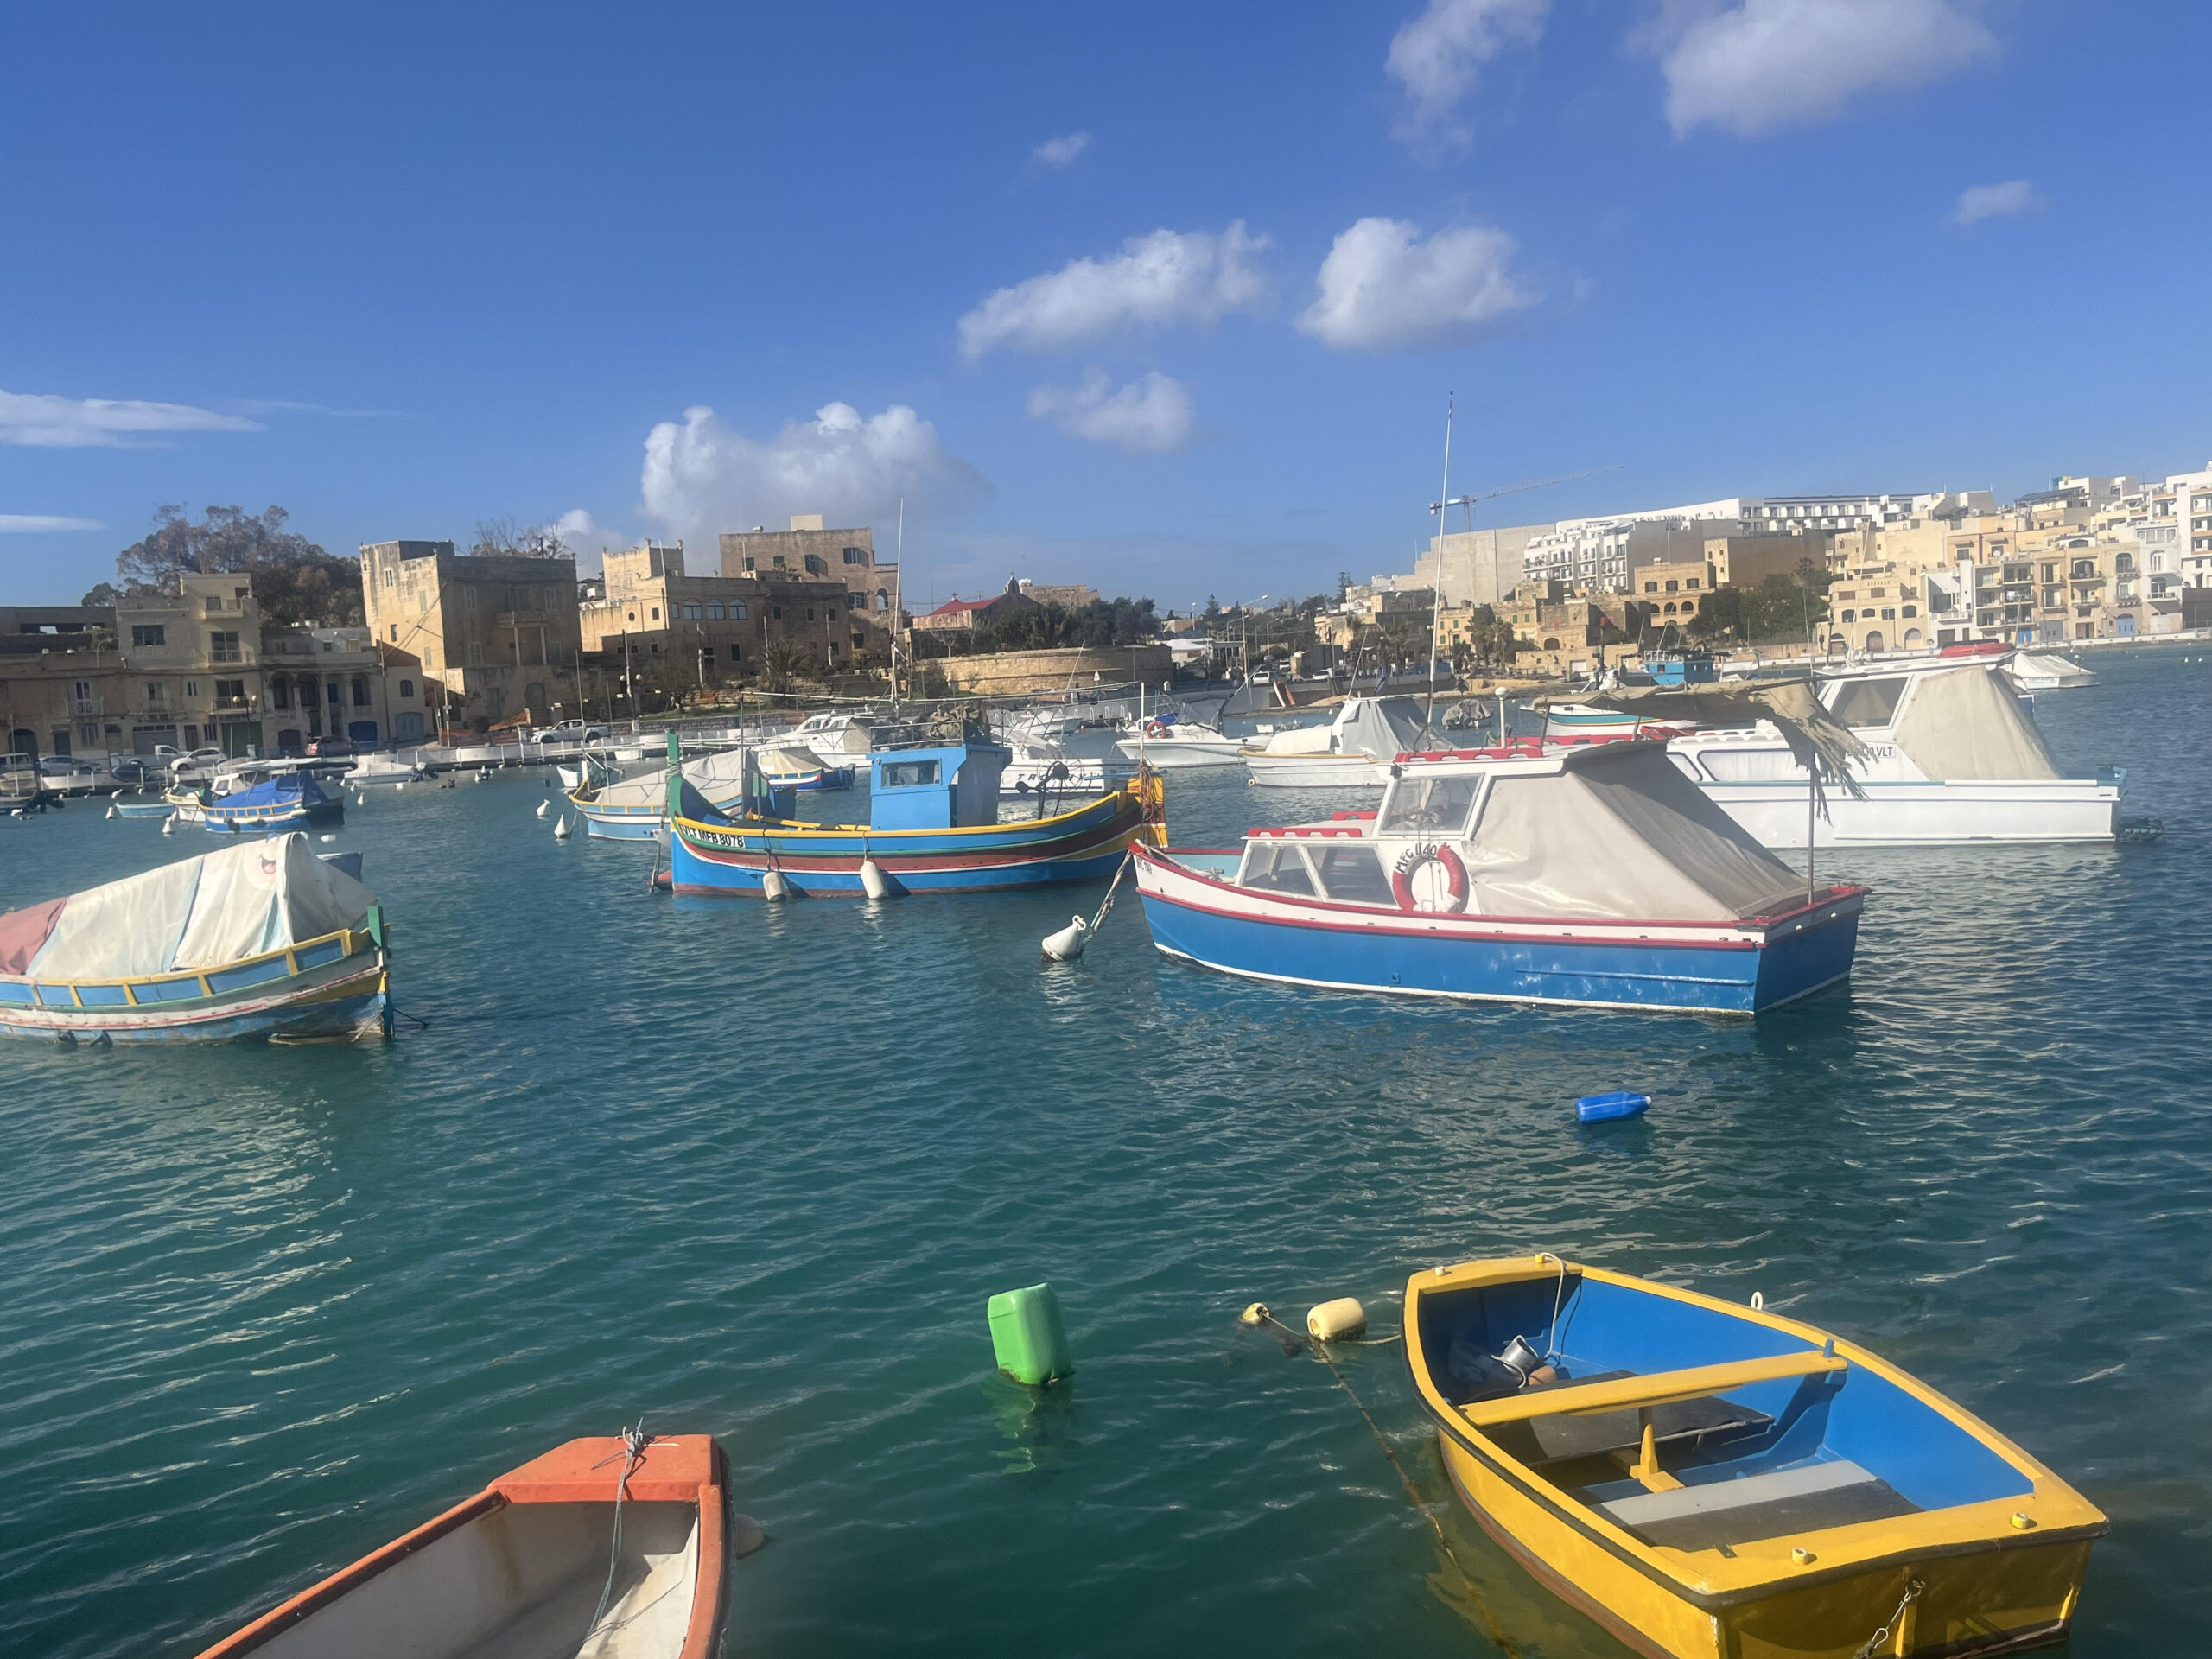
Malta: where we spent most of February this year. Photo by J. Chevreau
This particular topic attracted 84 comments by the April 20th deadline: this blog presents 25 or so that I selected. It’s long so I’ve summarized the main points with subheadings.
Note also that my latest MoneySense Retired Money column summarizes some of the main points, more succinctly as there is limited space for that column (about 1300 words, compared to the nearly 6,000 words that appear in the particular blog you are now reading).
To ease the reading burden, I’ve added subheads, some of which include:
Geoarbitrage: Live where cost of Living is lower
Renting RVs for Extended Travel Stretches
Make Travel a regular fixed expense you plan on incurring every month
Treat Travel as a budget category, not a luxury to eliminate
Embrace slow travel, house-sitting, points travel hacking and off-season destinations
Buy property in tourist spots to fund Travel
Majority of Professionals can now work remotely
The “goal isn’t to eliminate travel, but rather to make it more intentional.”
“Bleisure”: Let your career fund your transit
As President of Safe Harbors Travel Group, I’ve spent decades helping organizations use strategic logistics and “Bleisure” to explore the world without draining the bottom line. You can reach Financial Independence by letting your career fund your transit; we often help clients integrate vacation days into business trips to eliminate personal airfare and lodging costs.
A key strategy for the budget-conscious traveler is utilizing “humanitarian airfares,” a specialized airline product Safe Harbors provides that offers significant savings for anyone doing charitable, religious, or mission-based work. These fares are a powerful hack for those pursuing a purpose-driven life while keeping their personal travel expenses at a minimum.
By leveraging our elite tech partnerships for data-driven booking, you can ensure “duty of care” and response speed that prevents the costly emergencies often associated with unmanaged travel. This structured approach allows you to focus on wealth building while Safe Harbors handles the complexities of your global footprint. — Jay Ellenby, President, Safe Harbors
Build Travel into the system, not just a later Reward
Yes: you can chase FI or semi-retirement and keep travelling if you build travel into the system instead of treating it like a reward you “earn later.” I’ve run logistics/transportation businesses for years and now my wife and I host 15 furnished units in Detroit/Chicago, so I’m used to designing operations that still run when I’m not physically there.
What made it work for us is shifting travel from “big expensive trips” to “repeatable, planned mobility.” We use our Detroit-focused blog as a planning engine: when we travel, we test neighborhoods, transit (Q-Line/SMART/MoGo), and local routines the same way a guest would: then we bake that learning back into listings and guest guides so travel time also improves the business.
The practical FI move is making your income less dependent on your daily presence. Guest reviews told us people wanted clearer walkthroughs, so we added walkthrough videos to each property page and saw a 15% increase in booking conversions: less back-and-forth, fewer preventable questions, more freedom to be away while keeping standards consistent.
If you want one tactic you can copy: record a 5-8 minute “first night in the unit” walkthrough (lockbox – thermostat – Wi-Fi – parking – trash) and reuse it forever. That single asset cuts support load while you’re on the road, and it’s the difference between “I can travel” and “travel breaks my cashflow.” — Sean Swain, Company Owner, Detroit Furnished Rentals LLC
Geoarbitrage: Live where cost of Living is lower
Geoarbitrage allows you to live in an area with a lower cost of living for your family while allowing your investment portfolio to grow. The combination of using travel rewards on credit cards and traveling during less expensive times reduces your travel costs. This approach to finding money saving ways to see the world makes international exploration a viable way to maintain your lifestyle versus making it a luxury. — Zack Moorin, Founder, Zack Buys Houses
Geoarbitrage and the Second Act Advantage
In The Second Act Advantage, I show how geoarbitrage lets anyone achieve financial independence without sacrificing travel: in fact, it makes travel the strategy. By earning in strong currencies while living and exploring more affordable parts of the world, everyone can enjoy a richer, more adventurous life while actually spending less. The book teaches readers how to design a life where freedom, fulfillment, and financial efficiency all work together. — Jay Samit, Bestselling Author, The Second Act Advantage
Transitioning from Vacationing to Geo-arbitrage
The Travel-First Strategy: Designing FI Without Sacrifice
A common misconception in the FIRE (Financial Independence, Retire Early) community is that travel is a luxury to be deferred until the finish line. However, in my experience advising lifestyle-focused entrepreneurs, pursuing financial independence without giving up travel isn’t just possible it’s often a more sustainable strategy for preventing burnout.
Shifting from Consumer to Global Resident
The key is transitioning from vacationing to Geo-arbitrage. Traditional travel involves paying retail prices for short-term stays, which can cripple a savings rate. A strategic traveler focusing on FI prioritizes medium-term stays in regions where the cost of living is lower than their home base. By spending months in hubs like Portugal, Mexico, or Southeast Asia, you can often live a high-quality lifestyle for 40% less than in major Western cities. In this model, travel actually accelerates your path to financial independence by lowering your monthly burn rate.
Leveraging Credit Strategy as an Asset Class
From a PR and financial positioning standpoint, we should treat travel rewards not as points, but as a shadow asset class. A sophisticated FI seeker uses strategic credit card optimization to ensure that their transportation and lodging line items remain near zero. When flights and hotels are covered by systemic spending, travel stops being a drain on investment capital and becomes a tool for lifestyle maintenance.
The Semi-Retirement Pivot
The all-or-nothing approach to retirement is becoming obsolete. We are seeing a rise in Coast FIRE, where individuals reach a baseline of savings and then transition into remote-first or consulting roles. This allows for perpetual travel while the core nest egg continues to compound undisturbed. By integrating travel into the pursuit of FI rather than viewing it as a reward for the end of it, you create a life you don’t feel the need to escape from. This ensures that when you finally reach full independence, you already possess the global literacy to enjoy it. — James Tech, SEO Marketer, TripFrog
58% of Millennials and GenZ prioritize Travel over Material Accumulation
Financial Independence and travel are not mutually exclusive; in fact, they increasingly reinforce each other when approached strategically. A growing body of research highlights the rise of “geo-arbitrage,” where professionals leverage remote work or location flexibility to reduce living costs while continuing to explore new destinations.
According to a 2024 report by Deloitte, nearly 58% of Gen Z and millennials prioritize experiences like travel over material accumulation, reshaping traditional financial planning models. At the same time, the World Tourism Organization notes a steady increase in long-stay and work-from-anywhere travel patterns, indicating that travel is no longer viewed as a luxury pause but as an integrated lifestyle choice.
From a workforce perspective, continuous upskilling and digital proficiency — particularly in areas like project management, agile practices, and cybersecurity — enable professionals to maintain income streams while remaining location-independent.
Financial independence, therefore, is less about restriction and more about intentional design: aligning income strategies, skill development, and lifestyle priorities in a way that sustains both economic security and personal fulfillment. — Arvind Rongala, CEO, Invensis Learning
Renting RVs for Extended Travel Stretches
Absolutely yes: and I’ll tell you why from an angle most people overlook: your cost of living on the road can actually shrink dramatically while you’re building toward FI.
I run DFW RV Rentals, placing travel trailers for displaced families and insurance claims. What I see constantly is people discovering — often during the worst moments of their lives — that a well-equipped travel trailer is genuinely livable, comfortable, and cheap compared to a mortgage or apartment lease.
Here’s the FI angle nobody talks about: renting an RV for an extended travel stretch eliminates storage fees, maintenance headaches, depreciation, and insurance costs that crush RV owners. I’ve watched people romanticize ownership, buy a unit, and watch it become a financial anchor: whereas someone renting strategically keeps capital free and mobile.
If you’re pursuing FI and want travel woven in, think of RV rental as a variable living expense you control, not a lifestyle luxury. A few months on the road in a rented trailer can cost less than your fixed housing back home: and that gap is real money compounding toward independence. — Jonathan Dies, Owner, DFW RV Rentals
Maintenance-free Retirement communities
As Executive Director of The Village at Mint Spring and Stuarts Draft Retirement Community for over 16 years, I’ve guided hundreds toward maintenance-free retirement living that supports financial goals without homeownership burdens.
Yes, financial independence or semi-retirement pairs perfectly with travel when you eliminate upkeep costs like repairs, lawn care, snow removal, and property taxes: freeing budget and time for trips.
Our residents use the shuttle for local outings while traveling afar, knowing onsite care partners like Visiting Angels handle needs back home.
Fall incentives like up to $3,500 moving allowance make the shift easier, letting you lock in FI sooner and explore without stress. — David Brenneman, Owner, The Village at Mint Spring
Adopt a “Cash Rules Everything” mindset
As an advisor to business owners earning $400K+, I’ve found that financial independence is about aligning your strategy with your personal values rather than following generic industry models. I build plans for my clients that prioritize clarity and lifestyle flexibility, ensuring travel is a core component of the strategy rather than a sacrifice.
When the April 2025 market volatility caused equities to waver due to new tariffs, clients with high-liquidity strategies avoided the “dash for cash” and kept their travel plans intact. I focus on a “cash rules everything” mindset during periods of uncertainty to ensure market jitters don’t interrupt your personal milestones or global adventures.
I use the Altruist platform to give my clients a technology-driven, transparent view of their wealth from any location. This allows entrepreneurs to monitor their progress toward retirement and make confident decisions via mobile tools without being tethered to an office.
True financial guidance starts with understanding your long-term vision so your portfolio serves your life, not the other way around. By creating a practical action plan focused on stability and growth, you can pursue financial freedom while maintaining the lifestyle you have already worked to build. — Daniel Delaney, Owner, Seek & Find Financial
Make Travel a regular fixed expense you plan on incurring every month
Many people misunderstand the idea of being financially independent as a way to have nothing but austerity during their time of independence; however, the reality is that it’s just about allocating your money in a conscious manner. Too often, people will make travel an ‘additional’ expense that must be eliminated in order to achieve their savings goals: this can lead to burn out and a living arrangement that does not continue.
The problem is that travel is often treated as an item that has been paid for with ‘loose change’ after all of the other ‘necessary’ expenses have been paid each month; therefore when budgeting, travel should be included as a regular fixed expense you plan on incurring every month.
To have travel as part of your work-life balance, you will need to establish your savings plan with this in mind. Business places do this as well; you do not build a business just by lowering your cost structure, you have to build a company based on what gives you the highest return on your investment for the long-term. The same should be true for any travel related goal that you desire to achieve. One of the pitfalls that many individuals fall into when comparing their way of saving to the ways that people in the ‘lifestyle’ mode of saving demonstrate is that they fail to establish their own pace and their definition of ‘enough.’
Finding that work-life balance about not simply doing the math correctly, but making certain to build a lifestyle in which you would prefer to ‘Get up and do it!’ every single day. — Abhishek Pareek, Founder & Director, Coders.dev Continue Reading…
 Posted By
 Posted By