Building Wealth

For the first 30 or so years of working, saving and investing, you’ll be first in the mode of getting out of the hole (paying down debt), and then building your net worth (that’s wealth accumulation.). But don’t forget, wealth accumulation isn’t the ultimate goal. Decumulation is! (a separate category here at the Hub).

On the Middle Class & paying one’s fair share of taxes

By Tim Paziuk

Special to the Financial Independence Hub

The Liberal Government has stated it wants to build a strong middle class, but who comprises the middle class?  Mr. Morneau in his 2017 budget speech stated, “All Canadians must pay their fair share of taxes,” but what is a “fair share”?  Does fair share mean the total amount of taxes one pays as a percentage of their gross income?  Is this based on an annual consideration or a lifetime consideration?  Or does fair share mean positively contributing to the general revenue?

The answer to the first question is an ongoing contentious debate.  According to former Finance Minister Mr. Joe Oliver, the middle class could include households earning as much as $120,000.  Given research completed by MoneySense Magazine[1], the middle class could include households earning incomes ranging from $38,800 to $125,000 (average second, third, and fourth quintiles for Canadian households), but this varies considerably between Provinces and Territories, and even between cities.  But does owning a private corporation automatically exclude you from the middle class?  The continued witch hunt on private corporations by the Liberal Government would indicate this is the case since it directly contradicts their mandate to build a strong middle class.

Comparing a private-sector and public-sector worker

It is at this time I would like to introduce Sally.  Sally could be a physician or accountant, an engineer or architect, a therapist or life coach, or a hairstylist or clothing retailer.  Suffice to say that either out of choice or necessity, she is self employed.  Let’s make her a plumber who is in a position where it makes sense for her to incorporate because she can defer income within her corporation and income split with her spouse under present tax legislation.  Her spouse works part-time.  Their situation can be summarized as follows:

  • Sally’s taxable corporate income: $100,000
  • Spouse’s gross income: $25,000
  • Net income required to meet their lifestyle: $80,000
  • Spouse’s CPP income: $4,300

Continue Reading…

Making Canada great again

By Trevor Parry

Special to the Financial Independence Hub

I have to apologize to my CFL fan friends, particularly in Saskatchewan, where I have found it the rule rather than the exception to find a shrine to the fabled “Riders” in clear site in most offices.  The game just doesn’t do it for me.  The one, two punt monotony of the game isn’t overcome by the stoic resolution to play in Stalingrad like conditions on the Prairie in late fall.

With his second foray into Budget making, Finance Minister Bill Morneau’s attempt must be described as nothing more than a punt.  In this instance they have kicked away the ball to see what the offense south of the border will do.  For fiscal conservatives, who believe budgets should only go into deficit when faced with financial calamity, rather than to send the swag to the long list of Liberal sacred cows, pet projects and friendly consultants, this Budget was more of the same Keynesian dirge, although with veiled threats of further confiscation of wealth.  Certainly Prince Justin and LSE alumni Billy are taking marching orders from the reconstituted politburo to lay low and wait to see what The Donald can get through.

The Trump tax reform package, which despite the recent  (and what I am sure will be a temporary) hiccup in repealing and replacing Obamacare, will likely enjoy complete GOP support and support of Democrats concerned about re-election in 2018,  is the most ambitious tax plan to see the light of day since the days of Ronaldus Magnus.  It puts the Trudeauopian punitive “tax the hell out of everyone who wants to save 10 cents” dictum in definite jeopardy.  It would reduce all tax rates, including the top rate down to 33% from to 39.60%.

Canadian top tax rates kick in at just $200,000, half that of the US

Canadians should know that the top bracket in the US doesn’t kick in until you hit an income of US$418,000 as an individual, $470,700 if you file jointly and $444,550 if you file as a head of household with dependents.  Remember the Little Prince cancelled the miniscule Family Tax Cut ($2k) professing claims of “fairness”.  Canadian top rates kick in at C$200,000.

Continue Reading…

Don’t panic, Mom’s money is safe with an “advisor”

Toronto’s big banks: CBC puts focus on misleading job titles

“Integrity has no need of rules.” – Albert Camus

“If it is not right, do not do it.  If it is not true, do not say it .” – Marcus Aurelius

Words to live by, no?  Unfortunately, the financial services industry in Canada doesn’t tend to screen for existentialists and stoics.  I’d take Marcus Aurelius or Seneca as my financial advisor any day, even if they weren’t one of the rare advisors in Canada who are required by law to act in their clients’ best interest.

The headlines have been ablaze in the last few weeks with furor over alleged mis-selling at Canada’s banks.   Most recently, CBC’s Go Public investigators published a piece about misleading job titles:  a grand conspiracy perpetrated by the Canadian financial services industry in which the English language is manipulated to dupe unknowing consumers.  (See: ‘I feel duped’: Why bank employees with impressive but misleading titles could cost you big time)

“What’s in a vowel?”

Specifically, the authors suggest that by calling their employees “advisors” with an “o” instead of “advisers” with an “e”, banks are intentionally granting staff license to engage in all sorts of nefarious product mis-selling and conflicted behaviour.   Continue Reading…

Banks, Blockchain & Economic Liberty: A follow-up

By Adam Goldman

I wrote a piece last September titled ‘Why Our Economic Liberty Depends on the Blockchain’, providing an analysis on why I am certain distributed ledger technology is important to securing our rights under the law in the digital age.

In an ever-increasing realm of technology that is meant to improve (in positive ways) facets of our lives, the imperfection of humanity still exists while greed heavily plagues the banking world. As a firm advocate for the rule of law, I find recent revelations by CBC’s Go Public , that highlighted rampant fraudulent activity occurring amongst Canada’s largest financial institutions (TD, BMO, RBC, CIBC, and Scotiabank) disturbing to say the least.

‘This is why the only solution really is to have government step in and look after the Canadian people.’ says lobbyist Stan Buell as quoted in the CBC article.

Ultimately directives from above led to not only immoral, but also illegal tactics that chased their bottoms lines. Adding more bureaucracy at a government level will only exacerbate the climate.

Blockchain is the answer, not government

In my previous article I had given several broad examples of current institutions that could improve themselves, one being quasi-relevant to the financial fraud currently being exposed in Canada.

Continue Reading…

The 6 steps to Financial Independence

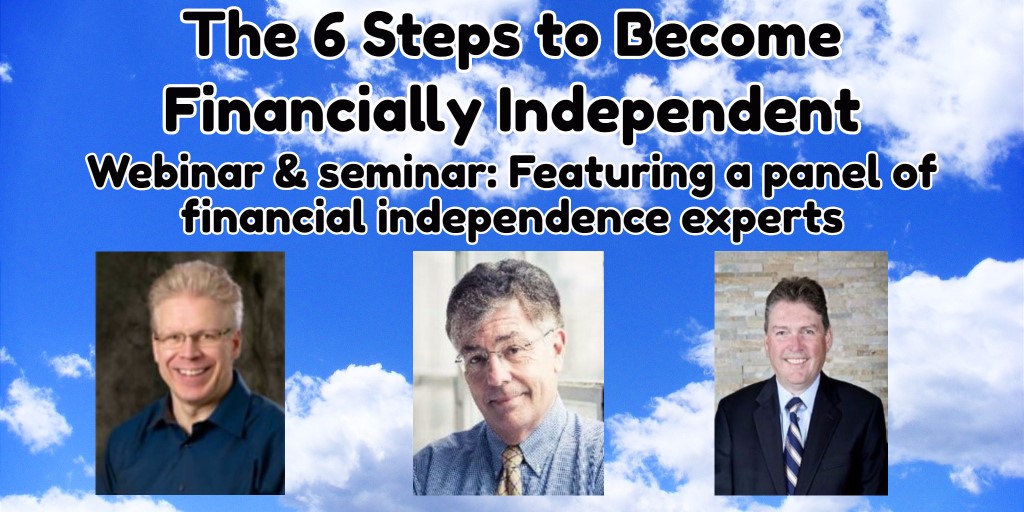
L to R: Ed Rempel, Jon Chevreau, Mike Drak

By Ed Rempel, CFP, CMA

Special to the Financial Independence Hub 

What is financial independence? How do you get there?

Financial independence means work is optional. You have enough money to live the way you want without having to earn money.

When you get there, life changes. You have freedom. You can do only what you enjoy or find meaningful.

If you don’t like your job or your boss, just quit. Your life is full of options. You can make the most of your own life.

When you get there, you can have a quiet confidence. You are financially secure.

Your plan should start with understanding your inner motivation and defining specifically the lifestyle you want to have once you are financially independent. It is your opportunity to determine your future.

Becoming financially independent requires planning and effort, but it is worthwhile to live a more fulfilling life. “It’s not about the money. It’s about your life.”

“Real freedom is financial freedom.” When is your Findependence Day?

Achieving financial independence is a very broad topic. Writing nearly 1,000 comprehensive, professional financial plans specifically for real Canadians has given me a deep insight into what really works.

Seminar in Toronto this Wednesday evening

Continue Reading…