All posts by Financial Independence Hub

5 things to consider when buying a new car

By Sia Hasan

Special to the Financial Independence Hub

It’s easy to buy a car without giving the purchase much thought. Every car dealer in town is ready to roll you off the lot in a brand new car today. If your credit score presents a problem, they’ve got a cheaper used model for you. Should your credit preclude that, there are any number of “buy here pay here” stores ready to roll you off the lot no matter what’s on your credit report.

But are you making a wise investment? People with lots of money got it by asking themselves that question before every purchase, be it a car, a house, or a hamburger. When it comes to a car, the answer to that question takes some research into the vehicle and a hard, truthful look at your financial situation.

If you are like most people, the first part of the answer is much easier to obtain. Ratings and reviews can tell you about the reliability, safety, and warranty. Armed with that information, it’s fairly easy to pick a car that’s not likely to cost you your left kidney. The second half of the equation requires putting the wishful thinking on the shelf and giving yourself an honest answer as to what you can afford.

Here are five important considerations when investing in a vehicle:

1.) Run the numbers

Before you even step onto a car lot or start reading the auto ads, know your budget. To figure this, add up the cost of all of your basic needs, like housing, utilities, food, cellphone, etc. Be sure to include the less basic but important needs, like saving for retirement, taking a vacation, saving for emergencies, going on a date, etc. Be honest with yourself. When you add in the cost of your new car, remember it’s not just the payment. How much it will cost for gas, insurance, maintenance, and repairs must also be included. Once you know what you can afford on a monthly basis, any number of online calculators can show what purchase price is in your range.

2.) Buy or lease

Most consumers are better off buying because they can gain equity in the car and eventually pay it off. With leases, the payments never end. The lease term expires and then you need another car. Also, mileage caps are restrictive and terms can be confusing. If you drive very little and don’t need the car for the long-term, leasing may make sense. Also, if you plan to drive a new car every two years, leasing may work better because, unless you’re a cash buyer, you’ll always have payments anyway.

3.) New or used

New cars drop a third of their value as soon as the proud new owner drives off the lot. Some of the best car deals out there are for 1- to 3-year-old cars. They’ve taken the initial depreciation but are still in good shape. Continue Reading…
Canadian Trade Relations: The wrong place at the wrong time

By Jeff Weniger, CFA, WisdomTree Investments  

Special to the Financial Independence Hub

The 24-year-old North American Free Trade Agreement (NAFTA) has never been this close to death, but a resolution could be behind the storm clouds.

Souring trade relations with the U.S. are a shame, because Canada got caught in the wrong place at the wrong time. Consider figure 1. President Donald Trump wants to make a dent in the US$388 billion annual trade deficit with China and, to a lesser extent, the yawning gaps with Mexico, Germany and Japan. But to show strength to them economically and North Korea militarily, he believes he has to treat even friendly actors such as Japan and Canada like hostile players. That became apparent when the U.S. administration imposed global steel and aluminum tariffs, and Canada wasn’t exempted.

Figure 1: Monthly U.S. Trade Deficit/Surplus (USD in Millions)

Monthly U.S. Trade Deficit/Surplus

Talks are starting to get personal, with U.S. President Donald Trump accusing Prime Minister Justin Trudeau of making false statements at a June news conference after G7 leaders met amicably. The Canadian leader then got relatively tough, responding that “Canadians … will not be pushed around.”

With the world’s two best friends in a lovers’ quarrel, the US$13 billion annual U.S.-Canadian trade gap, a rounding error, is somehow a political issue. It could have been resolved over golf.

But not all is lost. Ottawa would be wise to consider — if it is legal — scrapping NAFTA for a bilateral trade agreement with Washington.

Canada ill-advised to sit at table with Mexico

That’s because Canada is ill-advised to sit at the table with Mexico to try to strongarm the U.S. Not now, in 2018, given Mexico’s own specific troubles. Frankly, Mexico’s negotiating calculus is much weaker than Canada’s. The country went to the polls July 1, and leftist Andrés Manuel López Obrador (AMLO) won.  He won’t help Canada one bit because it isn’t politically palpable for him to shoot for a quick resolution. Hostility to the U.S. — or at least standing ground against Washington — has been a political winner for the Latin American “pink tide”1 for years. Playing the tough-talk game with Trump will be one of AMLO’s key rallying cries, and it can only cripple NAFTA. Continue Reading…

Staying on track financially: best practices

By Gloria Martinez

Special to the Financial Independence Hub

Many North Americans have trouble staying on track financially; there are so many things that can derail even the best-laid plans, from unexpected medical expenses to home repairs or a dip in credit.

However, there are some simple ways you can help keep your finances in check so you aren’t left with a nasty surprise down the road, and it will ensure that your retirement, college funds, or other savings are left untouched.

It’s important to start with a good plan. Sit down, look at your expenses and current income, and create a budget that will be easy to stick to. Don’t cut back on too many things at once; that’s a recipe for failure that will leave you feeling unmotivated to keep trying. It’s also a good idea to keep communication open with your spouse or partner so everyone is on the same page.

Read on below to find out the best ways to stay on track financially.

Buy a Life Insurance policy

The right life insurance policy isn’t just a way to protect your family in the event of your death; it’s also an investment that you can sell down the road should you need to free up cash. Many people do this in order to pad their nest egg a bit for retirement, but it’s important to find the right policy for your needs: both now and in the future.

Set a Budget

Setting a budget is essential when it comes to staying on track with your finances. Create a spreadsheet online that can be shared with your spouse or partner, and update it every day with each new purchase or checking deposit. It’s also a good idea to set an allowance for spending for the week and stick to it as closely as possible, whether it’s for groceries or eating out. You can look for ways to save, as well, such as carpooling, making eco-friendly changes to your home to reduce your utility bills, and trading cable for a streaming service. Continue Reading…

6 steps to avoiding a bear market near Retirement

By Fritz Gilbert, TheRetirementManifesto.com

Special to the Financial Independence Hub

Did you know a looming Bear Market Crisis is approaching?!

I just read it on the internet, so it’s got to be true!

To make matters worse, I just retired a month ago.

Uh Oh!  (Am I screwed?)

Today, some reality about Bear Markets, along with 6 steps to consider as you structure your retirement portfolio.

A Looming Bear Market

Ok, I’m having a bit of fun with the “read it on the internet” line, but the reality is that a Bear Market WILL happen. I’m not being prophetic, just stating the facts.  Since before the days of the tulip mania in 1637, bear markets have always been will us, and they always will.  We’ve benefited from a very nice bull run. We’re being naive if we think that it will never end.

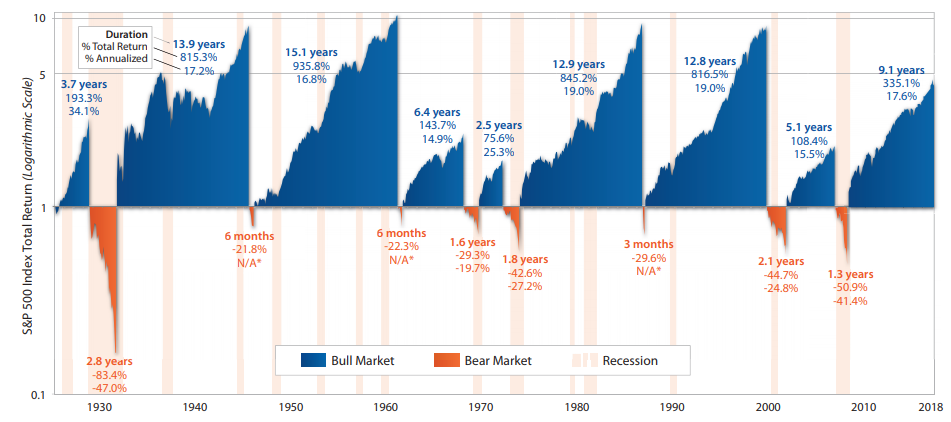
Since 1900, we’ve had 32 Bear Markets, defined as a correction of 20% or more.  Do the math, and that averages out to a Bear Market every 3.7 years.  The average bear market lasts 367 days (the longest was 34 months!). Here’s what they look like graphically:

The Looming Bear Market Will Drive A Retirement Crisis

I actually did read an article on the internet about the looming bear market crisis.  In “The Next Bear Market In Stocks Will Drive A Retirement Crisis,“ the author states:

“A recession could decimate even substantial retirement portfolios.”

Further, the author goes on to say that Social Security and Medicare, and the resulting increase in taxes, increase in eligibility age and reduction in benefits “would be a disaster” for those dependent on the safety net.

Add to that the Voices Of Worry over the global debt pile up and the underfunded status of many state & local pension funds and things could get really, really ugly.

Maybe I shouldn’t have retired early. 

Too late now, I guess I’d better get to work on building a Bear Market Crisis Prevention Plan.

The Looming Bear Market Crisis

We all know a Bear Market is coming. It’s been an increasing theme in the blogosphere, with even the esteemed Financial Samurai taking risk off the table. America’s wealthy are moving to cash.  Ben Carlson of A Wealth of Common Sense has 36 Obvious Investment Truths to remind folks that you should protect yourself.

I’m not a panic-driven investor, screaming a scare tactic headline to drive traffic (tho, if you’re reading this, I guess it worked, right?).  Rather, I’m reminding folks of the reality of how the markets work and encourage you to think about it as you develop your retirement portfolio strategy.  Yes, stocks have historically outperformed over the long-term, and will likely continue to do the same.  Just recognize that the road can be bumpy, and plan accordingly to avoid getting bitten by a bear when you can least afford it.

A Bear Market Crisis Contingency Plan

The reality is that bear markets have always been with us, and always will.  Unfortunately, we never know when that snake is going to strike, so it’s best to wear snakeproof boots along the path of retirement.  Following are some steps I’m taking, as an early retiree, to defend our portfolio against the risk of a bear attack.  View them as suggestions, and pick and choose as appropriate for your situation.

6 Steps To Bear Market Protection Continue Reading…

Oil pumping up returns for Canadian investors

By Neville Joanes

(Sponsor Content)

We don’t just use it to drive. It’s in the roads we drive on. In fact, it is used in over 6,000 products that help make up modern life. “Oil,that is. Black gold. Texas tea …” And for a fossil fuel commodity supposedly going the way of the dinosaur, oil is looking pretty slick these days.

Oil hit $73 recently and then moderated down to a sweet spot in the mid-$60 range. But can $100 oil really be on its way down the pipeline? Spoiler alert: you might not be thinking big enough. $100 is just a number, not a cap.

As an example of the importance of oil to the Canadian scene, let’s look at the Horizons S&P/TSX 60 Index ETF, which holds the top 60 companies on the S&P 500 index as well as the Toronto Stock Exchange. (WealthBar holds HXT because it is an efficient way to have exposure to Canadian companies or businesses in our clients’ portfolios.) A significant number of those companies are energy producers (ie. oil companies). Indeed, on the TSX, nearly one fifth of the stocks represent energy companies.

Their success fuelled a bounce to a record high in late June. Oil is back — and that means Canadian investors (or at the very least, investors in Canada’s oil-fuelled economy), a steady pipeline of profits is bubbling up.

The recent history of oil. Before the boom, the bust

If you filled up your car recently, the dog days of oil might seem like a distant memory. But it wasn’t that long ago. Thanks to a glut of supply on the world market, oil was down at $30/barrel in 2016. How did it get so low? Mostly, fracking.

North American energy companies employed new technology techniques to bump up energy production by exploiting fields formerly deemed uneconomical. This reduced the need for importing oil from abroad.

The world did not adjust, at least not right away. Russia and the OPEC countries are addicted to revenues from exported oil. With few alternatives as a revenue pipeline, these nations had continued to pump oil even as the price was clearly sliding. Soon, the world had an ocean of cheap oil on its hands.

Moving forward to the dog days of August 2017 and that glut was still choking down the price per barrel. Note the final bolded conclusion in this Bloomberg article:

When OPEC and Russia first embarked on their strategy to clear a global oil glut, it was expected to succeed within six months. It now looks like the battle could last for years.

The Organization of Petroleum Exporting Countries and its partners plan to wrap up their production cuts next spring, already nine months later than originally expected. Yet oil prices are faltering again as data from the International Energy Agency show world inventories could remain oversupplied even after the end of 2018. ESAI Energy LLC predicts that, rather than months, draining the surplus may take years.

With oil priced so low, North American energy companies struggled to keep pumping. At the height of the crash, tens of thousands of Canadians, mostly in Alberta, lost high-paying jobs. By 2017, our Prime Minister was even talking about phasing out the oil sands.

But predictions of oil’s demise were premature.

Oil slides back from the brink

The rebound in oil happened a lot quicker than the experts expected. Today, it is welling up past $70/barrel. What happened? Supply met demand. Continue Reading…