All posts by Financial Independence Hub

Are you prepared for the new Income Tax rules for Private Corporations?

By John Fisher

Special to the Financial Independence Hub

As many of you are aware, the Canadian government announced new rules in February concerning the taxation of passive income in Canadian controlled private corporations (CCPCs).

The Liberals’ original draft legislation proposed to target tax strategies that have been used by small businesses and professionals since the early 1970s, so naturally the initial announcement in July 2017 drew widespread condemnation.

The government’s concern with the accumulation of passive income-generating investments in private companies stems from the fact that CCPCs pay a blended federal and provincial small business tax rate of 13.5% (in Ontario) on active business income up to the small business deduction (SBD) limit of $500,000 in 2018. This compares favorably to the tax rates on income earned by individuals. On a combined federal and provincial basis, the differential between the highest marginal tax rate on personal income and the small business tax rate ranges between about 36% and 41%, depending on the province in which a CCPC resides.

As a result of this tax rate differential, owners of a CCPC are almost always better off retaining corporate earnings and investing within their corporation. While a similar amount of combined corporate and personal tax is ultimately paid by business owners when monies are withdrawn through dividends, taxes can be deferred until such time as the money is required personally. This effectively allows business owners to temporarily obtain the benefit of investing a larger amount of money than would otherwise be available if they earned the money personally or immediately withdrew profits from their corporation.

One side note worth highlighting here: it is a common misconception that passive investment income earned within a corporation can be taxed at the lower small business tax rate. This is incorrect, as passive income is generally taxed at about the same rate (over 50%), whether earned inside or outside a corporation; so there is no real benefit, per se, from earning investment income in a corporation. Rather, the advantage is that the corporate entrepreneur is able to temporarily invest the amount of taxes deferred by delaying the withdrawal of funds from his/her company.

So what are the new rules governing passive income?

The government has announced its intention to introduce legislation that will reduce the SBD limit by $5 for every $1 of investment income above a $50,000 threshold, beginning in 2019. Once passive investment income exceeds $150,000, the SBD limit will be reduced to zero and the CCPC will pay tax at the general corporate tax rate of 26.5% as opposed to the 13.5% SBD Rate (for Ontario CCPCs).

The $50,000 threshold applies to passive income earned on both legacy and new investments which is important to note given the government’s original promise to “grandfather” any passive income earned from investments previously accumulated

How will the rules affect you as an owner of a CCPC?

Many entrepreneurs are asking if the new rules will result in them paying additional taxes if their corporations generate passive income in excess of $50,000. In most circumstances, the answer is that they will pay more corporate taxes, thereby reducing the size of their tax deferral advantage (from 40% down to 27% on their 2019 corporate income earned in Ontario).

The loss of the entire SBD limit would cost an Ontario CCPC about $65,000 in additional annual corporate taxes ($500,000 x 13% increase in the corporate tax rate). However, once income is paid out by way of dividends from the CCPC, the analysis we have reviewed suggests that the combined personal and corporate tax burden will increase by only about 1% as compared to the current tax regime.

What can you do in light of the proposed changes? Continue Reading…
Is typical retirement advice good? – Testing popular Retirement rules of thumb

Special to the Financial Independence Hub 

You want to retire soon. How should you set up your retirement income?

You talk with some friends, read about it on the internet, and talk with a financial advisor. Are you actually getting good advice?

When it comes to retirement income, most financial advisors rely on a few rules of thumb handed down from one generation of advisors to the next. The rules appear to be common sense and are usually accepted without question.

Do these rules of thumb actually work?

Before giving clients this advice, I tested them with 150 years’ history of stocks, bonds and inflation. I wanted to see if these rules were reliable for a typical 30-year retirement. (The average retirement age is 62. In 50% of couples that reach their 60s, one of them makes it to age 92.) 

These five rules are the “conventional wisdom” – the advice typically given to seniors:

  1. “4% Rule”: You can safely withdraw 4% of your investments and increase it by inflation for the rest of your life. For example, $40,000 per year from a $1 million portfolio.
  2. “Age Rule”: Your age is the percentage of bonds you should have. For example, at age 70, you should have 70% in bonds and 30% in stocks.
  3. “Sequence of returns”: Invest conservatively because you can’t afford to take a loss. You can run out of money because of the “sequence of returns.” You can’t recover from investment losses early in your retirement.
  4. Don’t touch your principal. Try to live off the interest.
  5. Cash buffer: Keep cash equal to 2 years’ income to draw on when your investments are down.

The results: NONE of these rules of thumb are reliable, based on history.

Let’s look at each to understand this.

1.) “4% Rule”: Can you safely withdraw 4% of your investments plus inflation for the rest of your life?

Based on history, the “4% Rule” was safe for equity-focused investors, but not for most seniors.

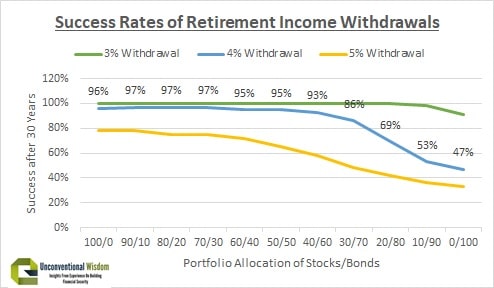
In the results shown in the graphic at the top of this blog, the blue line is the “4% Rule,” showing how often in the last 150 years a 4% withdrawal plus inflation provided a reliable income for 30 years.

The “4% Rule” only works with at least 50% in stocks.

The “4% Rule” worked only if you invest with a minimum of 50% in stocks. Even safer is 70-100% in stocks. It is best to avoid a success rate below 95% or 97%. They mean a 1 in 20 or 1 in 30 chance of running out of money during your retirement.

Most seniors invest more conservatively than this and the 4% Rule failed miserably for them.

A “3% Rule” has been reliable in history, but means you only get $30,000 per year plus inflation from a $1 million portfolio, instead of $40,000 per year.

These results are counter-intuitive. The more you invest in stocks, the safer your retirement income would have been in history.

To understand this, it is important to understand that stocks are risky short-term, but reliable long-term. Bonds are reliable short-term, but risky long-term. Why? Bonds get killed by inflation or rising interest rates. If either happens during your retirement, you can easily run out of money with bonds.

The chart below illustrates this clearly. It shows the standard deviation (measure of risk) of stocks, bonds and cash over various time periods in the last 200 years. Note that stocks are much riskier short-term, but actually lower risk for periods of time longer than 20 years.

Stocks are more reliable after inflation than bonds after 20 years.

Ed’s advice: Replace the “4% Rule” with “2.5% +.2% for every 10% in stocks Rule.”  For example, with 10% in stocks, use a “2.7% Rule.” If you invest 70% or more in stocks, then the “4% Rule is safe.

2.) “Age Rule”: Your age is the percentage of bonds you should have. For example, at age 70, you should have 70% in bonds and 30% in stocks.

Continue Reading…

Affordable Housing: Which Toronto neighbourhoods are friendliest for Condo buyers?

By Penelope Graham, Zoocasa

Special to the Financial Independence Hub

There’s no denying Toronto real estate prices have tumbled since the Fair Housing Plan was introduced by the Ontario government last April, to address the searing 33-per-cent year-over-year price growth that alarmed buyers and policymakers alike. Detached house prices – the hardest hit segment following the Plan – have since declined 14.8 per cent, representing a dollar loss of $180,878, while the average aggregate home price is down 11.8 per cent, a loss of $108,696.

However, affordability continues to be a keenly-felt issue in the city, especially among what is supposed to be the affordable entry point for new home buyers: condos.

While the priciest home segments posted deep declines in the volatile months following the Plan, condos consistently posted year-over-year gains in value; now, just over a 15 months later, they’re sitting at an average of $561,097, an increase of 8.1 per cent.

FHP did little for first-time buyers

That means that, while those in the move-up markets have enjoyed improved buyer conditions, the most vulnerable and cash-strapped have faced only worsening affordability following the new policies. Rather than find an affordable entry-hold in the 416, first-timers are increasingly drawn to further-flung communities, such as homes for sale in London, Ontario, or even Ottawa real estate, where detached living can be had at the fraction of the cost for a city condo.

However, these are aggregate data, reflecting home prices collected from the entire region monitored by the Toronto Real Estate Board. As real estate is extremely local, and can differ from neighbourhood to neighbourhood, savvy condo buyers seeking a deal may still have options within the City of Toronto proper.

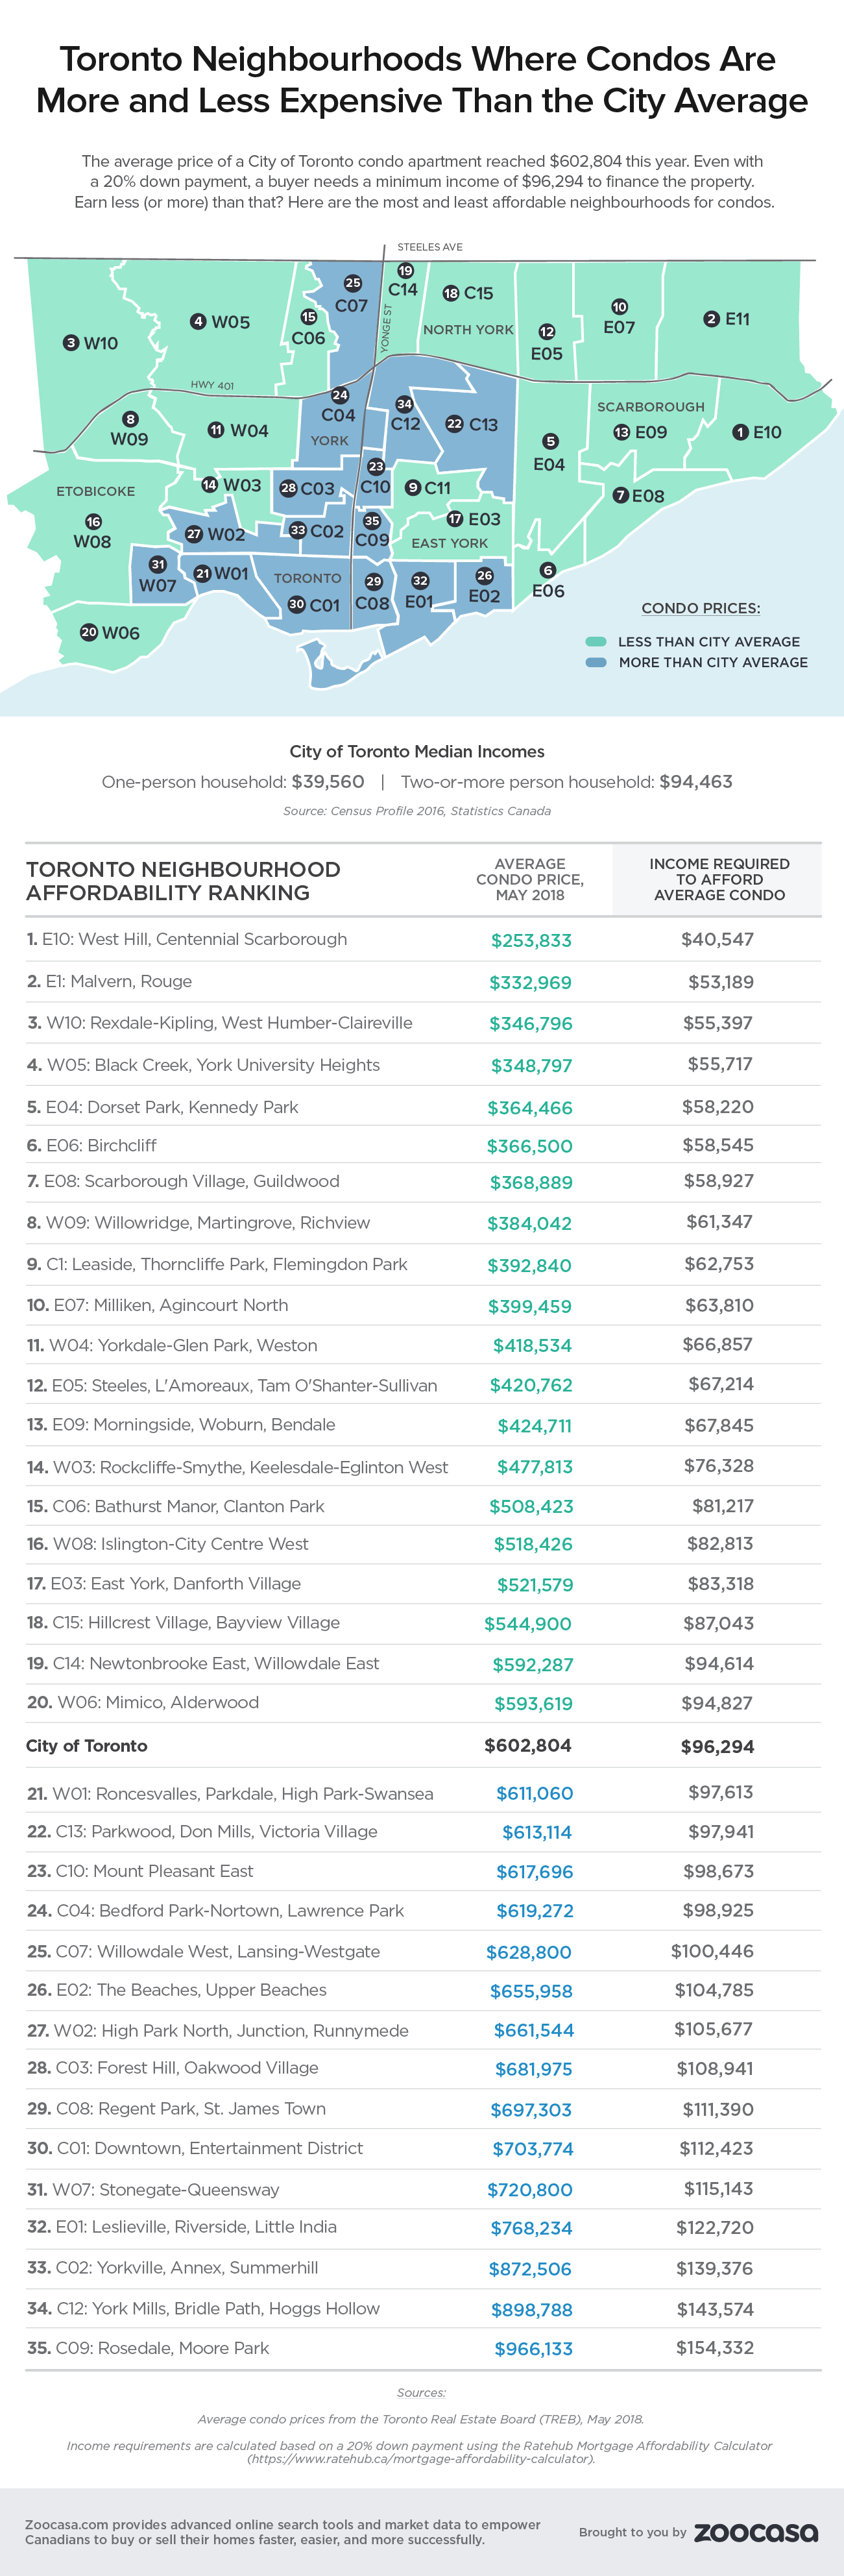
Toronto’s most affordable Condo communities

To identify where this is possible, Zoocasa crunched the affordability numbers per neighbourhood, factoring in the average price in each as well as the median income earned in Toronto households.

The findings revealed that, for households earning two or more incomes at the median of $96,294, 18 of the 35 examined markets remained within the realm of affordability.  They are:

Continue Reading…

The Case for Financial Assets over real estate

Billy kicking back on Mexico’s Pacific Coast

By Billy Kaderli

Special to the Financial Independence Hub

When I was a stock broker in California — one of the hottest housing markets in the US — real-estate was my competition. “Everyone” was making money in real-estate, so why would they invest in the stock market?

I needed an angle

I went to the Board of Realtors and got prices for 2-, 3- and 4-bedroom homes in the area, both at the current price and for 10 years prior. I did the math to calculate what annual return these houses were creating for that ten-year span, then compared that to the S&P 500 Index for the same time period.

The index clearly beat all three home styles without the hassles of ownership. Now I had my argument to help people invest in the market.

Ok, that was then and this is now

Using Zillow.com I looked up what the home we used to own was now worth. It was listed at US$862K. Again I did the math and found that over the last 31 years since we bought it, that house has appreciated 6.4% annually. Sounds OK, except that there were property taxes, maintenance and repairs that would need to be deducted lowering that annual return.

Then, I wondered, what if we had put the money to buy our home into the S&P 500? So I calculated that figure also.

Are you ready?

It would be worth 3 million (US) dollars today! Over three times the current value of the home, as the Index produced a 10.46% annual return during those 31 years. Continue Reading…

Why the “T” in TSX should stand for Tokyo

By Jeff Weniger, CFA, WisdomTree Investments

Special to the Financial Independence Hub


Canada’s stock market construction may be more than just a portfolio risk; it is arguably a systemic one.

If, for whatever reason, the Canadian financial system were to encounter serious difficulty, investors would be hit by a one-two punch. The attendant economic weakness would hang over the stock market, and it would be the very companies that dominate the stock market that would be battling demons. Canada’s top-heaviness, where more than $2 of every $5 in the MSCI Canada Index is in financial stocks, is not normal or reassuring for a developed economy.1 We should stop making like it is.

In fact, it would be better for the TSX if the “T” stood for Tokyo, at least on the sector diversification side of things, as we show below.

Stuck in the mud

Everywhere you turn, countries that are top heavy are doing something about it. Saudi Arabia, for example, sees the writing on the wall for fossil fuels; either the price mechanism may cause a phase-down in oil demand in the next quarter century, or environmental action groups will crush demand themselves. Either way, the ruling Crown Prince Mohammad bin Salman is keen to avoid state failure if a bleak future for oil comes to pass. That country will soon float an IPO of Aramco, the state-run oil behemoth that may be equal to several ExxonMobils. Proceeds will be diverted into tech, infrastructure—anything that isn’t oil.

China, too, realized it was turning into a one-trick pony. After building its export machine after Mao’s death, the time for middle-class demand eventually arrived. When it joined the WTO at the turn of the century, the country’s household consumption was 46% of GDP. It fell to 36% of GDP in 2007, but it has been rising ever since; sights are set on 40% this year.2

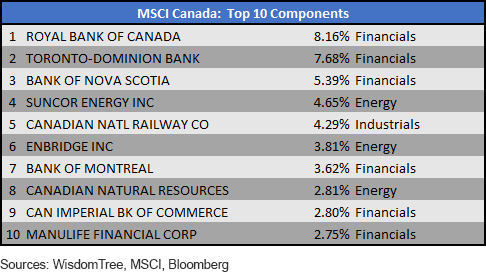
But not Canada. The hat is hung on the same two sectors, as always. Nine of this country’s top 10 corporations by market capitalization fit the bill (figure 1). This, in a country where the average investor has 86% of assets inside these borders.3

That is concentration on top of concentration.

Figure 1: Canada’s Sector Concentrations

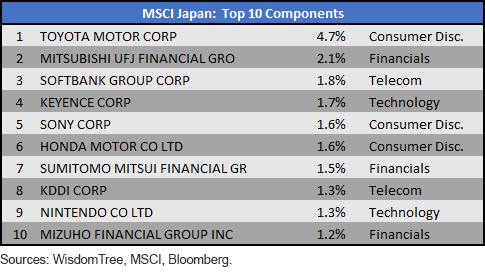
Compare the “T” for Toronto with another T: Tokyo. Figure 2 shows Japan’s national champions. They don’t dominate allocations quite like Canada’s do.

Figure 2: Japan’s Largest Companies

Continue Reading…

Powered by the Financial Independence Hub.
© 2013-2026 All Rights Reserved.
Financial Independence Hub Logo

Sign up for our Daily Digest E-Mail!

Get daily updates from the FindependenceHub.com straight to your inbox.