All posts by Financial Independence Hub

Why Sean Cooper quit his full-time job after 8 years

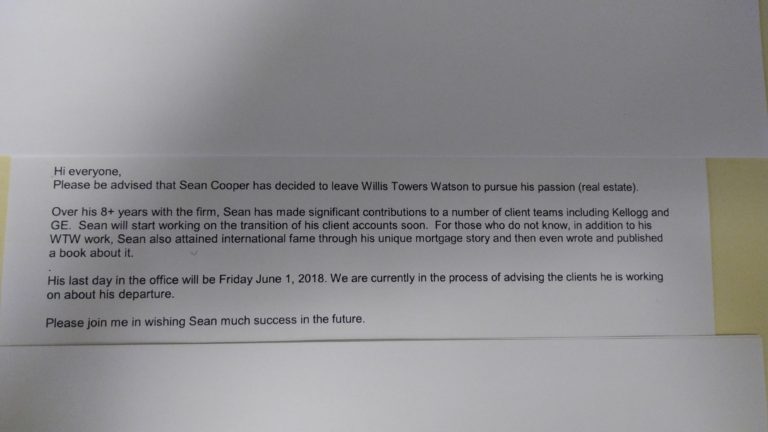
What a thoughtful goodbye email. Gosh, it’s hard to keep a secret! I guess everyone knows about my mortgage burning story, even my colleagues at work!


By Sean Cooper

Special to the Financial Independence Hub

If you follow me on Instagram, you may have already heard the big news. After 8 years, I’m quitting my full-time job at the pension consulting firm. I gave my employer plenty of notice. I handed in my resignation 2 months ahead of time. June 1st will be my last day in the office. To celebrate this big career milestone, I’ve booked a weeklong trip to New York City and Boston.

I always planned to quit my full-time job. I just didn’t think it would happen so soon. I’m at a crossroads in my life. I’m 33 years old and not getting any younger. It’s time to make some tough “adult” decisions. I can either take the easy road and keep working for a company where I’m comfortable, or take the hard road and become a full-time entrepreneur. I chose the latter.

Keeping a promise to myself

A promise I made to myself after I burned my mortgage in September 2015 is that I’d slow down and get a better work-life balance. Unfortunately, that just wasn’t happening.

I’m someone who’s super ambitious. So, 6 weeks after burning my mortgage papers, I started writing a book. With the success of my book and speaking career, I’m finding myself busier than ever. I’m probably working harder now than when I was paying down my mortgage (no joke).

I’m still putting in the 80+ hour workweeks, waking up at 6:30AM and working until midnight or 1AM most days – and for what? I’m mortgage-free. I don’t have to work this many hours, but the problem is I love what I do. I enjoy my side hustle as a personal finance journalist, money coach and speaker more than my full-time job. I couldn’t keep working at this insane pace forever. I was tired all the time. Something had to give.

So with mixed emotions, in early April I made the difficult decision of choosing my budding career as a personal finance expert over my full-time career. It wasn’t an easy choice, but I was ready to make the jump.

Taking a risk

This was probably the most difficult decision I’ve ever had to make. It wasn’t easy to walk away from a steady, full-time job with benefits and a defined benefit pension plan. It was especially difficult for someone as risk adverse as me (I did after all pay off my mortgage in record timing in 3 years).

When I shared the big news with those closest to me – friends, family and coworkers – I didn’t know what to expect. Thankfully everyone has been supportive of my decision. Saying goodbye to my coworkers will be especially tough. My coworkers are like family to me. They were there when I burned my mortgage and launched my book.

It’s going to take me a while to get up and running. Luckily I have time and money. My house is paid off. I also (still) rent out the main floor of my house. The rental income alone can support me. I also have savings to last me for the years to come.

From a personal standpoint, it helps that things are less complicated. I’m single (I’m half joking when I say I’m still looking for a frugal girlfriend). I don’t have a spouse or children to look after. (Although this is a double-edged sword since I don’t have a spouse’s income to rely on either.) I’d probably hesitate to do the same thing if my circumstances were different and I was married with children.

You’ll never get rich working for someone else
Continue Reading…

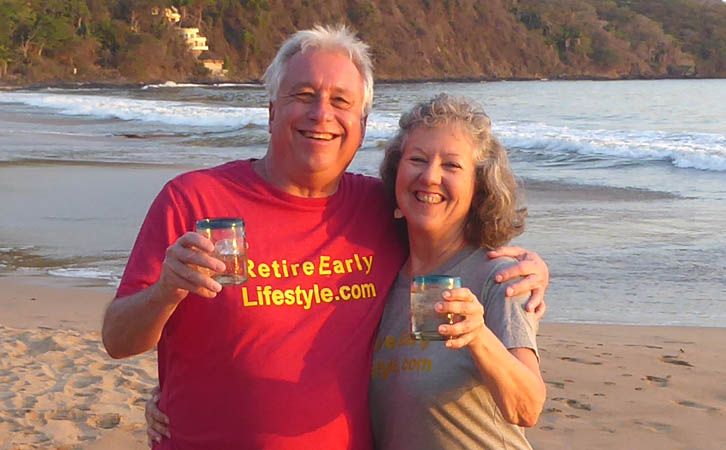
10,000 days of Findependence (Financial Independence)

By Billy and Akaisha Kaderli

Special to the Financial Independence Hub

Wow! We made it!

Ten thousand days of financial independence!

Now into our 28th year, we just passed the 10,000-day milestone. And all the while our net worth has grown: above inflation and spending. We have been financially independent longer than some of our readers have been alive! Think about that!

Do you know what this is? This is unbridled success!

No one thought we could do this, and many told us we’d fail.

And we have always said that if WE could do this, YOU could too!

In the beginning

It was January, 1991 that we traded our briefcases for backpacks and we haven’t looked back. We were 38 years of age when we ventured into uncharted waters for the great unknown. That sounds dramatic, but it’s true.

At the time there was no internet, no Google, no social media or Youtube, few ATM’s and – with little guidance – we left our secure jobs for a lifestyle of adventure and experiences. We wanted something different for ourselves than what traditional thinking offered.

There was no word for what we were planning to do. In fact, the road we were taking was a barely visible, unmarked trail. Some people thought we were crazy to put our financial and social lives in danger like this. Others just looked at us with pity, “knowing” we’d be back in a few months from our vacation with our tails between our legs, begging for re-entry into the world that we seemed so willing to chuck for the sake of adventure.

But we weren’t designing their dream, we were creating ours. And, after all these years of world travel, we are still here (and with a stronger portfolio! Do you ever hear THAT from the financial pundits?)

Overcoming challenges and moving into the future

The most difficult part of this adventure was that there was no support system in place for “professional vagabonds.” The word “Location Independent Living” hadn’t been invented yet, nor had email, electronic bank transfers, safe withdrawal rates, downloadable books or music.

That was almost three decades ago (seems almost primitive, doesn’t it?), and today the choice to become financially independent and live a lifestyle of travel is So. Much. Easier.

To stay in touch with family and friends, we utilize email, Skype and social media. Our photos are digital and are kept on a hard drive or up in the cloud. Ninety-nine percent of our bills and financial transactions are done online with the click of a key. The snail mail we do get is handled through a mail service. We can get our news in an instant with 24/7 worldwide coverage. We download movies, take online courses, and order music or books from Amazon or from hundreds of businesses who offer what we are looking for.

Things have changed a LOT over the last 3 decades and digital nomads are everywhere.

Freedom was our motivation

While there are many ways to live a life, and we aren’t criticizing anyone’s choice, for us, Freedom was our motivation. Continue Reading…

How to develop a Financial Independence mindset if your parents were reckless spenders

By Alex Lawson

Special to the Financial Independence Hub

Our parents are our first teachers. We learn our values, our habits, life skills, relationship skills, and many other things from our parents, long before we venture out on our own.

One of the things that people pick up on is financial habits, good or bad. If your parents were reckless spenders, chances are you’re already headed down the same path. The good news is that it’s possible to change your mindset and learn to manage your finances so that you don’t make the same mistakes they did.

Separate yourself from them

The first thing you need to do is realize that you are your own person capable of making your own choices. Don’t tell yourself you’re irresponsible with money just because that’s how you grew up. Make the decision to be different and start telling yourself the opposite. Reinforce the idea that you can be financially responsible and independent regardless of how you grew up, and you’ll be able to start making better choices.

Decide on your goals

Many people that had financially irresponsible parents have never been taught to think about the future. Planning for retirement should begin as soon as you leave college. Do you think you’ll want to retire with enough money to live comfortably as you have been, or are you planning on securing complete financial independence by the time you’re 30? The process for saving and investing will be completely different based on your goals. Begin saving aggressively when you’re young so that your money will have more time to grow.

Make saving a priority

If your parents were reckless spenders, they probably didn’t teach you anything about saving. One of the biggest keys to financial independence is learning how to save properly, so that you can be prepared for both unexpected problems and for your future. Build savings into your budget before you even look at what type of housing you can afford. A good rule is to start saving 10% of every paycheck and live off what is left over until you reach the goal of three times your monthly income. Then, when your car breaks down or if you lose your job, you will have an emergency fund to rely on without having to go into debt. Continue Reading…

The 7 most common trading mistakes

By Alana Downer

Special to the Financial Independence Hub

With the ever-increasing popularity in trading, be it stocks, Forex or cryptocurrency, more and more people are becoming involved. Some are getting rich while others find themselves learning the hard way. Of course, beginner mistakes are almost inevitable when a new trader enters the market, but with some research and careful planning, some mistakes can easily be avoided. Here are seven of the most common trading mistakes you should recognise and avoid in 2018.


1.) Catch a falling knife

As a new trader, a common mistake is thinking that a dip has run its course. A common mentality, especially in crypto trading is to “buy the dip,” however just because an asset is cheap, be it stock, a forex trade or cryptocurrency, doesn’t mean it can’t get cheaper. Many people buy in, anticipating a reversal, only to see the price drop further.

It’s much better to have a “price confirmation” approach, where you wait for the market to reverse before you enter. To do this effectively, you need something that can be objectively defined such as a price moving above an average or the completion of a head and shoulder pattern.

2.) Holding on to losing trades

Another popular crypto mentality is to “Hodl”, which is simply a misspelling of hold. This isn’t exclusive to crypto, however, and most new traders have likely lost money this way. A trade going against you, especially as a new trader, never feels good and instead of getting rid of it, as you may have planned, you hold on to it, hoping it will reverse.

One simple tactic to avoid hanging on to a losing trade is to ask yourself “would I enter this trade today, at this level?” If the answer is no, it’s probably best to get rid of it.

3.) Listening to hot tips or FUD

The internet, your friends and your family may be full of advice and “hot tips.” Trade recommendations for all markets can be found everywhere. The rumours might be right, or they might be horribly wrong but it’s important to remember they’re just rumours. Do your own research, and decide if it’s something you agree with. At the end of the day you’re trading with your own money, so your choices need to be your own.

Similarly, there can be a lot of fear, uncertainty and doubt (FUD) floating around in today’s climate of viral and fake news. Again, do your own research and learn as much as you can about any recommendations you are following.

4.) Taking uncomfortable risks Continue Reading…

7 steps to Financial Independence

By Laura Martins

Special to the Financial Independence Hub

Financial Independence (aka “Findependence”) is something that many of us are working towards, but which very few actually achieve. Having a high-paying job alone does not guarantee financial independence. While making more money does make Findependence easier to achieve, the important thing to focus on is what you do with your money, rather than how much you earn.

It’s also important to understand that financial independence will take time and planning. With the right goals and steps in place, Findependence can be achieved, but it’s important to be persistent and patient.

In most cases, financial independence doesn’t mean you won’t work ever again, but it brings freedom so you can enjoy your life and work on the things that matter to you. Here are seven key steps to develop financial independence.

1.) Get to know your money

Before you can begin to work on your financial independence, it’s imperative that you know exactly what your money is doing. You must know how much is coming in, and how much and where you are spending it.

Develop a habit of checking your bank account. Ignoring it is one of the fastest ways to lose track and lose money. It might seem obvious, but developing financial independence means spending less than you earn.

Spend a few weeks or months tracking your finances and create a budget. It’s important that it’s realistic so you can stick to it.

2.) Remove non-essentials

Once you understand your finances, it’s time to find the areas where you can save more. This is one of the hardest parts on the journey to financial independence, but also one of the most important steps.

Look at your spending and assess what you don’t need. In other words, you should try to minimize your non-essential expenses. That might mean cancelling your gym membership, reducing the amount of streaming services you pay for or making more meals at home. While these things might seem small, they will all add up, and after a few months it might make a noticeable difference to your bank account.

3.) Increase your income

Now that you understand your finances and have your spending under control, it’s time to start saving more. Continue Reading…