All posts by Financial Independence Hub

What the first week of Retirement is really like

By Fritz Gilbert, RetirementManifesto.com

Special to the Financial Independence Hub

I have no idea why I’m fascinated by the “First Week Of Retirement,” and I’m curious if others also wonder about it? I suspect many do and dedicate this post to those of you who wonder what the first week of retirement is really like.

Now that I’m living the first week of retirement, how would I describe it? Is it what I thought it’d be, or is it different? Is it a big deal, or just another week? Is it weird, or normal? Is it scary, or exciting?

Yes to all of that. And no to all of that.

What does Retirement taste like?

Have you ever tried to explain what something tastes like? Let’s go with chocolate, as an example. How would you describe it? What words would you use? Describing the first week of retirement is like describing the taste of chocolate. It’s really good, but it’s hard to describe.

Yeah, the first week of retirement is alot like that.

It’s good, but I can’t think of the right words to describe it. Regardless, today we’re going to try.

What the first week of Retirement is really like

Is It Like Taking A Vacation?
A Vacation In Norway. Is it like that?

As I write these words, I’m 5 days into my retirement (a true rookie). Is the first week of retirement like being on vacation? On one hand, kinda sorta, but that falls far short of describing the reality. It’s similar in that you’re off work for a few days, but it’s very, very different in the knowledge that You’re Never Going Back To Work.is


A Vacation that never ends will always feel different than a two-week vacation. Full Stop. So, imagine the first half of your vacation, where you’re all pumped up and excited. But you know it lasts for the rest of your life. Yeah, it’s more like that.

Only different.

I love swimming in my local mountain lake.

Is it like Saturday every day?

With less than a week of retirement under my belt, the “Saturday” analogy seems to be a better description of what the first week of retirement is really like. Like the Saturday’s you’ve experienced for decades, you’re free to do what you want to do. You’re ok letting your email go unchecked for a day or two. You can stay up later, you can sleep in.

You’ve got time to head up to the lake for that swim.

But it’s different because you know that there’s no Monday looming on the horizon.

What’s chocolate taste like?

Yeah, it’s hard to describe.

Is it scary, or exciting?

I had a friend ask me if I was “scared.” I answered that I was 98% excited and 2% scared. Sure, there’s some apprehension, but it’s a really small piece of my mindset in Week 1. At this stage of the game, I’m just learning my way around this thing called retirement, and enjoying the sensation of the very first Tastes Of Freedom I’ve worked so hard to earn. It’s only scary if you make it scary.

I know we’ll travel through many phases during our retirement journey, and I’m sure some will be more “scary” than others. We’re planning to take it all in stride. One day at a time, with some thoughts on where we want this thing to lead while leaving some freedom to enjoy the Serendipity of the thing.
You can choose what you want your retirement to be. Don’t choose scary. Life’s too short.

Choose the attitude with which you’ll live your life.

I’m choosing excited (and yeah, just a wee bit scared). Continue Reading…
How do Canadians feel about the new Real Estate regulations?

By Penelope Graham, Zoocasa

Special to the Financial Independence Hub

The anniversary of the implementation of the Ontario Fair Housing Plan has come and gone, and the playing field is just starting to even in the province’s housing market. Designed to cool demand and price growth in the Greater Golden Horseshoe, the 16-part package of housing regulations has effectively done just that, with sales down double-digit percentages throughout the region, and prices softening for the most expensive housing types.

Housing analysts argue that this result is mainly due to psychological factors, rather than the new regulations – which include a foreign buyer’s tax, and overarching rent controls – themselves.

But what do Ontarians really think about the new regulations? To find out, Zoocasa conducted a survey of 1,400 respondents on their sentiments around the highlights of the plan, and whether they support the government’s intervention in the free housing market.

Following BC’s footsteps

If Ontario’s attempt to tax foreign purchasers of real estate seems familiar, that’s because it closely resembles what occurred in British Columbia; the province initially implemented a 15-per-cent levy on foreign buyers within the Metro Vancouver area in August 2016, before upping the tax to a full 20 per cent, and extending the affected geographical area, in February of this year.

While Ontario’s version, called the Non-Resident Speculation Tax (NRST) still taxes just 15 per cent of a home’s purchase price, it will apply to anyone buying a home within the GGH – including homes for sale in Hamilton, or condos for sale in Mississauga, who is not a Canadian citizen or permanent resident (those who obtain such status, or who are enrolled in a minimum two-year full-time post-secondary program within a year of their home purchase are eligible for a full rebate on the NRST).

At the time of its implementation, former Ontario premier Kathleen Wynne was adamant that the tax was not intended to discourage newcomers to Canada from settling in Ontario.

“The Non-Resident Speculation Tax has nothing to do with new Canadians or people who want to make Ontario their home,” she stated to a media scrum on April 20, 2017. “This is targeting people who are not looking to raise a family, who are just looking for quick profit or a place to park their money.”

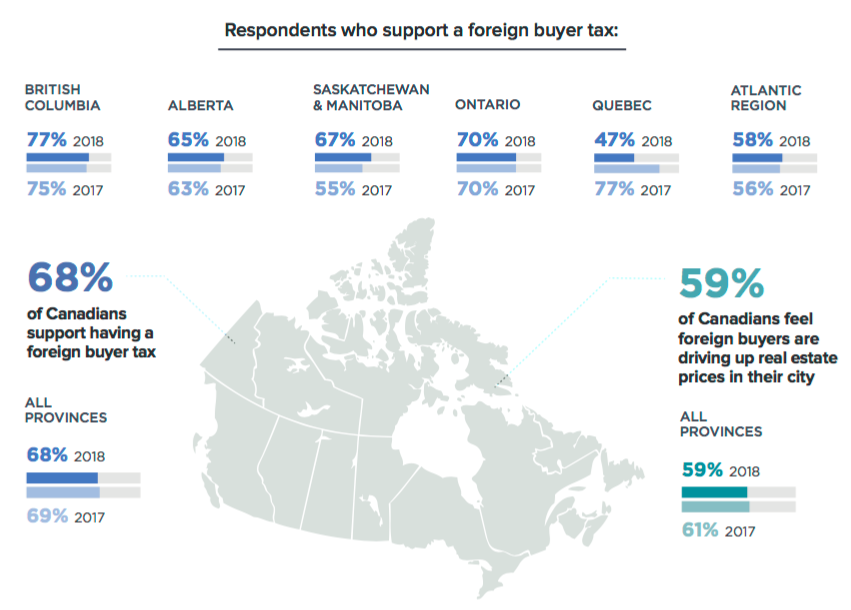
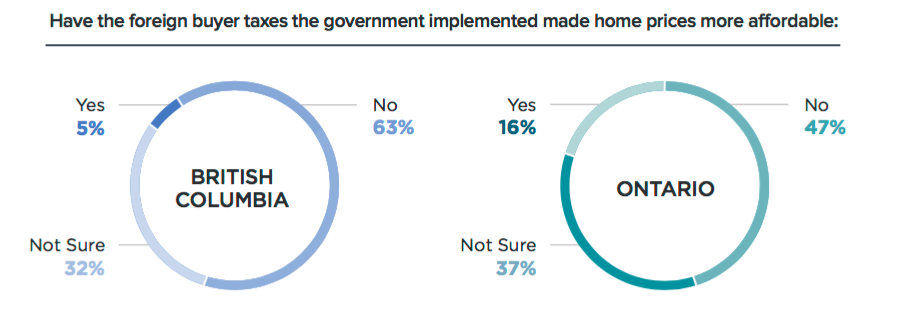
The measure appears to have resonated well with all Canadians; according to survey results, 69 per cent of respondents from all provinces indicated they support the tax, while 61 per cent felt foreign ownership directly impacts prices in the local housing market.

Perhaps not surprisingly, respondents from provinces with the most competitive real estate marketplaces were most likely to support the tax: 77 per cent of British Columbians and 70 per cent of Ontarians indicated they were pro-tax.

Support extends beyond affected Housing markets

However, even respondents from provinces where foreign investment and homeownership is not considered a stressor on the market, indicated support for the tax; 65 per cent of Albertans indicated support, even though only 40 per cent feel out-of-country buyers impact housing prices in their region. Continue Reading…

Investing for people over or under 45

By Tea Nicola

(Sponsor Content)

Your ideal investing strategy when you’re 25 just is not the same as when you’re 52.

That’s because what you earn is partly a function of what you’ve already managed to acquire. In Canada, about 85% of all financial assets are in the hands of people over age 45. Pension assets are held in the same proportions. On the real estate front, just 32% of all real estate value is in the hands of those under age 45. Meanwhile, fewer companies today offer a pension plan of any kind. The defined benefit pension plan is on its way to extinction.

What’s a young person to do? And for older investors who are going to retire earlier, how should their investment strategy change? What are the lessons that need to sink in when it comes to investing for people over or under 45?

What’s the investment strategy for Canadians under 45? Lower your fees!

You’re finished with school (at least for now). You’ve entered the job market and you’re starting to build up some savings. You’re diligently putting between 10 and 20 per cent of your salary into an RRSP. The younger you start to contribute to an RRSP, for instance, the sooner you can take advantage of compound interest.

Regardless, you want a good return on your investment and maybe you’ll get lucky and enjoy a bull market.

You can’t actually control that return, even if you’re investing in your own company … but if you’re using an investment platform like WealthBar or a traditional firm, you definitely can control how much you pay in fees.

For instance, with a WealthBar account, an investor might pay about 0.6% in management fees to WealthBar, versus 2.2% for a mutual fund at a bank. Put another way, an investor might pay $10 a month for WealthBar to manage $25,000, versus nearly $46 per month with a typical bank mutual fund.

Fees add up! While it may seem like the older generation controls the vast majority of assets (OK, they do), young people can at least control how much they pay a firm to manage their account. The right choice can literally save hundreds of thousands of dollars in value that would otherwise pad a financial adviser’s pocketbook.

But, should you race to the bottom? Perhaps not. Ensure that your strategy is still sound and diversified in order to achieve your goals in time. So, do not invest all your money into that 0.05% US Equity ETF. Some fees are ok, if they provide value such as diversification, cash flow, currency alignment and liquidity.

What’s the investment strategy for Canadians over 45? Reduce your risk!

Perhaps you’re one of the lucky Canadian investors over 45 who has had a good run. A pride-inducing chunk of that 85% chunk of financial assets are in your account. Continue Reading…

How in sync are global Central Banks?


By Kevin Flanagan, WisdomTree Investments

Special to the Financial Independence Hub

Without much fanfare, the U.S. Federal Reserve (Fed) provided its policy guidance late in May. Although no rate hike was implemented [it raised its overnight lending rate by 0.25% at 2 pm today, June 13, at 2 pm: Editor]  the money and bond markets fully expect the U.S. central bank to continue on its tightening path for the remainder of 2018, if not beyond. While the lion’s share of the focus has been Fed-centric on this front, it seems like a good exercise to check in on what the expectations are for the developed world’s other key monetary policy makers.

Heading into 2018, optimism for ongoing global growth seemed to be the norm. Indeed, along with the outlook for continued global growth, discussions were arising on whether central banks would soon turn their attention to any potential increase in inflation. While we still have almost seven months to go in this calendar year, recent data appears to be suggesting a plateauing of sorts on the economic front.

One economic indicator that is widely watched for help discerning economic trends on a global basis are the various Purchasing Managers’ Indexes (PMI) on a country or regional basis. While the levels being posted in the developed world still point toward further expansion, they don’t necessarily indicate a pick-up in growth prospects on the immediate horizon. In fact, the readings for April on an aggregate basis were relatively flat, and in some cases — such as the eurozone, the UK and Canada — have actually slipped a bit from their recent peaks.

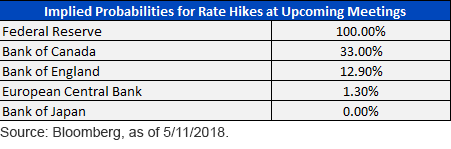
So, what should investors expect in near-term global central bank policy? As illustrated in the table above, expectations for the upcoming policy meetings certainly differ quite a bit. The overarching outlook is for the Fed to raise rates at its convocation on June 13, with the Fed Funds Futures implied probability being 100%, as of this writing. The remaining four developed world central banks — the European Central Bank (ECB), the Bank of England (BOE), the Bank of Canada (BOC) and the Bank of Japan (BOJ)  — all fall in the “no rate hike” camp. Continue Reading…

“Unretirement” and why it’s not selfish to be selfish

“Unretired” novelist and blogger Joyce Wayne

By Yvonne Ziomecki, HomEquity Bank

Over the last few years, we have seen a growing trend among older Canadians: what we call “unretirement.”

This is where some Canadians take action on long-held dreams once they settle into their retirement and start to consider activities and interests for added personal fulfilment. They’re increasingly seizing the opportunities that retirement presents, fulfilling personal passion projects, which, up until now, they never had the opportunity to prioritize.

One particular obstacle seems to hold Canadians back from achieving their retirement dreams: the guilt of feeling selfish if they actually do something just for themselves!

The obstacle to a fulfilling unretirement: selflessness

We recently surveyed 1,361 Canadian homeowners, aged 55 and over. We asked, “If you received a $100,000 cash gift, what would you most want to do with the money?”

Using the money to pay off debts or giving the money to family members or donating to charity were very popular choices. More popular than putting the money towards their own retirement or funding a lifelong dream.

It seems that Canadians are extremely generous souls, putting others’ needs ahead of their own. But is their selflessness preventing them from having a fulfilling and purposeful retirement?

Mark van Graft, Vice President at Mackie Research Capital Corporation, believes it is.

“I enjoy motivating my clients to realize that it’s not selfish to be selfish”

For decades, Mark has been helping Canadians to make informed financial decisions in their own best interests.

“I enjoy motivating my clients to realize that it’s not selfish to be selfish,” he says. “They should spend some of their investments on their own enrichment versus sitting on savings or worrying about everyone else.”

Mark likes to help his clients embrace their personal goals and aspirations in their retirement. “Coaching clients who have unrealized dreams is one of the favourite parts of my job,” he says.

“I show clients how to use a reverse mortgage, not as a last resort or dire straits resource. A reverse mortgage can unlock funds to go beyond aging at home. It’s more like enabling a desire to ‘unretire,’ to bring a passion project to life, to fund a legacy project or finance a long-held dream to travel or innovate.”

Write a new chapter and unretire

Joyce Wayne is a retired college writing instructor and an unretired novelist and blogger. “I have always loved writing,” she says. Continue Reading…