All posts by Financial Independence Hub

5 financial tips that save money in the long run

By Sia Hasan

Special to the Financial Independence Hub

The financial steps you take now can have a major impact on your life. Believe it or not, there are changes you can make right now if you would like to save yourself a lot of money.

Below are five tips you can follow if you would like to handle your finances in the best way possible.

1.) Save for Retirement

First, it’s never too early to start saving for retirement. For example, if you don’t already have one, you can open up a self directed IRA (or its Canadian equivalent, the RRSP.) Contributing money to your retirement account now can help you ensure that you save up enough money for when you are no longer able to work. If you start now, you can help ensure that you earn more in interest as well.

2.) Focus on Maintenance

Maintenance of your home, car and other things you own can be expensive. However, not maintaining your home or vehicle can actually be a lot more expensive in the long run. Therefore, even though it can be tough, it’s important to make maintenance a top priority. This can help you ensure that things last longer and can help you avoid more expensive repairs later on down the road.

3.) Take care of your Health

Along with focusing on taking good care of your car, your house and your other belongings, it is also important to take good care of yourself. Not only can taking care of your health help with your overall happiness and well-being, but it can save you a lot of money as well. Therefore, it’s important to avoid smoking or drinking too much alcohol, and it’s also critical to see your doctor and your dentist on a regular basis. Continue Reading…
Use your Tax Refund to jumpstart your Savings

By Jordan Lavin, RateHub.ca

Special to the Financial Independence Hub 

It’s tax season, and if you’re like the majority of Canadians you’ll be getting money back from the government.

That’s right. Out of everyone who files a tax return for the 2017 tax year, 58% are getting a refund and the average amount is $1,765.

That’s not a small amount of money. $1,765 is enough for a nice new TV, a beach getaway, or maybe even a deposit on a new car. If you have a big tax refund coming your way, you might already be dreaming of all the ways you can spend it.

But I want you to think of it another way. Your tax refund is a refund. You’ve paid too much money to the government in taxes over the year, and now they’re returning it to you, without interest. If your tax refund is $1,765, that means you paid more than $147 a month too much in taxes over the year.

It’s your money, not free money!

It’s not free money. It’s your money, that you already earned and were forced to save.

You could take your tax refund and splurge on something fun. But since you’ve already saved that money, why not keep it going and use it to earn money that actually is free?

In fact, you can use a tax refund of $1,765 to generate $724 in interest by depositing it in a high interest savings account, TFSA, or RRSP, and allowing it to grow. That’s more “free money” in your pocket.

Need proof?

Today’s best high interest savings account rate is 2.3%. At that rate, a deposit of $1,765 will earn $41.03 in interest in the first year. After 20 years, it will have earned $1,030 in interest. Once tax is taken out, that means the total earnings on your savings would be $2,489 and change.

Wait, taxes?

Yes, money earned in an ordinary high-interest savings account is taxed at your marginal rate. For example, if you make $50,000 per year and live in Ontario, your marginal tax rate is 29.65%. For every $100 in interest your savings account earns, you will owe $29.65 in income tax.

The advantages of TFSAs

Fortunately, there are some ways to reduce the amount the government takes out of your earnings.

Continue Reading…

Tools and platforms for would-be Webpreneurs

By Linda Binklage

Special to the Financial Independence Hub

So you need your own website? Whether you’re a small business, a budding webpreneur or just someone with a message to share, a website is a great way to reach your audience.

Nevertheless, many people are put off starting a website for fear of the costs and expertise involved. What they don’t know is that there are loads of amazing tools and platforms out there that can help them to design an effective website at an affordable price.

Here are some of the best tools and platforms for making a website:

Duda

Duda is a responsive website builder. Choose from a range of ready-made templates then use the drag and drop editor to create the look and the layout you want. You can integrate your site with the likes of PayPal, OpenTable and Disqus. And there are some great website personalisation features, allowing you to adapt your site for different customers.

WordPress

WordPress is a favourite amongst rookie and professional web designers for a reason. It’s great for everything from a basic blog to a fully-fledged e-commerce site. It’s really easy to use. And this is one platform where the cost of a website needn’t be a worry. Free packages cover all of the basics. And if you’re looking for more templates, greater customisation or full control over how your website looks and behaves, there are very reasonably priced upgrades you can sign up for. Continue Reading…

5 rare types of Credit Card Travel Insurance coverage

By Maria Weyman, creditcardGenius

Special to the Financial Independence Hub

Having a form of insurance coverage while travelling gives tremendous peace of mind. And when that important coverage comes from the credit card you already have and you use to book your travels, even better.

Why? Because insurance coverage built in with your credit card has no additional cost, not to mention it’s convenient.

Despite the convenience and potential to save money, it pays to read the details.

Reading your insurance certificate

Your credit card insurance certificate should have the details of what coverage comes with your credit card as well as information on exclusions and limitations.

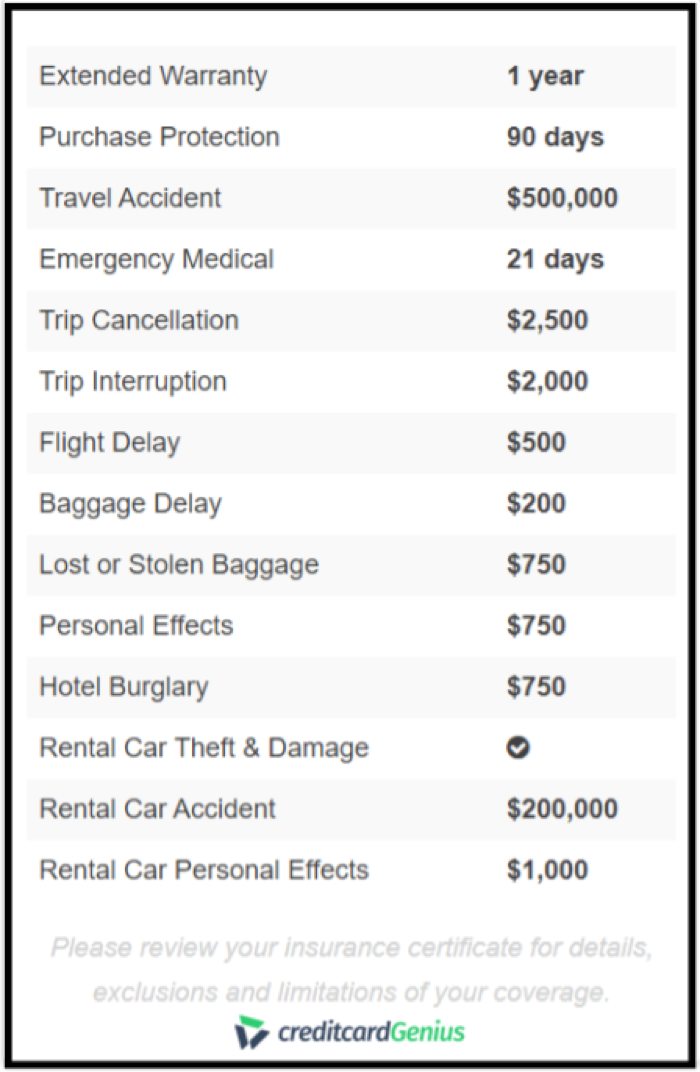
For example, here’s a list of coverage one credit card offers:

However, even after reviewing this list, it’s always best to still review the certificate to read all the fine details so you know exactly:

  • what is covered,
  • what’s excluded,
  • the maximum amount you can claim per coverage, and
  • any additional terms and conditions.

5 rare types of travel insurance coverage

There are 16 types of insurance coverage we track; however here’s an overview of the five rare types of travel insurance coverage your card might include:

1.) Trip Cancellation

Opting for lower-cost non-cancellable flights and hotels saves money up front. But what happens if you need to cancel? Trip Cancellation coverage takes care of that for you if you’re cancelling for a list of emergency reasons.

Keep in mind there will be a cap to how much you can claim, typically around $1,500. However $1.5K is still better than $0 without this coverage. Continue Reading…

Top Ten questions & answers on Medical Tourism

Medical building in Guatemala City

By Akaisha Kaderli

Special to the Financial Independence Hub

Because Billy and I live a lifestyle of travel, we often get readers asking us basic questions about medical tourism. Below we have the answers to some of the most common questions we get asked. How do you know if this option will work for you? The following should help you decide.

Q: I have heard the term “Medical Tourism,” but what exactly is it?

A: Generally, Medical Tourism refers to going elsewhere other than your own city or state/province to receive medical care. For example, people in the U.S. have been going out of their home state to Mayo Clinic or Cleveland Clinic for years, and no one thinks twice about it. Canadians will come to the U.S. for procedures perhaps because they don’t want to deal with long waits in their own home country or maybe they have other personal reasons.

Today, there are dozens of countries like Thailand, Mexico, Costa Rica, India, Guatemala, Singapore and the Philippines which offer excellent medical care delivery in ultra-modern facilities for very affordable prices.

The importance of medical tourism – and this cannot be overstated – is that its availability offers options to those who are:

  • Under-insured
  • Self-insured
  • Not insured and,
  • For procedures not approved in the USA (or the patient’s home country).

Q: Is Medical Tourism expensive? And how does one choose a hospital or country?

A: In terms of budgeting for medical tourism, we think it’s a good idea to have an emergency fund, or institute your own style of a Health Savings Account, where you only utilize that money for health related issues.

When you purchase medical care overseas, you will know how much it will cost before you purchase. There is no guessing game because you check off what you want as if from a menu. If you want to have an “Executive Physical” for instance, you can choose all the features you would like: lung x-ray, bone density test, colonoscopy, full panel blood tests, and so on, and with every choice, your total at the bottom of the page changes. You see beforehand what your cost outlay will be and what price everything is individually.

The delivery of medical care in the States is expensive and out of the reach of many. If you have a high deductible, and you go out of network, sometimes that deductible doubles.

Treatment in the States for a heart condition or cancer can cost hundreds of thousands of dollars. Not so overseas.

A heart valve replacement in the States can cost US$170,000 but will run you US$24,000 in Guatemala City. Chemotherapy in the States runs about $75,000 but is under $20,000 in Guatemala City. A bone marrow transplant can cost up to $200,000 in the U.S., but will run up to $25,000 in India. A spinal fusion runs between $80-100,000 in the United States but will cost you $6-10,000 overseas.

There are many medical tourism concierge services available and websites of hospitals in various countries have their prices listed for procedures. Continue Reading…