All posts by Financial Independence Hub

Do you want to be younger in 2018 than in 2017?

By Fritz Gilbert, TheRetirementManifesto.com

Special to the Financial Independence Hub

I hate New Year’s Resolutions, and I can’t remember the last time I made one.

Why make them, if you’re most likely going to break them?  That doesn’t make sense to me.  Call me cynical, but that’s just not the way I think about challenging myself to improve.

Don’t get me wrong.  I love thinking about how I can move life from Good To Great, and I enjoy having goals.  I think often about both my long- and short-term goals, and where my life is going.  I do it informally, by constantly watching for opportunities to create improvements in my life and developing personal challenges.   I push myself to achieve the goals I set for myself (like writing this blog).  Do you?

Make the pursuit of challenges an ongoing habit in your life. It’s a way of Living Life At The Limits, and it keeps life interesting.  Most of you know that I’m a bit of a fitness nut, and I’m always on the lookout for opportunities to challenge myself.  I grab onto interesting things as they cross my path.  It’s why I swam in the cold waters of London on an early November morning.  It’s something that keeps me young.

It works for me.

Try it …  It just may work for you.

Today, I’ll give you your chance …

A Bunch Of Folks Decide To Get Younger Together 


Something exciting happened at the beginning of this year, and it generated this post you’re now reading (originally posted early in January).  A new Community/Movement/Revolution was launched, and it’s rapidly taking shape.  It’s only a few months old but it’s starting to run.  And it’s starting to run …

… Fast.

Do You Want To Be Younger?

This development is a legitimate way to make you Younger In 2018 Than In 2017, if you’re willing to commit to doing a bit of work. A bunch of folks are joining in and this thing is gaining momentum.  The fact that it’s (original) timing falls in line with New Year’s resolutions is irrelevant, in my book (tho, in fairness, it’s a good time to launch the challenge, as many folks are thinking about trying to get into shape for the New Year).

This movement is a great opportunity and I’m convinced that it can, indeed, help in your quest to Achieve A Great Retirement (my byline).  It’s a group of friends with similar interests urging each other on to mutual success (on both sides of the US/Canada border).

If you’re interested, check it out.  You don’t have to commit today.  Just explore and see if it’s something that interests you.   I’ll show you below, but in case you’re impatient and just want to head over there now here’s the link, but please don’t go there yet 🙂 

The group’s open to all, and readers are especially encouraged to participate.

The #YoungerNextYear 2018 Community Is Launched! Join In The Fun. EnCourage each other. Succeed. Click To Tweet

The Birth

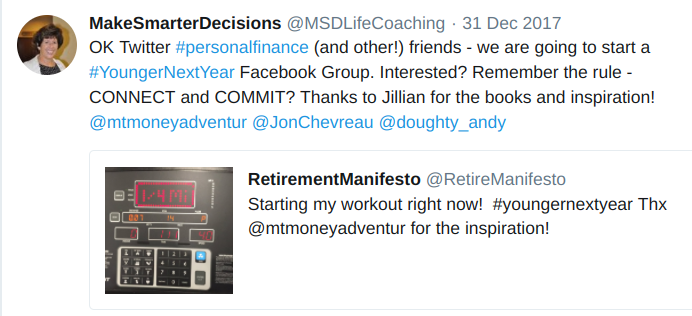
The excitement all started on Dec 31, 2017 when Vicki @ MakeSmarterDecisions sent the following Tweet and, in the process,  Launched A Movement …

The Birth Of #YoungerNextYear2018:
What’s Younger Next Year All About?
Continue Reading…

Priced out of the housing market? 5 creative financial ideas to get In

By Sean Cooper

Special to the Financial Independence Hub

Are you finding it a challenge to buy real estate in the big Canadian cities? If you’re looking to purchase a home in Calgary, Toronto or Vancouver, even buying with the minimum five per cent down can be tough. (The new mortgage stress test sure doesn’t help.)

Despite rising home prices, millennials haven’t given up on buying homes. In fact, they’re still finding ways to get into the real estate market. Survey after survey shows that younger folks still see homeownership as a good long-term investment.

So how do you actually afford to buy real estate in the more expensive markets? Let’s look at five creative ways to still get into pricier real estate markets:

1.) Tapping the Bank of Mom and Dad

The “Bank of Mom and Dad” may be a term you’re already familiar with. Property virgins are increasingly turning to their parents for financial help with a down payment. Parents often gift their adult children some or all of their down payment. Often, this benefits both parties. The adult children can live closer to their parents in a good neighbourhood and see each other more often. The parents may be able to provide childcare, while the adult children can look after their parents in their old age.

2.) Buying with Family and Friends

Are you finding it tough to qualify for a mortgage if you’re single? You don’t have to necessarily buy a property with a spouse. A new trend is to buy with family and friends. If you know a family member or friend that you trust, why not combine your finances and buy a home together? Two incomes and down payments: sure makes it a lot easier to afford a home in a nice neighbourhood. (However, if you buy with family or friends, be sure to have a written agreement in place so that when someone wants to sell, your expectations are in line.)

3.) Buying in a Satellite City and Renting in the Big City

Can’t afford to buy in the big city, but still want to own a piece of the real estate pie? Why not buy in a satellite city and rent in the big city? This is becoming a lot more common in Toronto and Vancouver, where the cost of homeownership is the highest in the country. When you buy in a more affordable satellite city, you can start build up equity to eventually move into the big city. Continue Reading…

Quality is the Factor ETF investors should emphasize in today’s Market

By the WisdomTree ETFs team
Special to the Financial Independence Hub
 

Investing is hard. Trying to time the market is harder. Timing return factors at the right time? Forget about it.

The past few years have seen some of the industry’s brightest minds publish papers concerning the feasibility of timing return factors. The conclusions have varied slightly, but most generally agree that when investing in factors, trying to determine which ones to invest in at a given time is an incredibly difficult undertaking.

However, most of these papers analyze factor timing from the lens of the valuations of these factors. What if we take a different approach and see if we can estimate which factors could outperform from the context of where we are in the market cycle?

Where are we now?

The U.S. equity bull market started on March 9, 2009. In the almost nine years since then, the S&P 500 has rallied nearly 400%.1 We are certainly not calling for an end to the bull run — in fact, the market environment still appears benign, and corporate earnings have remained strong — but it is certainly not a stretch to claim that we are closer to the end of the cycle than we are to the beginning of it.

As of this writing [mid-February], we are in the midst of the longest period without a 3% pullback in the history of the S&P 500.2 With implied and realized volatility hovering near their all-time lows, it seems reasonable to expect more choppiness — if not an outright correction — coming in the next few months. Based on what we know from history, what factors tend to outperform in the late stages of market cycles?

Factor performance prior to market corrections

Factor Performance Prior to Market Corrections

Late-Stage Outperformers: Momentum, Quality

Dating back to 1990, there have been ten distinct 10% corrections in the S&P 500,3 with bifurcated results in the months preceding the correction. In the lead-up to the downturns, momentum and quality stocks have seen consistent excess performance compared to the market, whereas the size and value factors have generally underperformed.

These results provide an interesting backdrop for today’s market. If we are indeed late in the cycle, and the market dropped 10% tomorrow, this trend would hold true once again. The MSCI Momentum Index and MSCI Quality Index have outperformed the S&P 500 over the last 12 months (by 1,700 and 320 basis points (bps), respectively), whereas the Russell 2000 Index and Russell 1000 Value Index (well-known small-cap and value indexes) have both lagged by more than 700 bps.4

While it is interesting to look at what factors worked well, we think it is also important to analyze what didn’t. If size and value lagged, one can conclude that their complements — large caps and growth companies — outperformed as a result.

Factor performance during market corrections

Factor Performance during Market Corrections

Quality: The best of Factors in the worst of times

Shifting our focus to the market corrections themselves, when the S&P 500 fell at least 10%, it is clear that quality was the most desirable factor by a relatively wide margin. Intuitively, that makes sense—when there is stress in the markets, high-quality companies should help protect investors during market downturns. Encouragingly, the factor excess performance was largest in the most severe market sell-offs (with the quality factor having captured only 74% of the market downside during the tech bubble and 81% during the financial crisis).

Again, value underperforms here, with size and momentum each having relatively more mixed results during market corrections.

What are Size and Value good for? Continue Reading…

The 5 worst financial decisions you can make

 By Alana Downer

Special to the Financial Independence Hub

Sometimes when it comes to your finances it can be difficult to know if you’re making the right decision. What bank account should you pick? Should you buy a car outright or pay it off as you go? Are you eating too much takeaway? Every day we have to make decisions that affect our finances and some are harder and more consequential than others. In fact, sometimes one small financial decision can have a lasting impact on the health of your bank account. Here are the five worst financial decisions you can make, so you can avoid making the wrong choice in the future!

1.) Spending more than you earn

Overspending is probably the number one money mistake that you can make. You cannot build wealth or be financially secure if you are spending more than you’re earning. By spending money that you should be saving you are doing serious damage to your finances and stalling your financial progress.

It’s true that not everyone has high-paying jobs or huge inheritances, but this doesn’t mean you can’t build up healthy savings by simply monitoring your spending. Part of spending less than you earn means putting effort into living below your means. Track your spending and take a hard look at your spending habits. Are you buying two or three coffees a day? Do you pay a lot of money every month for a gym membership you don’t use? Or perhaps on a bigger scale, you have a huge house or luxury car that you just don’t need.

2.) Never Budgeting

Creating a budget goes hand in hand with learning how to spend less than you earn. A budget is a blueprint for financial success. Without budgeting, it is nearly impossible to keep track of your expenses and ascertain whether or not you are spending more than you should. By creating a budget to follow week-to-week or month-to-month you can stay on top of your finances and prevent yourself from making financial decisions that you may regret.

When creating a budget, it’s a good idea to look at your whole year and the payments that you have to make, such as your rent, your bills, your car registration and cost of transport. Use bills, your bank statements and receipts to help you understand all your expenses. Once you’ve figured out roughly how much you spend over a certain period, figure out your net income (i.e. the money deposited in your bank account each pay period). Subtract your expenses from your income and what is left should be what you aim to save.

3.) Not creating an Emergency Fund

Many people have the mindset that bad things won’t happen to them and that if they do, they will find some way to deal with it when the time comes. This is not a financially intelligent way to think and could leave you in serious trouble if something goes wrong. An emergency fund is exactly what the name suggests, a bank account that can you use in the case of an emergency without having to dip into your savings or rearrange your budget. It is money set aside specifically for use when things go haywire.

Continue Reading…

What is a Mortgage Vacation?

By Sean Cooper

Special to the Financial Independence Hub

Do you enjoy going on vacation? Who doesn’t? So, the term “mortgage vacation” has to be something similar, right? When you hear mortgage vacation, you’re probably picturing yourself laying on a warm, sandy beach, drinking an umbrella drink. Well I hate to break it to you, but although you got the vacation part right, you forgot the most important part: the mortgage part.

A mortgage vacation is a feature that lets you skip paying mortgage payments for up to a few months, but with a catch. You have to prepay the amount in advance. In an era where savings rates are near record lows and household debt is near a record high, mortgage vacations have become a popular feature with mortgage lenders. Who needs to save for a rainy day when you have a mortgage vacation?

A mortgage vacation can help you out when you run into financial difficulty or when you want to use your cash flow towards something else. But as the saying goes, there’s no such thing as a free lunch. By planning ahead of time, you can avoid taking a mortgage vacation and still be on your way to burning your mortgage.

What is a Mortgage Vacation?

If you’re like most homeowners, you’re introduced to mortgage vacations in this way. You get a letter in the mail from your lender letting you know that you’ve been approved for a mortgage vacation. Yippee! The banks market mortgage vacations like they’re a privilege for their best clients, but as I mentioned earlier, there’s a catch. Hidden in the fine print is what happens when you skip your mortgage payment. Continue Reading…