All posts by Financial Independence Hub

Does downsizing to a secondary housing market really save money?


By Penelope Graham, Zoocasa.com

Special to the Financial Independence Hub

Despite the efforts of new rules and regulations, real estate prices continue their upward trajectory across the nation; according to the Canadian Real Estate Association, the HPI Index rose in nine of 13 markets in January by an average of 7.7 per cent, while the average home price increased 2.3 per cent, to $481,500.

However, CREA noted that excluding Canada’s largest housing markets – Toronto and Vancouver – would strip a whopping $107,500 out of the national sale price, with the remaining markets contributing to an average of $374,000.

While it has always been more expensive to live in a main city centre than in a rural market, excessively hot price growth over the last few years has increasingly prompted buyers to explore their options in secondary real estate markets, fuelling the migration to further-flung communities with comparatively affordable housing. And, as new stress-testing mortgage rules designed to squeeze affordability are now in place, this big-city exodus won’t slow any time soon.

Savings offered by secondary Real Estate markets

This trend is perhaps most evident in Ontario’s Greater Golden Horseshoe region, home to the City of Toronto and surrounding markets that stretch as far as Niagara, Peterborough and Windsor. Prices have ballooned in Toronto over the last two years and – while slightly softer following the implementation of the Fair Housing Plan last year – remain firmly out of reach for many prospective home buyers. For perspective, the average sale price in the Greater Toronto Area fell 4.1 per cent to $736,783 in January, yet a buyer earning the city’s median household income of $78,280 would qualify only for a maximum mortgage of about $545,692.

One of the most popular real estate destinations for these displaced buyers is the City of Hamilton, located to the west along the shores of Lake Ontario. At a roughly one-hour’s drive from Toronto’s downtown core, and boasting beautiful natural features in addition to a rapidly-gentrifying downtown, home seekers have been drawn to the Hammer in droves.

However, affordability is clearly their main motivation, as freehold Hamilton real estate can be had for a relative bargain compared to its Toronto counterparts, with the average home costing $549,546 in January. That’s a whopping $734,435 less than the average Toronto detached price of $1,283,981.

Is It worth moving to another city?

Such savings are tempting – but there are considerations all buyers should mull over before booking a long-haul moving truck. Continue Reading…
Online Fraud: 7 simple ways to protect yourself from a #clicktastrophe

By Rob Fodor

Special to the Financial Independence Hub

If you’re like most people, you have a phobia about phishing. In fact, as we found in a recent Interac survey, almost one quarter of Canadians have clicked on a link that resulted in a phishing scam.

It’s no wonder Canadians are more likely to be worried about payment fraud scams such as phishing and skimming than they are about having their homes broken into or their cars stolen. Fortunately, just as you can take steps to protect your home and car, there are things you can do to protect yourself from online scams, too.

Beware Phishing trips

Phishing is a scam where fraudsters try to get your personal or financial information – such as passwords or card numbers – by masquerading as a trusted person or business, usually through email, text or an instant message, but also sometimes by phone. Continue Reading…

Budget 2018 aftermath: Holding passive investments inside Private Corporations

By Brad Smith and Tea Pupica-Terzic 

Special to the Financial Independence Hub

The 2018 Federal Budget confirms that the Government will move forward with the implementation of the December 13, 2017 proposals regarding the splitting of income by private company owners and their family members. The Budget, however, proposes two additional key measures regarding the taxation of passive investment income earned by a Private Corporation, a topic that was aggressively targeted by the July 2017 consultation paper on tax planning strategies involving private corporations.

The first measure focuses on limiting the access to the small business tax rate to private corporations earning a significant amount of passive income.[1]  Currently, the small business deduction limit allows for $500,000 of active business income to be taxed at a preferential small business tax rate. This $500,000 limit begins to be ground down once the taxable capital of an associated group of companies reaches $10,000,000; it is completely eliminated once the taxable capital of the group is $15,000,000.

Budget introduced new reduction mechanism on passive investment income

The Budget’s proposal introduces a new reduction mechanism, which will work in tandem with the aforementioned existing business limit reduction, based on the passive investment income earned by a private corporation and its associated group. Specifically, once a corporation and its associated members earn $50,000 of passive investment income in a given year, the small business deduction limit begins to be ground down, on a straight line basis, until the passive investment income reaches $150,000. At this point, the small business deduction limit would be ground down to nil. The new reduction will apply to taxation years that begin after 2018.

The second measure aims at correcting an unintended tax advantage currently enjoyed by some private corporations when paying out eligible dividends to their shareholders in situations where the refundable tax pool (aka refundable dividend tax on hand “RDTOH”) was generated from investment income that would need to be paid out as a non-eligible dividend. The Budget is creating a new account, called the eligible RDTOH account, which will include the tax paid on eligible portfolio dividends.

Otherwise, tax paid on investment income or on non-eligible portfolio investments will be included in the non-eligible RDTOH account. The ordering rule will dictate that a private corporation, in payment of non-eligible dividends, will first have to access the refundable tax in the non-eligible RDTOH pool before it can tap into the eligible RDTOH pool.  A payment of eligible dividends will only entitle the corporation to dividend refund to the extent of its eligible RDTOH pool. These new measures will also come into play after 2018.[2] Continue Reading…

Canadians miss out on $1,000 a year from Credit Card rewards, RateHub says

By Alyssa Furtado, RateHub.ca

Special to the Financial Independence Hub

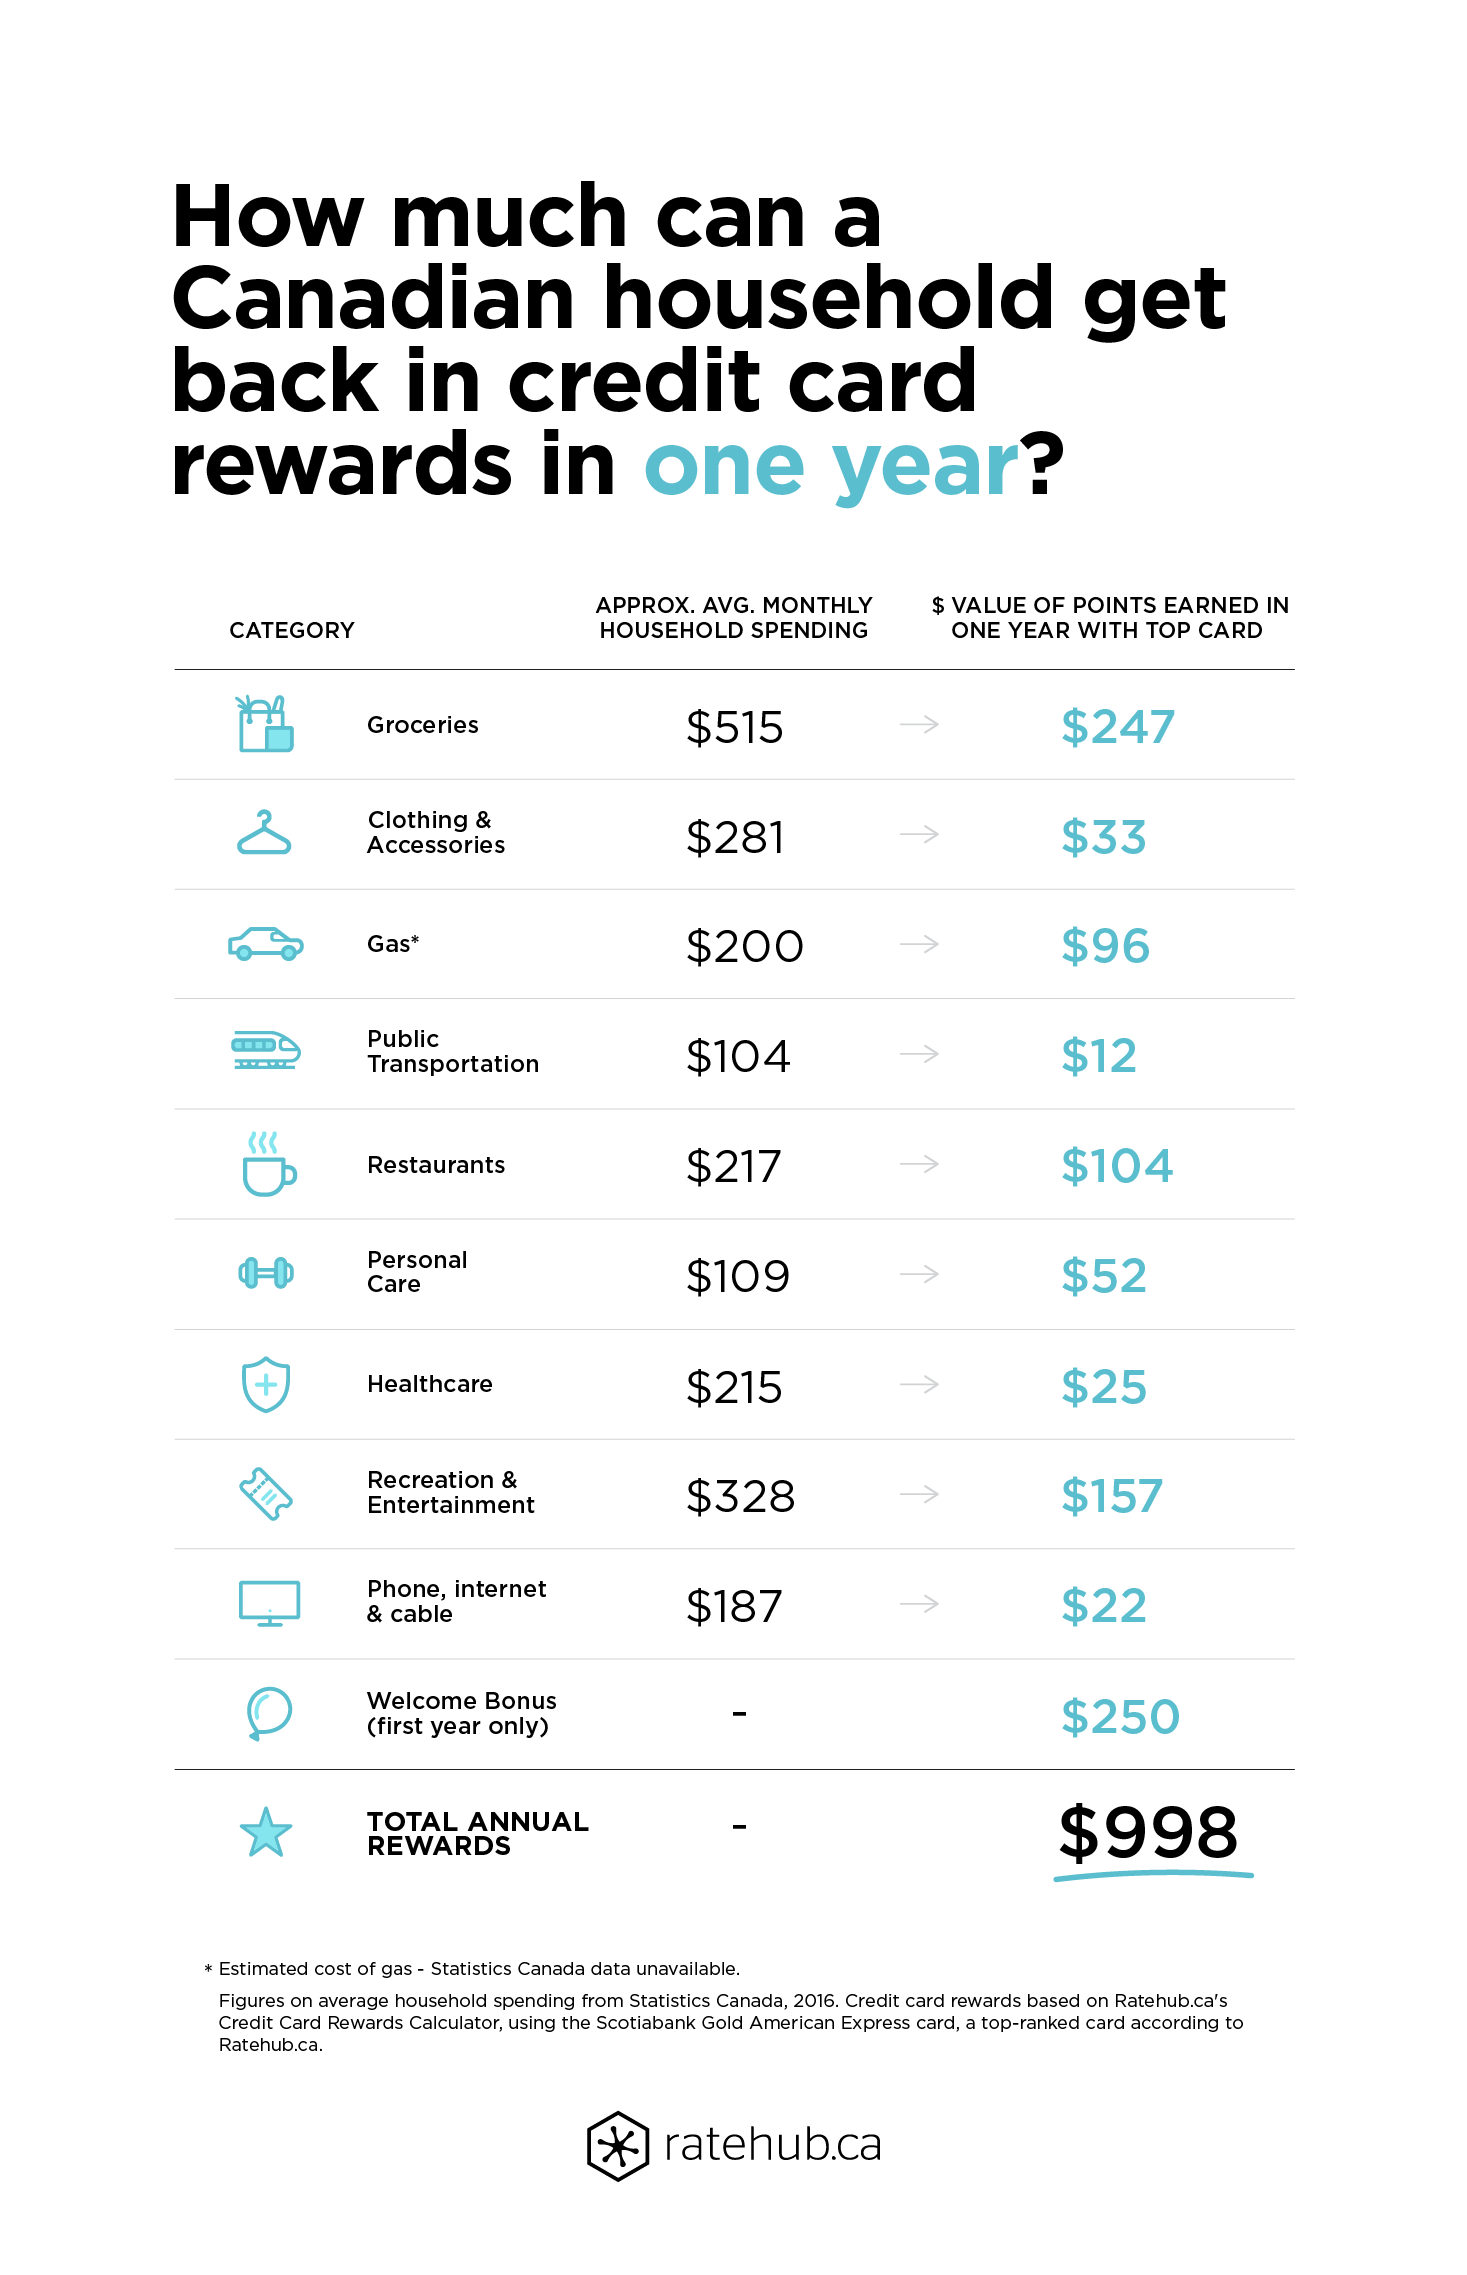
A whopping 86 per cent of Canadians say one of their top reasons when choosing a new credit card is earning rewards points or cash back, this according to a recent survey done by Ratehub.ca. 42% of those surveyed said they’ve never searched or compared credit cards to ensure they’re getting the maximum return.

Based on spending averages from Statistics Canada, that means Canadians could be giving up almost $1,000 rewards by not using one of the best credit cards available.

How is that possible? Well, when you look at some of the best credit cards in Canada, they offer up to 5% in cash back or rewards for certain categories. In addition, many cards offer a big sign-up bonus that could be worth anywhere from $250 to $500, so it’s not hard to see how some people are missing out.

Choosing a new credit card

With 29 per cent of those surveyed saying that the card they use most has been in their wallet for more than 10 years and another 50 per cent saying they would never pay an annual fee, perhaps it’s psychology that’s holding them back from making a change?

Continue Reading…

Budget 2018: Pixie Dust

By Trevor Parry

Special to the Financial Independence Hub

While Bill Morneau’ s second federal budget can be described as a punt, this third foray can best be described as a “fart in the wind;” however,  given that this is a Justin Trudeau government, the term “pixie dust” seems far more appropriate.

The Budget included two major tax measures, one relatively substantial and the other curative.  The latter was a tweaking of the rules surrounding Refundable Dividend Tax on Hand (RDTOH) , dividing the pools into eligible and ineligible pools, thus corresponding with their according dividend. The more substantive measure was to introduce a measure that reduces the ability of a corporation (or its related entities) to claim the Small Business Deduction where “substantial” income has been earned of invested after tax profits.

The new rule would see a company’s SBD eroded by 5 dollars for each 1 dollar of passive income earned in excess of $50,000 each year.  If the company earns $150,000 per year in passive income it loses the entire SBD and is subject to General Rate taxation, effectively 26%.  The government claims that this will affect about 3% of businesses.  In the cases where the full SBD is lost the company will end up paying about $55,000 in additional corporate tax.  The same company would also be paying out eligible dividends, which will be taxed at lower personal rates by the shareholder.

Finance’s pragmatic policy wonks prevailed with the Small Business Deduction

I actually think that the more pragmatic policy wonks in the Department of Finance prevailed with regard to this measure.  The SBD was introduced to provide a tax incentive for small businesses to save and invest and by this process graduate to a medium sized or growing business.  The problem of course is that tax planners have for decades sought to freeze the status of a small business in place.  This can still be achieved by paying out shareholder bonuses, but given confiscatory personal rates in most of the provinces it is likely that trusted advisors will still the ability of a corporation to defer taxation and recommend that earnings continue to be retained.   The approach the government has taken is a more comprehensive approach to total corporate earnings.  It explicitly says to business owners and incorporated professionals that you can use your corporation as a retirement vehicle, or rainy day fund but you will be taxed as a more mature business.

There are of course planning measures that can be taken to avoid this new measure.  Permanent life insurance remains the last game in town with regard to significant tax deferral possibilities.  Given that the Department of Finance engaged in meaningful consultation in fashioning the substantive update of the “exempt test” rules in 2016 that no wholesale assault on life insurance is in the offing.

Instead, I think the Department will continue to observe the golden rule — “Pigs get fat and hogs get slaughtered” — in deciding what action is necessary.  Like the 10/8 strategy before, there are strategies being implemented today that clearly drift into the aggressive category.   The diversion of loan proceeds to a shareholder in an Immediate Finance Arrangement, or the rebating of commissions without their appropriate declaration of status as taxable income come to mind.

Individual Pension Plans only temporary remedy for new rules

Some might also trumpet the use of Individual Pension Plans.  IPP’s in the right instance are wonderful planning tools.  They are particularly useful for incorporated physicians who cannot plan retirement on the basis of an eventual sale of their professional corporations and who too often suffer from a lack of savings discipline.  Continue Reading…