All posts by Financial Independence Hub

Investing in fads like Bitcoin or Marijuana stocks: Quack like a duck and you may get plucked

By Steve Lowrie
Special to the Financial Independence Hub


It’s now been nearly a decade since investors have had to face down a bad bear market.  Long enough, apparently, that many have forgotten how painful that can be.  Maybe that’s why I’ve been witnessing what seems like an uptick of speculative excess lately – aka, fad-chasing.

For example, there’s been performance chasing in real estate, and continued stockpiling of high-dividend stocks.  At least these qualify as legitimate asset classes if they’re sensibly incorporated.  In an increasing bid to turn up the heat, I’ve also been seeing investors bedazzled by far riskier ventures ranging from cryptocurrency to cannabis. This, despite decades of evidence suggesting what the future has in store for financial fads.  A few lucky players make a fortune, but the vast majority who pile in after the run-up is noticeable are far more likely to be left holding the bag.

When the ducks quack, feed them

Everyone seems to have forgotten how risky a hot hand can be.  Everyone, that is, except the Bay Street and Wall Street denizens who have a saying for these sorts of speculative runs:  When the ducks quack, feed them.  Meaning, as one source has described, “when investors want to buy something … that something is offered for sale.  It doesn’t make any difference if Wall Street knows in its heart of hearts that that something (such as an IPO) is overpriced.”

Make no mistake.  The typical Wall Street brokers and Bay Street bankers are no fools; they are opportunistic.   If they see a chance to make easy money on a hot-hand trading frenzy, they’re happy to help you get in on the action.  Whether you win or lose on your trades, they come out ahead on the transaction fees involved.

Likewise, the popular financial press makes its money by capturing your interest; not by advising you according to your highest interest.  Case in point:  As I write this post, the Yahoo Finance feed is prominently displaying Bitcoin pricing ahead of the Cdn/US dollar exchange rate and major international market returns.  It’s also awash with ads promoting Bitcoin and other cryptocurrency for sale.  So much for objective reporting.

As Reformed Broker Josh Brown once said: “The more you read about Wall Street history, the more you recognize it as the world’s most elaborate petting zoo – lambs, ducks, goats, cows and pigs herded into pens so that bankers and brokers can feed them pellets right from their hands.  We are fed until the bursting point, we almost never walk away on our own.”

So before you decide to buy cryptocurrency, cannabis, or whatever is the next craze to come, here’s what I would suggest you do first:  Think it over while taking a good long walk – most likely in the direction of “away.”
Continue Reading…
Do you need two million dollars to retire?

By Billy and Akaisha Kaderli

Special to the Financial Independence Hub

We like to keep informed about the topic of retirement from the perspective of money managers and those in the financial fields.

You might have read some of these articles also; you know, the ones that say North Americans have not saved enough to retire.

Many of these pieces proclaim that you must save enough in your investments to throw off 80% of your current annual salary so you can afford a comfortable life away from a job. Lots of them will say that you need US$2 million in investments and woe to the person who thinks they can do it on less.

Approximately 10% of the households in the US have a net worth of one million dollars or more. What are the other 90% supposed to do? Not retire? What kind of common sense does this make?  Expecting the regular “Joe” to meet this $2 million dollar mark is not realistic.

As you know, we have almost three decades of financial independence behind us. And while everyone’s idea of a perfect lifestyle sans paycheck is different, we can tell you that for these almost-30-years, we have kept our annual spending around $30,000 or less per year.

The secret: Living within your means

In all of our years of retirement and travel we cannot recall one retiree who regrets their decision to retire. In fact, most have told us that they wished they had done it sooner.

The Society of Actuaries (SOA) recently conducted 62 in-depth interviews of retired individuals across both the U.S. and Canada. These people were not wealthy and had done little to no financial planning. But the vast majority of them shared that they had adapted to their situation and live within their means. Meaning, they have adjusted their spending to the amount of money they have coming in every month.

So basically, it’s really that simple and this is why we say if you want to know about retirement, go to the source.

It doesn’t have to be complicated

In our books and in our articles about finance, we say over and over that there are four categories of highest spending in any household. We personally have made adjustments in all four of these categories, and have therefore reaped the benefits of having done so.

The financial guys and gals will have you tap dance all over the place with investment products, and a certain financial goal you must achieve. They will press upon you the seriousness of this decision to leave your job for a couple of decades of jobless living. We say it doesn’t really have to be that complicated, but it’s very important to pay attention to these four categories.

Listen up Continue Reading…

How to choose your financial oasis

By Lidia Staron

Special to the Financial Independence Hub

So, you have a job where you have to start at 9 a.m. in the morning and end at 5 in the afternoon. It pays a good amount; you’re able to enjoy life and you also have the capacity to pay the bills.

And then it hits you: you asked yourself the question, “Do I want to live here for the rest of my life? Or do I want to go somewhere else and live there instead?”

Questions such as these are pretty common, especially if you’ve reached your 30s. Some people quit their day jobs and turn to freelancing instead, because of the freedom to work from home. Do you want to do that?

In today’s article, I am going to talk about choosing your financial oasis. An oasis, by its definition, is a haven where everything is perfect. So, how do you choose yours? Read on to find out

1.)  Is it Better to Go Abroad?

One of the questions you need to ask yourself is if it is better for YOU to go abroad or not? I emphasized the word “you” because not everyone wants to go abroad due to a lot of reasons such as family, friends, your current job, among others.

Now, if you ask me, the answer to the question depends on where you live. If you live in a developing country where money is a bit harder to earn, then I highly recommend moving to another state or province.

Conversely, if you already live in a country or state that doesn’t have a lot of problems (especially when it comes to money and taxes), then I would suggest that you stay.

Again, this decision is entirely up to you. You have to weigh the pros and cons so that you can have a clearer mind to make the decision.

2.) Find a place with low Income Tax

If you do decide to move out of your country or place and into a new one, find a place where there is low income tax.

You see,  some countries take a huge chunk of your salary per month for taxes. Heck, they even take almost 30% of your salary just for taxes!

Ideally, find a place where income tax is not present. There are certain states in the U.S such as Washington, Florida, Nevada, and Texas that do not require Income taxes.

If you found a place where there is still an income tax, make sure that it doesn’t require more than 15% of your total salary.

3.) Find a place with a low cost of living

One of the criteria for moving into a new state is that it should have low-cost living.

There are certain places that do not have a huge cost of living, such as Iowa, Indiana, Oklahoma, Arkansas, to name a few. Continue Reading…

Sizing up the Size Factor


Small-Cap Growth & Small-Cap Value begin to diverge in 2015

By Chris Ganatti, Wisdomtree Investments

Special to the Financial Independence Hub

It seems like everywhere across the investment landscape in these days there is talk about “factors.” While this isn’t necessarily a new discussion (research has been done for decades regarding the drivers of excess returns within equities), it is easier than ever to pick and choose the factors to which you would prefer exposure.

Size: popular but volatile

When people get excited about changes — changes in policy, changes in growth expectations, changes in political leadership — we’ve tended to see this excitement show up in the behavior of small-cap stocks. We saw this most recently during the “Trump trade,” with the bulk of the performance response coming between the November 8, 2016, election victory and the January 20, 2017, inauguration.

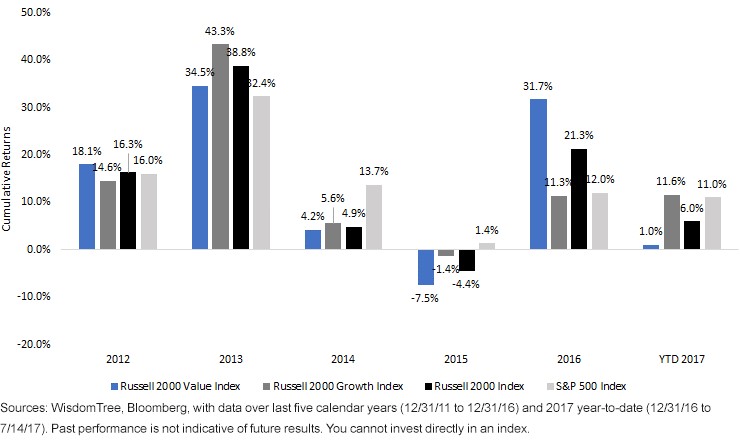
  • In 2012 and 2014, the Russell 2000 Value Index and the Russell 2000 Growth Index performed very similarly. Even the approximate 9% difference between these indexes in 2013 wasn’t particularly noteworthy because U.S. equity market indexes across the board tended to be up 30% to 40% that year.
  • The most recent “tough” year for small caps was 2015, and it was clear that the Russell 2000 Value Index was the laggard, as the Russell 2000 Growth Index was nearly flat. But 2016 saw greater than 20% outperformance of the Russell 2000 Value Index vs. the Russell 2000 Growth Index. In 2017 through July 14, these indexes have reversed again, with the Russell 2000 Growth Index now outperforming the Russell 2000 Value Index by 1,000 basis points (bps).

Value, Growth, Core…What’s the “Right” Choice?

Based on what we’re seeing in more recent index behavior, trying to time the shift between value and growth could carry with it a significant opportunity cost and the risk of being incorrect. Intuitively, one might say, “why not just own all the stocks?,” which could then lead to the Russell 2000 Index: very much the status quo choice. But as we mentioned before, it has never been easier to fine-tune exposure to a market segment through the use of factors.

Over the long term, did Size or “Size-Plus” lead to outperformance?

Continue Reading…

Early Retirement: It’s a Lifestyle, not a Vacation

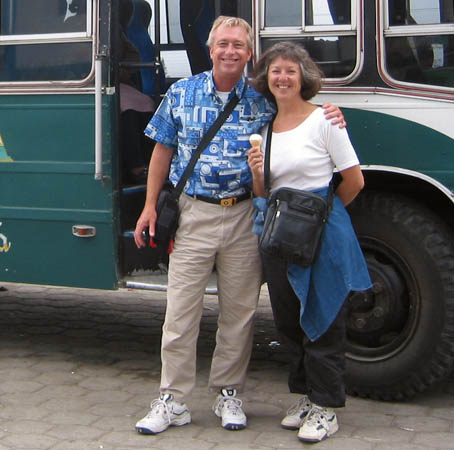
Billy and Akaisha in the Highlands of Ecuador

By Akaisha Kaderli, RetireEarlyLifestyle.com

Special to the Financial Independence Hub

Ever wonder how it was for us in the beginning of living life without a paycheck?

In 1991, we understood that we were retiring with the idea that we would not be returning to work. If we had to, we would, but it was not part of the plan. We were not taking a break from work, we were leaving the working world all together. It was a little unnerving to be making such a clean break because we were out on our own with little emotional support from family and friends. Our retirement at age 38 challenged the belief systems of everyone we knew.

Important points

After all this time, the most important thing we want our Readers to know is: Don’t let anyone destroy your dream. Learn to be self-sufficient and self-motivating and you can create the life you want to live. If you desire something strongly and it makes you happy, don’t look to others for approval. Move in the direction of your dream.

Additionally, we want to inform you of the value of tracking spending. We’ve tracked our spending since our early years of owning a restaurant when we were in our 20’s. This has given us a sense of control over our finances and that brings self-confidence. If you track your spending you always know where you are financially, and if you know your net worth you can calculate what percentage you are spending. A rule of thumb is to keep your spending at 4% or below of your invested capital. If the market changes or your life circumstances change, knowing where you are with your money output is priceless.

What we wanted to achieve

Above all else, we wanted our freedom.

We had been working 60-80 hour work weeks with very little personal time or time with family and friends. While we consider ourselves to be productive people and we loved our jobs, this amount of time focused on work began to feel like a grind. I am sure many readers understand this feeling as we were not unique. We longed for large stretches of time before us that were unstructured so we could do as we wanted, when we wanted. So we traveled, read books, took classes, played music, took photos, and met new people – all on our own time schedule.

This pleased us greatly.

The greatest lessons we have learned Continue Reading…