All posts by Financial Independence Hub

Your (last) greatest show on earth

By Heather Compton

Special to the Financial Independence Hub

What do you envision when it comes to your final wishes? Would there be a formal service? If so, who would officiate? Do you wish to be cremated or buried or donate your remains to science?

I get it, end of life conversations are difficult and even if you are prepared to have the discussion, dollars-to-donuts your kids or responsible family members don’t want to go there.

Regretfully I’ve been involved with funeral planning for a number of relatives, and even some clients, and these are the decisions families find most difficult. When the time comes —  and it will —  the question inevitably asked is some variation of “What do you think mom would have wanted?”

If those closest to you know your personal wishes they don’t have to make it up in the funeral director’s showroom while debating between the grand showcase coffin and the budget version you might have preferred!

Bless Mom — she was very clear — cremation by the most frugal means possible, and a nice lunch for our friends.  My Scottish depression-era mother liked the memorial society option because they negotiate funeral cost discounts.

The Memorial Society Association of Canada’s website identifies contacts across the country. A modest membership fee gets you an information package to help document decisions plus they pre-negotiate cost-conscious plans with funeral homes. You can file your wishes with the funeral home or with a memorial society but keep a copy with your other important documents.

Fire Drill Conversations

Because these are difficult conversations, I suggest you treat them like a fire drill: keep it short, discuss what’s needed, make sure everyone understands, document and call it done.  Have another fire drill if your thoughts or wishes change.

Here goes:

► Style of service Continue Reading…

What to do and not to do when with your IRA

By Sia Hasan

Special to the Financial Independence Hub

If you have decided to invest in a self directed IRA (Individual Retirement Account: the American equivalent of Canada’s RRSP), you have taken the first step to enjoying a better financial future and to preparing for peace of mind in retirement. However, simply opening an IRA account is not all that it takes to benefit from this type of retirement account. If you want to maximize the benefits of your IRA fully, follow these helpful tips:

Choose the right type of Retirement Account

There are several types of IRA accounts that you can open, and two of the most common options are a traditional and Roth IRA. There are significant differences between these accounts. By learning more about these differences, you may be able to find the account type that is best for your financial planning efforts.

Both have similar contribution limits, but a Roth IRA uses money that has already been taxed as contributions. When you withdraw the money after you reach age 59 and a half, you can enjoy tax-free distributions. A traditional IRA, on the other hand, uses pre-tax dollars as contributions, and the money is taxed at a later date when you withdraw the funds. Depending on your current tax rate and your projected tax bracket in retirement, you may find one of these options to be far more useful than the other.. For example, if you expect to be in a lower tax bracket in retirement, a traditional IRA may be a better option for you because it minimizes your tax liability.

Maximize your contributions

If you want your account balance to grow at the fastest rate possible, you should make regular contributions into it each year. More than that, you should maximize your contributions annually to fully take advantage of the tax benefits associated with the account. Any additional investment funds that are available can be invested in another tax advantageous account or in a non-investment stock account.

Be aggressive in your younger years

With a self-directed IRA, you are in complete control over how your funds are invested. This means you can choose to take less risk or more risk. While taking more risk may sound unwise, the reality is that riskier investments generally have a higher return. In your younger years when you have decades before retirement, you can more comfortably take these risks with your investments. When risks are intelligent and moderated, you can grow your nest egg substantially in the younger years of your adult life. Then you can comfortably reduce your risk and return later in life without negatively impacting your financial security in retirement. Continue Reading…

End the year with your taxes in order

By Lisa Gittens, H&R Block

Special to the Financial Independence Hub

At this time of year, you’re likely occupied with decorating for the holidays, cooking an abundance of food for family, and selecting gifts for your Secret Santa exchange. Amidst the placing of ornaments, stringing of lights and baking of cookies, taxes are probably the last thing on your mind: they’re something you’ll think about next year, when you’re reminded it’s officially tax season.

But, believe it or not, the end of a calendar year is the perfect time to review the current state of your filing and get your taxes in order before flipping the page to 2018. To help you do just that, H&R Block offers these tips:

Agendas make great friends

Treat yourself to the gift that keeps on giving: an agenda. With this new friend in tow, you can take advantage of sporadic free time and update it with all relevant tax-related dates so they don’t sneak up on you in 2018. Examples of entries you’d want to include are: February 26, 2018, which marks the day the Canadian Revenue Agency officially opens.

(As a side note, this is actually the latest opening in Canadian history and means Canadians will have a shorter window to file taxes.) April 30, 2018 is another date to keep in mind: it’s the deadline for filing 2017 personal tax returns. (If you’re self-employed, the deadline is June 15, 2018.)

Organization is in style

Hopefully you’ve been saving bills, tuition receipts, transit passes, charitable contribution receipts, health expenses, and other key tax documents this year. When it comes to your tax return, it literally pays (in the form of a tax return!) to retain and organize these documents. Like agendas, accordion-style folders with tabs to separate by category are great gifts to yourself. Just ensure you keep it in reach — and out of harm’s way — so you’ll be more motivated to use it throughout the year. Continue Reading…

Rekindling our inner creativity and frugality this Holiday season 

By Maria Weyman, creditcardGenius

Special to the Financial Independence Hub

Gifts, parties, drinks, and yes … food! Is there a more expensive time of year than … now?

Staying on the straight and narrow road of financial responsibility means we can’t go about our lives like a zombie (oh wait, wrong holiday )…

But how do we stay frugal (yes, I’m using the F word), and keep fun within arm’s reach?

It’s all about creativity

… not sacrifice.

So, don’t worry, I’m not going to ask you to create two separate lists for needs and wants. Instead, let’s stick with one master list: where you list your full holiday needs and wants.

Now, here’s the thing. At the bottom of your list, write the max dollar amount you plan on spending for everything. But before you write that single number down … a little research would help, like:

How much disposable money –- after your fixed expenses and savings goals –- do you have in the bank?

(No, your credit card limit doesn’t count.)

Working with that single number –- your maximum budget –- it’s time to break it down into chunks depending on what’s in your list. Now we’re cooking.

You’ll feel a little bit of tension. An internal struggle when you’re deciding how and where to allocate your holiday spend. Completely normal. That just means our brain is getting warm and prime to let our creative juices flow. Because here’s a not-so-obvious secret:

Constraints and limitations drive creativity.

Make it a game

Because games are fun. And at its core, aren’t games all about solving problems and overcoming specific challenges?

Even more fun when you get to save, indulge yourself, and spoil the people you love in the process. And here’s the best part:

You get to create the rules.

Here are some questions and suggestions:

Review your list

When you review your list…

  • Is there anything that you can get pre-loved (say hello to Kijiji, Craigslist, and even Facebook)?
  • Is there anything that you can create yourself (using a little help from Pinterest and YouTube)?
  • Is there anything that you can borrow from friends and family?
  • Is there something that you can replace with something that is just as good or better?
    • Example: if you’re thinking of getting your bff that beautiful warm $50 scarf, how about a) inviting her over for home-cooked dinner?, or b) volunteer to watch over the kid(s) for an afternoon so she can have a “me time”?

Anytime you can DIY [Do it Yourself], borrow, replace or get something pre-loved…write down how much you’re saving. Obviously, the bigger the number, the bigger the genius you are.

What’s at stake? Well, that’s for you to decide.

Free is fun

Let’s stop and think about all the free things we’re getting online; amazing isn’t it?

So, back to your list. Is there anything you’ve listed that is available for free? Some ideas …

  • Free local events: Check Eventbrite for current and upcoming local events, some have tickets for sale and some are free.
  • Free stuff. Browse Kijiji and Cragslist free stuff and see if there’s a match on what’s on your list.
  • Other freebies: like games, baby stuff, etc.

7 DIY gift ideas

Ideas from easy to advanced …

  1. Personalized christmas tree ornament: grab a box of blank-canvas ornaments from the dollar store, markers, and stickers … and have fun!
  2. Vanilla infused vodka for baking, etc.: Better alternative than that boring store-bought “vanilla extract” (cheap vodka is welcome).
  3. Chocolate spoon mixer like this one is delish.
  4. Ready-to-go hot cocoa and marshmallow in a jar: drool-worthy ideas here.
  5. Homemade chocolate and caramel dips: you can find glass bottles at the dollar store and recipes for chocolate and caramel dips are abundant.
  6. Decorated candle holder. You can go from simple elegance to elaborate, some ideas here.
  7. Festive painted glassware: Grab a (wine) glass (you guessed it, from the dollar store), enamel paint (specific for glasses), paint brushes, and … some inspiration! The best news? Sky’s the limit to your pattern and design.

These ideas are by no means exhaustive, but I hope it’s a good starting point to get you thinking of the possibilities.

The bottom line

Gifts, parties, drinks, and yes … food.

We’re entering a time where abundance and indulgence are celebrated. And while, no doubt, there are worse things in the world, over-indulgence only feels good for a moment.

So let’s make sure the reality we come back to after this holiday is a happy one for you and your wallet.
Maria Weyman is Co-Founder of creditcardGenius, the only tool that compares 50+ features of more than 150 Canadian credit cards using math-based ratings and rankings that respond to your needs, instantly. Follow on Twitter and Facebook.


 

How to graduate debt-free from College

By Steve Barker

(Sponsored Content)

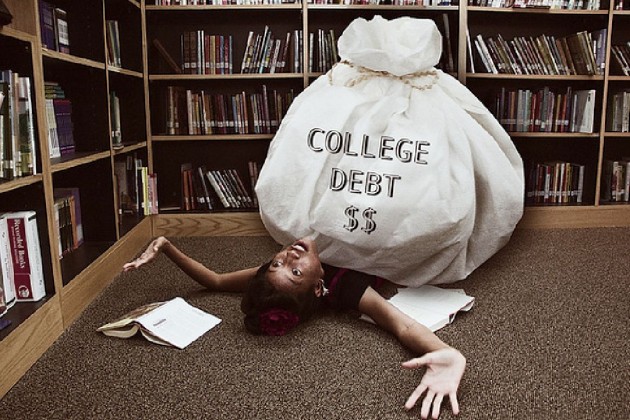
Many high school students are faced with the prospect of going into tens of thousands of dollars in debt or foregoing higher education. Today’s young people are having to look at a college education as an investment and to weigh the value of that investment against potential returns.

There are ways to stay out of debt and still earn a college degree: it just requires a little planning and patience.

Advantages of Going to College

The cost of tuition is steadily rising without the accompanying rise in income. Although there are many paths to success, a college degree does greatly increase job options, teach valuable skills, and create lifelong networks of friends and colleagues. Here are some reasons why college is still worth the cost.

  •       Increased pay: Even though incomes aren’t rising with tuition costs, college graduates still tend to make more than their non-schooled friends. College grads earn an average of 56 per cent more than high school graduates.
  •       Higher rate of employment: The job market is extremely competitive. Anything that gives you an edge should be considered. Some studies show that only 3.8 per cent of college grads are unemployed compared to 12.2 per cent of individuals with only a high school diploma.
  •       Networking opportunities: You are likely to make a lot of valuable connections while attending school. You are introduced to people with new ideas who have the potential to inspire, encourage, and challenge you. Your professors and peers may become vital connections as you enter the workforce.

Staying Out of Debt

There is more than one way to earn a diploma. Taking out student loan debt is not the only way to finance your education. Continue Reading…