All posts by Financial Independence Hub

Do men and women have different Savings Habits?

By Danielle Kubes

Special to the Financial Independence Hub

In an online survey about savings habits, financial comparison site Ratehub.ca reports that although Canadian men and women save almost the same amount of money, men have a greater level of confidence in their financial planning.

Inspired by 2014 Statistics Canada data that says Canadian women have lower financial literacy scores than men and were less likely to consider themselves “financially knowledgeable” (31% of women versus 43% of men), Ratehub.ca set out to discover if there truly is a gender divide. 

The company digitally surveyed a random sample of 1,087 Canadians in November, with respondents self-identifying their gender.

“Our survey revealed that while men and women differ in aspects of their financial planning, at the core, their personal finance goals and concerns are nearly identical,” the report says.

Both genders have similar financial goals

Indeed, both genders report almost the exact same financial goals. At the top of list of priorities is retirement, followed by travel and then having an emergency fund.

Both men and women prefer to save and invest in registered accounts, especially the registered retirement savings plan (RRSP) and tax-free savings account (TFSA). What they choose to invest in within these accounts — guaranteed income certificates (GICs), exchange traded funds (ETFs), stocks, or other products — is unknown.

Yet men and women diverge most in how confident they are that they’ll have enough money to retire: less than half of women, 41%, say they’re confident compared to over half of men surveyed, at 56%.

Odd, because both genders save almost the same amount of their salaries, with women saving 26% and men 29%.

The gap could potentially be explained in how able they are to grow those savings through investing. Eighty-five per cent of men invest their money, while only 76% of women do.

Of those that do invest, less women than men self-manage their investments, potentially indicating another worrisome lack of confidence in their financial knowledge.

This is supported by the original Statistics Canada data, which found women were less likely to state they “know enough about investments to choose the right ones that are suitable for their circumstances.”

Confidence doesn’t mean financial knowledge

But does confidence translate to actual financial knowledge? Apparently not. When Statistics Canada quizzed Canadians who rated themselves financially literate, one in every three women failed, while one in every four men failed. Continue Reading…
TREB vows to take battle over housing market data to Supreme Court

By Penelope Graham, Zoocasa

Special to the Financial Independence Hub

Real estate consumers will have to wait a little longer to access transparent housing market data: the Toronto Real Estate Board (TREB) has vowed it will take its fight to keep such information private all the way to the nation’s highest court, in response to losing its latest appeal.

The Federal Court of Appeal has rejected the real estate board’s arguments that the sharing of its database would violate both its copyright and home sellers’ privacy. It contains extensive details on past sold homes, including their asking versus sale prices, the length of time they lingered on the market, as well as the commissions earned by real estate agents.

Currently, agents can only divulge this info directly to their clients; posting it publicly on a website or emailing it to a subscriber base has been prohibited by TREB (and it has aggressively shut down past attempts to do so, including Zoocasa’s past solds emails in 2015).

Challenging Information gatekeepers

However, restricting this data was challenged by the Competition Bureau of Canada, which took TREB to the Competition Tribunal in 2011. After the case was initially dismissed and appealed, the Bureau won in 2016 (a decision immediately appealed by TREB).

The Bureau successfully argued that withholding the data was not only to the detriment of consumers, but hurt the business models of virtual online offices (VOWs for short, referring to online real estate brokerages).

The Appeals Court upheld this ruling last week, saying TREB’s database did not qualify for copyright protection, and throwing out their privacy argument. While based around the Toronto real estate market, the implications could be nationwide, setting an important precedent for how all real estate boards collect and distribute data. Currently, only Nova Scotia releases it in Canada, though it is common practice in the United States.

Better data benefits consumers

Lauren Haw, Zoocasa’s Broker of Record, says better access to sold data will help consumers make educated decisions when buying or selling real estate. For example, having access to comparable solds records can help buyers determine whether a Toronto townhouse, condo or detached home is fairly priced.

“The ability to share and display market data (such as past-sold prices) with consumers is a positive development for the real estate industry,” she says. “We strongly believe in a model where consumers are educated and able to work with experienced agents that act in an advisor capacity: not as gatekeepers of information.”

Continue Reading…

How high investment fees can diminish Investment Returns

By Chris Ambridge, Transcend

Special to the Financial Independence Hub

The objective for most investors is to earn value-added performance. Unfortunately there are fees and other costs that can diminish investment returns. The reality is that the costs associated with investing in these products can lead to underperformance when measured against industry standard benchmarks.

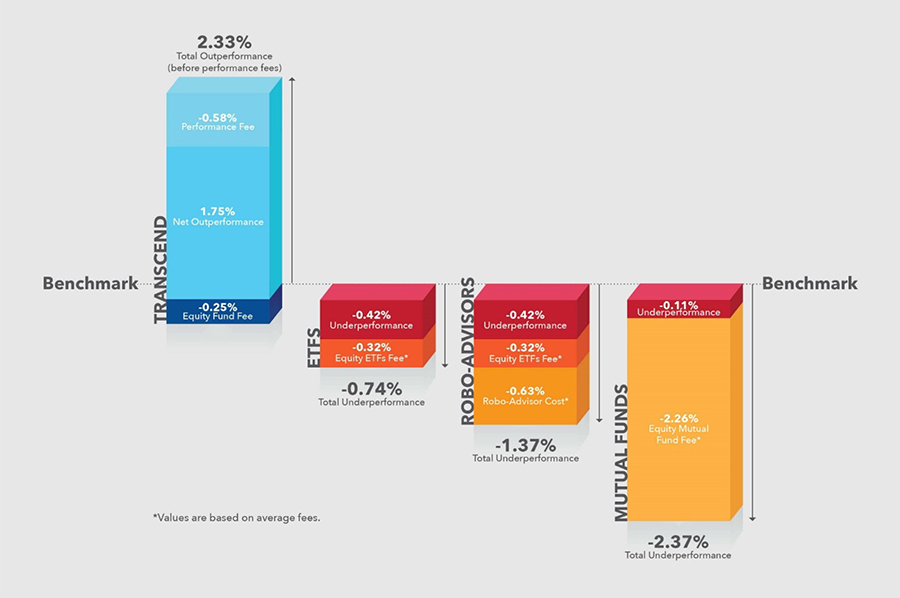
The above chart shows the average annual fees and their impact on investment performance for Equity Mutual Funds, Exchange Traded Funds (ETFs), robo-advisors and Transcend’s Pay-for-Performance™ model. This is illustrated by comparing their returns against a benchmark. The benchmark is a universally accepted representation of a particular stock market that is used to measure the performance of a portfolio manager.  For example, a benchmark for Canadian equities is the S&P/TSX and a benchmark for U.S. equities is the S&P 500.

Ultimately, excessive fees reduce clients’ investment performance and hampers their ability to reach their financial goals.

While ETFs and robo-advisors are gaining in popularity, mutual funds are still the prevalent investment product for retail investors despite numerous studies that have confirmed the weak investment returns of equity mutual funds relative to their benchmarks. In Canada, a fairly new approach developed by S&P Dow Jones Indices called the SPIVA Canada Scorecard confirms performance failings. The latest result based upon five years of data ending December 2016 confirms that equity mutual funds have underperformed their benchmark, often because fees have such a negative impact on the overall portfolio results.

Mutual funds can charge management fees as well as administrative costs and custodial fees. They can also charge clients for trading, legal, audit and other operational expenses. In the chart above, these fees plus investment related underperformance add up to the average true cost (-2.37%) of investing during the last five years for equity mutual funds.

Even low-cost ETFs, which are designed to mirror a benchmark, tend to disappoint. The performance lag can be tied to the level of fees of 0.32%, plus trading and rebalancing costs as well as a potential cash balancing drag of up to 0.42%, based on 2015 data from the Management Reports of Fund Performance (MRFP) found on the SEDAR.ca website. This analysis does not include the negative impact of brokerage costs to buy and sell, and potential custodian or registration fees. With that in mind, the chart reveals that ETF investors underperform the market appropriate benchmark by -0.74%.

Robo-advisors to the rescue?

Another relatively new entrant to the low cost investment marketplace is the robo-advisor. Employing several common assumptions such as an average portfolio size of $50,000 and trading costs of 0.2% per year, it can be determined that the average robo-advisor fee in Canada is 0.63%.

This cost shows that it is more efficient than traditional wealth management fees, but still lags behind the Pay-for-Performance™ model. While everyone is talking about robo-advisors, the true question should be about getting value for your money and how much fees can impact actual outcomes. Continue Reading…

John Bogle’s 7 tips for successful investing

Vanguard founder John C. Bogle

Investing is not a one-way ticket to riches. Both novice and expert investors have periods of good and poor performance. Success or failure is driven largely by the markets, but how we behave also has a huge impact.

In a recent article for Financial Analysts Journal, Vanguard founder Jack Bogle summarized the rules for successful investing he developed over his 65-year career. They’ve been tried and tested through different market conditions, and we’re reproducing them here so everyone can potentially benefit.

1.) Invest you must

The biggest impediment investors face is not market volatility, but not investing in the first place. History shows that investing — as opposed to simply saving — is necessary to generate a reasonable return over the long run.

2.) Time is your friend

Investing is a virtuous habit best started as early as possible. Thanks to the “magic” of compounding (simple math, really), even modest investments made in one’s 20s can grow to surprising amounts over the course of an investment lifetime.

3.) Impulse is your enemy

Eliminate emotion from your investment programme. Have rational expectations for future returns, and avoid changing those expectations in response to the ephemeral noise coming from Wall Street. Understand that what may seem like unique insights are typically shared by millions of others. Continue Reading…

What does tax reform mean for high-yield debt?

By Bradley Krom and Josh Shapiro, WisdomTree Investments
Special to the Financial Independence Hub

In an earlier post, we highlighted the likely impact tax reform could have on investment-grade (IG) corporate debt. In part two, we turn our attention to the high-yield (HY) market.1 While a reduction in taxes should benefit all profitable companies, other provisions could lead to tough choices for some less-credit-worthy borrowers. As we’ve seen during the most recent earnings season, HY still presents a mix of opportunity and risk. Below, we highlight the contrasting impact of lower tax rates and potential changes in the deductibility of interest expenses.

Big Picture: lower taxes, higher free cash flow and earnings

On net, the proposed tax plan is a positive for high yield. Lower statutory tax rates should result in higher profitability metrics, greater free cash flow and a boost to economic momentum/growth, while extending the credit cycle. While all businesses won’t be impacted the same way, we feel comfortable concluding that tax cuts should bias credit spreads tighter for riskier borrowers, on average. Similarly, an increase in economic growth could also push nominal interest rates higher.

What about Revenue Offsets?

While the top-line impacts we highlighted above should be broadly positive, we believe other elements of tax reform warrant closer attention: most notably, the so-called interest deductibility provision.

In the current environment, companies choosing to finance themselves with debt are permitted to fully deduct interest payments. As a result, companies have an incentive to finance themselves with debt as opposed to equity. In order to help dampen the fiscal impact of tax cuts on the federal budget, the current proposal would limit the deductible amount of interest expenses to 30% of EBITDA.

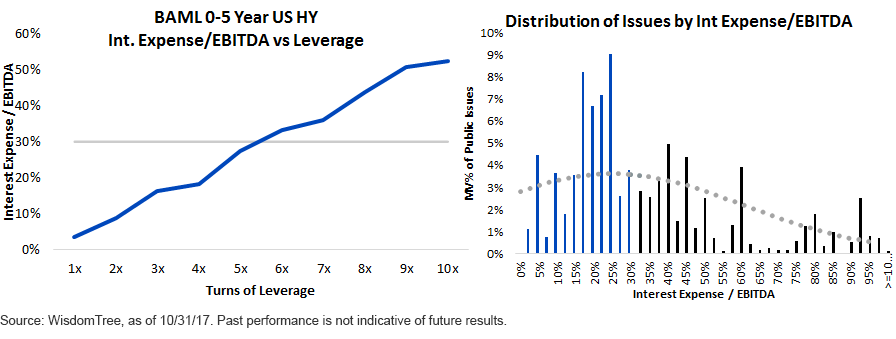
Fundamentally, this provision should have a much greater impact on the HY market. Given that risky borrowers tend to pay higher interest rates and (all else being equal) tend to deploy more leverage, the 30% cap on deductions should impact a larger percentage of the market. As we show in the chart below, HY companies with leverage of approximately 5.5x would likely be unable to fully deduct their interest expenses. In the second chart, we show that this makes up approximately 40% of the total market.2

Market Impact

While attempting to draw broad-based conclusions about individual companies can be tricky, a few key points stand out. In our analysis of firms with public financials, we estimate that 91% of CCCs will be unable to fully deduct their interest expenses. Continue Reading…