All posts by Financial Independence Hub

Millennial Money: Can Money buy Happiness?

By Brandon Hill, CFP

Special to the Financial Independence Hub

Do you believe the saying money can’t buy you happiness? Most people laugh at that notion, while some of the wealthiest people sing its praises …

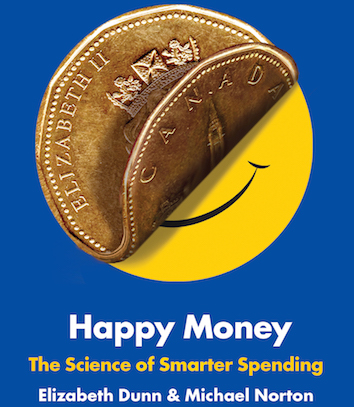
I recently read a book called Happy Money: The Science of Happier Spending by Elizabeth Dunn and Michael Norton.

The book set out to tackle the question – “Just because money often fails to buy people happiness, does that mean that it can’t?”

Luckily it can:  it just depends on how you go about spending it. It turns out that our everyday spending choices releases a variety of biological and emotional effects – either positive or negative.

This book covers five specific spending strategies to spark positive effects and increase happiness. You may have heard of some – such as buy experiences, not “things.”

The goal is to maximize the amount of happiness you get out of every dollar you spend.

Some of the wealthiest individuals have mastered these tactics (Bill Gates / Warren Buffett) and don’t let their wealth become a source of anxiety or stress.

It’s important to note that these ideas aren’t supposed to encourage you to spend your way to happiness. All strategies are meant for your discretionary spending, after your needs and future savings goals are taken care of (see my previous article on Guilt-free Spending).

All of the ideas written about here are completely attributable to the authors of this book and include paraphrased ideas and/or direct quotes from the authors. I don’t take credit for the concepts written here. The full book is a quick read and if you are interested in reading more in-depth, you can buy a copy here.

Buy Experiences

A study found out that once an individual makes $75,000 or more (in the US), any increase in income has no effect on their everyday general happiness. Isn’t that crazy?
Continue Reading…
Can I afford to Retire?

The following is the second excerpt from Create the Retirement You Really Want: And Retire Smarter, Richer and Happier

By Clay Gillespie

Special the Financial Independence Hub

It was a beautiful May morning when I next saw Rachel and Mike. Rachel was carrying a large gift-wrapped box.

“This is for you,” she said, smiling and handing the box to me.

“Thank you,” I said, pleasantly surprised. “Most of my clients wait until they see how their portfolio performs before expressing their appreciation.”

“Shall we take it back then?”

“No, no! I’ll keep it,” I said, smiling, as I began to slide off the ribbon and remove the wrapping.

I opened the lid, looked inside and grinned with pleasure. “Much appreciated,” I said, looking proudly at a genuine leather soccer ball with my daughter’s name custom-printed on the top panel. “Sarah’s going to love it!”

“We wanted to give you a memento of our first meeting,” Rachel said.

“How very appropriate. Well, I don’t have a soccer ball for you,” I said, putting the ball down. “But hopefully I have an equally useful gift.”

“One that will last a lifetime?” Rachel asked.

“Yes. You might say it’s a gift that keeps on giving,” I said, grinning and handing them each a file folder.

“Our retirement numbers?” Mike asked.

“Yes. These are your illustrations.”

“Will we need to eat cat food?” Mike asked with a smile.

“No.” I laughed. “My goal is to help you maximize your retirement income, not minimize it.”

“And we won’t outlive our money?” Mike asked, more serious now.

“You should have plenty left for your children, unless you live to be Methuselah’s age.”

“Methuselah lived to be 969 years old,” Rachel said. “So I think the odds of that happening to us are slim,” she said pointedly.

“Right. My mistake,” I admitted. “I’ve taken the liberty of including a life expectancy table in your retirement illustration, so you’ll know the odds.”

“The odds of us dying at a certain age? I’m not sure I’m ready to see that!” Mike said uneasily.

“Don’t be such a worrywart, Mike,” Rachel said, chiding him gently. “It’s not as if you’re going to see the exact date and time of your death.” Suddenly, she frowned and looked at me. “Are we?”

“No,” I said smiling. “The actuaries aren’t that good, at least not yet. The life expectancies I’ve included are estimates based on a number of factors including your current age, your diet, exercise frequency, stress, body fat, genetics and the quality of health care.We’ll get to those in a moment. What you’re about to see is a financial illustration. It’s designed to give you an initial picture of your retirement situation for planning purposes. But first, we need to review your finances together so we’re all on the same page. Agreed?”

“Agreed,” they said together.

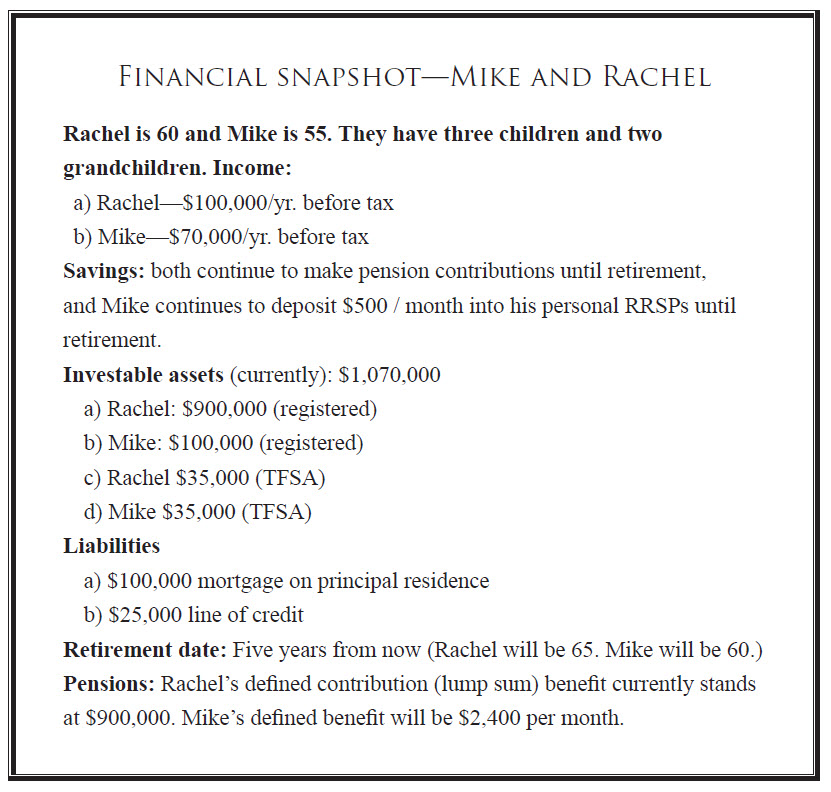
“Good. Here’s a quick snapshot of your current finances. As we go through it, I want you to let me know if anything is amiss.”

This is what they saw:

“As you can see, your gross income is $170,000 per year, while your combined income after tax is approximately $125,000.” “We work hard for our income,” Rachel said defensively.

Continue Reading…

Do you believe in the Inflation Bogeyman?

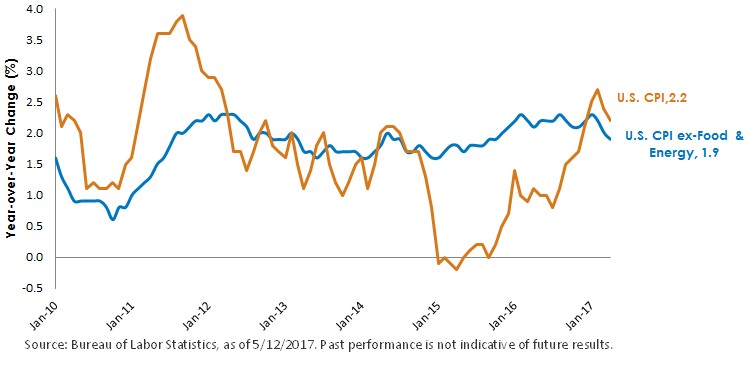
U.S. CPI vs. U.S. CPI ex-Food & Energy Year-over-Year Change from 1/31/2010 to 4/30/2017

By Kevin Flanagan, WisdomTree Investments

Special to the Financial Independence Hub

One of the lynchpins behind the Federal Reserve’s (Fed) decision-making process thus far in 2017 has apparently been the altered inflation landscape. The policy makers seem to be more comfortable that deflationary conditions have passed and that inflation will be “running close to the Committee’s 2 per cent longer-run objective.” Does that mean that fixed-income investors should be fearful of the inflation bogeyman rearing its ugly head anytime soon?

Calendar year 2017 did get off to a somewhat unexpected start on the inflation front. Indeed, the Consumer Price Index (CPI), perhaps the most widely followed gauge on price developments, revealed some visible upside during the winter months. According to the Bureau of Labor Statistics (BLS), overall CPI rose as high as +2.7%1 in February on a year-over-year basis, the strongest performance in five years.

In fact, as recently as July of last year, the figure came in as low as +0.8%2. The Fed’s preferred measure of inflation, the price index for personal consumption expenditure (PCE) exhibited a similar pattern, coming in at a five-year high watermark of +2.1%3 and crossing the FOMC’s mentioned 2% threshold in the process.

Core inflation slowing

Interestingly, inflation has not exhibited any further upward momentum in the months that followed. To provide some perspective, the year-over-year gains for CPI and the PCE price index have since dropped back to +2.2%4 and +1.8%5, respectively, in the latest data available. Continue Reading…

Why Baby Boomers should stay on top of Medical Device Recalls

By Cher Zevala

Special to the Financial Independence Hub

Today, there are nearly 80 million Americans over age 65 — and that number is expected to double within the next 30 years.

Such an increase in the number of older adults, many of whom have more active lifestyles than previous generations, along with advances in technology, means that the medical device market has grown exponentially along with the population. More people than ever before are relying on medical devices, such as artificial joints, cardiac devices, and other advances to stay healthy and active longer than they otherwise might have.

With the expansion of the medical device market among older adults, though, there is also some concern. Although the overall number of medical device recalls is down almost 30 per cent since 2014, recalls are still something to be concerned about. Class I recalls, in which there is a high risk of the device causing serious injury or death, are thankfully the rarest, but the most common type of recall, Class II, still carries some risk. A Class II recall is issued when a device has a chance of causing a serious health problem or injury, but can be fixed. Class III recalls are only for those devices that have no chance of causing injury or death, and are also quite rare.

Of course, judging by some of the headlines and television commercials that we see all the time, it seems like medical device recalls are quite common — and that anyone who has ever used certain devices, some of which are very common among Baby Boomers, is not only at risk of imminent death, but also entitled to significant compensation. There are certainly cases in which compensation is warranted, but before it gets to that point, it’s important for individuals to stay abreast of recalls to protect themselves.

The Trouble with Recalls

In most cases, recalls are issued voluntarily by medical device manufacturers; rarely does the FDA order a company to issue a recall. When the decision to recall is made, the company needs to notify affected individuals. This isn’t always as easy as it sounds.

Continue Reading…

Money strategies for the sandwich generation

By Scott Evans

Special to the Financial Independence Hub

If you’re busy raising kids and supporting your parents too, you’re not alone. Statistics Canada reports that over 700,000 Canadians aged 45 to 64 are splitting their time and money caring for their children and parents. If you belong to this sandwich generation, it can be a difficult balancing act.

Everyone’s circumstances are different and your priorities will reflect that. Maybe you have a young family, a mortgage and parents nearby who require occasional assistance. You might be saving for your children’s education, paying down debt and setting aside a few hours each week to help your parents.

Or, perhaps you’re close to being debt-free, but have parents living far away with little saved and have just had an adult child move back in. You’ll likely be directing some of your income to parental care and asking your child to chip in at home.

Whatever your situation is, planning ahead can go a long way to easing emotional and financial strain.

Helping out your parents

Understanding your parents’ needs and resources is the first step to managing a sandwich situation. Here are some topics to explore with them:

Financial inventory

Gain an understanding of your parents’ assets, income sources, living expenses and debts. If they have pension income, substantial home equity and are otherwise debt-free, the options might be quite different than if you have to support them financially. Also, know where important documents are kept so you can access them if necessary.

Living arrangements

Some people look forward to downsizing when they retire, while others want to stay put. Either way, there are ways to unlock home equity to fund living and care expenses, or invest for income. Continue Reading…