All posts by Financial Independence Hub

U.S. Treasuries: Who’s buying, who’s selling?

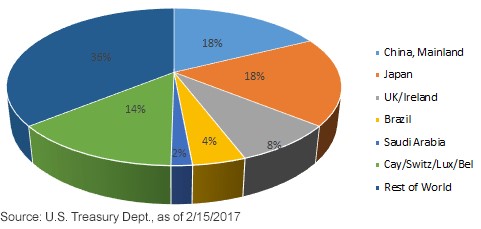
Major Foreign Holders of U.S. Treasuries Dec. 2016

By Kevin Flanagan, Senior Fixed Income Strategist, WisdomTree

Special to the Financial Independence Hub

One of the linchpins supporting the U.S. Treasury (UST) market in recent years has been the relative yield advantage against the rates that have existed among the sovereign debt of other G7 nations. In the post-U.S. presidential election landscape, fixed-income investors have witnessed a back-up in G7 government bond yields on a global basis, and questions have arisen as to whether said advantage would remain a key contributor to the UST market outlook in 2017, now that the “zero rate club” has shrunk. The best way to answer this query is to examine just who exactly has been buying and who’s been selling, with the first data point looking at developments from the foreign perspective.

Each month, the Treasury Department releases statistics on this front, but it should be noted that the actual data are provided with a one-month lag. Thus, the latest report did not provide any fresh details on how 2017 got started, but it does offer interesting information for calendar year 2016. The report itself is called Treasury International Capital data, or TIC, as it is known in fixed income trading circles, and includes the figures for “Major Foreign Holders of Treasury Securities.” Continue Reading…
On the Middle Class & paying one’s fair share of taxes

By Tim Paziuk

Special to the Financial Independence Hub

The Liberal Government has stated it wants to build a strong middle class, but who comprises the middle class?  Mr. Morneau in his 2017 budget speech stated, “All Canadians must pay their fair share of taxes,” but what is a “fair share”?  Does fair share mean the total amount of taxes one pays as a percentage of their gross income?  Is this based on an annual consideration or a lifetime consideration?  Or does fair share mean positively contributing to the general revenue?

The answer to the first question is an ongoing contentious debate.  According to former Finance Minister Mr. Joe Oliver, the middle class could include households earning as much as $120,000.  Given research completed by MoneySense Magazine[1], the middle class could include households earning incomes ranging from $38,800 to $125,000 (average second, third, and fourth quintiles for Canadian households), but this varies considerably between Provinces and Territories, and even between cities.  But does owning a private corporation automatically exclude you from the middle class?  The continued witch hunt on private corporations by the Liberal Government would indicate this is the case since it directly contradicts their mandate to build a strong middle class.

Comparing a private-sector and public-sector worker

It is at this time I would like to introduce Sally.  Sally could be a physician or accountant, an engineer or architect, a therapist or life coach, or a hairstylist or clothing retailer.  Suffice to say that either out of choice or necessity, she is self employed.  Let’s make her a plumber who is in a position where it makes sense for her to incorporate because she can defer income within her corporation and income split with her spouse under present tax legislation.  Her spouse works part-time.  Their situation can be summarized as follows:

  • Sally’s taxable corporate income: $100,000
  • Spouse’s gross income: $25,000
  • Net income required to meet their lifestyle: $80,000
  • Spouse’s CPP income: $4,300

Continue Reading…

Men and women approach taxes & investing differently

By Gennaro De Luca

Special to the Financial Independence Hub

Anyone who is in financial services, and especially wealth management, knows there are big differences between men and women in terms of how they invest. But what isn’t as well known is that there are also big differences between men and women when they do their tax returns.

I started working at a bank at the age of 19, have been in financial services since 1990, and have spent the past 18 years in wealth management. But I also have a company that specializes in doing tax returns for small businesses, families and students. All this experience has provided a lot of insight into how men and women differ when it comes to financial matters.

Let’s first look at tax returns. Nine times out of ten it is the woman who takes the bull by the horns to get the family’s taxes done. Women tend to be more involved and are much more apt to ask questions of their accountant or tax preparer. Men may not ask any questions at all; they just hand over their documents and see you later.

What kind of questions am I talking about? Women want to know things like this:

  • What kind of tax credits are we eligible for?
  • Are there any government benefits we are eligible for?

That latter point is especially important for women who have small children. Indeed, many young families are really squeezed nowadays, so every opportunity for a tax break is vital.

Here is a perfect example from a client that illustrates what I mean. The woman is a teacher who could claim certain expenses for driving her car to work. Her husband is not a teacher, but does work for an employer. She asked us if her husband is also eligible for this same deduction because, like her, he drives a car for his employer and has lots of expenses.

As it turned out, he was eligible for what is known as a T2200, which is a declaration of conditions of employment –- effectively work-related expenses –- and in his case it meant deductions of $10,475, which resulted in a tax saving of over $3,000 on his tax return. But if his wife had never asked the question, none of this would have been claimed.

Men are more resistant to change

Another difference with doing taxes concerns technology. Today more than 80% of tax returns in Canada are done digitally, Continue Reading…

Making Canada great again

By Trevor Parry

Special to the Financial Independence Hub

I have to apologize to my CFL fan friends, particularly in Saskatchewan, where I have found it the rule rather than the exception to find a shrine to the fabled “Riders” in clear site in most offices.  The game just doesn’t do it for me.  The one, two punt monotony of the game isn’t overcome by the stoic resolution to play in Stalingrad like conditions on the Prairie in late fall.

With his second foray into Budget making, Finance Minister Bill Morneau’s attempt must be described as nothing more than a punt.  In this instance they have kicked away the ball to see what the offense south of the border will do.  For fiscal conservatives, who believe budgets should only go into deficit when faced with financial calamity, rather than to send the swag to the long list of Liberal sacred cows, pet projects and friendly consultants, this Budget was more of the same Keynesian dirge, although with veiled threats of further confiscation of wealth.  Certainly Prince Justin and LSE alumni Billy are taking marching orders from the reconstituted politburo to lay low and wait to see what The Donald can get through.

The Trump tax reform package, which despite the recent  (and what I am sure will be a temporary) hiccup in repealing and replacing Obamacare, will likely enjoy complete GOP support and support of Democrats concerned about re-election in 2018,  is the most ambitious tax plan to see the light of day since the days of Ronaldus Magnus.  It puts the Trudeauopian punitive “tax the hell out of everyone who wants to save 10 cents” dictum in definite jeopardy.  It would reduce all tax rates, including the top rate down to 33% from to 39.60%.

Canadian top tax rates kick in at just $200,000, half that of the US

Canadians should know that the top bracket in the US doesn’t kick in until you hit an income of US$418,000 as an individual, $470,700 if you file jointly and $444,550 if you file as a head of household with dependents.  Remember the Little Prince cancelled the miniscule Family Tax Cut ($2k) professing claims of “fairness”.  Canadian top rates kick in at C$200,000.

Continue Reading…

Banks, Blockchain & Economic Liberty: A follow-up

By Adam Goldman

I wrote a piece last September titled ‘Why Our Economic Liberty Depends on the Blockchain’, providing an analysis on why I am certain distributed ledger technology is important to securing our rights under the law in the digital age.

In an ever-increasing realm of technology that is meant to improve (in positive ways) facets of our lives, the imperfection of humanity still exists while greed heavily plagues the banking world. As a firm advocate for the rule of law, I find recent revelations by CBC’s Go Public , that highlighted rampant fraudulent activity occurring amongst Canada’s largest financial institutions (TD, BMO, RBC, CIBC, and Scotiabank) disturbing to say the least.

‘This is why the only solution really is to have government step in and look after the Canadian people.’ says lobbyist Stan Buell as quoted in the CBC article.

Ultimately directives from above led to not only immoral, but also illegal tactics that chased their bottoms lines. Adding more bureaucracy at a government level will only exacerbate the climate.

Blockchain is the answer, not government

In my previous article I had given several broad examples of current institutions that could improve themselves, one being quasi-relevant to the financial fraud currently being exposed in Canada.

Continue Reading…