 Posted By
Merry Christmas from the Hub!


By Billy and Akaisha Kaderli, RetireEarlyLifestyle.com
Special to the Financial Independence Hub
These days, no matter what the topic, the talk is all about sustainability.
In regards to financial sustainability, there are three legs to the stool: income, spending and Investments.
1.) Income
Income is derived from money you make through your job using physical or mental labor or both. Passive income can be created through property rentals, bond interest, dividends and or capital gains from investments.
Increasing income can be done by learning a new skill, getting a promotion, or taking on a better or second job. Maximizing your skills and continued education either formal or on your own is a valuable asset. This could be as easy as teaching yourself about investments in your down time. There are plenty of online tools available to learn this.
Also, don’t rule out that Social Security [or in Canada, CPP and OAS] will be available once you become eligible.
2.) Spending
How much you spend and the debt you carry are two areas that are completely manageable by you. The categories of largest spending in any household are housing, transport, taxes and food/entertainment. Depending where you live, it may make more sense to rent instead of buying a home, or rent out a room in the home you already own, or rent out a subsection of your home in order to help with the mortgage. Putting off that remodel of the bathroom or kitchen, or the re-do of the back yard will also allow you extra money to put into investments.
Regarding transportation, you could walk or bicycle to work, take public transportation instead of owning your own vehicle, car pool or use Uber or a ride sharing service. The cost of car ownership is over $8,000 per year, roughly $650 per month, or $22 per day according to AAA’s 2016 Your Driving Cost Study. How much of your day is spent covering your car expenses, which according to Fortune is parked 95% of the time?
 By Barney Whistance
Special to the Financial Independence Hub
In the wake of a new generation now growing up and planning to settle down, one of the biggest concerns for them is finding a place to live. Finding a house for you and your spouse to live in is one of the most important decisions that you will have to take. Therefore, it should not be taken lightly. There are a lot of factors for you to consider when you set out to purchase or get a house on mortgage. You have to be certain about your choice as you will be the one living with it for a major part of your life.
Your financial situation is the biggest aspect you have to consider when making a decision like that. Once you know your financial point and how much you can afford, you must decide on where you want to live. Planning everything step by step always gets the work done more smoothly and also makes your choice easier.
Finances
Talk about your finances with your partner, so in order to set a budget, you already know how much you both have. Once you have done the initial financial scrutiny, you can decide which plan you should be applying for. Continue Reading…
 By Jo-Anne Wong
Special to the Financial Independence Hub
Post-secondary education is a necessity to get ahead in the new economy, but for many Canadians, attending university is out of reach due to rising tuition costs.
This why it’s now more important than ever for parents to start saving for their child’s education. Thankfully the Government of Canada offers one of the best ways to save for your child’s future through a Registered Education Savings Plan (RESP).
Rising Tuition Costs
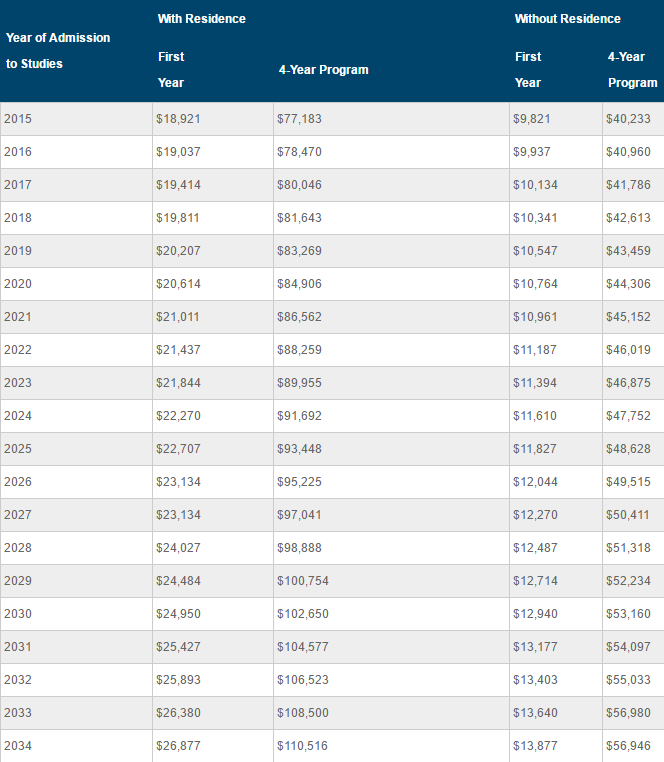
According to Statistics Canada, tuition costs have increased by 40 per cent in the last ten years, and between 2014-2015 and 2015-2016 school years it rose by almost three per cent. The news is worse for parents in Ontario where the average cost of tuition is $8,114: the highest in Canada. If your child chooses to study out-of-province or overseas, fees will be significantly higher. Knowledge First Financial’s Guide to Education Costs in Canada projected that tuition could climb to over $14,000 by 2034. These figures do not account for living expenses. For example, four years of tuition, room and board could add up to $90,000 at the University of British Columbia.
The cost of tuition has been rising steadily over the last ten years and continues to outpace inflation. Compared to last year, students paid on average 3.2% more in tuition compared with the previous year, while the Consumer Price Index was 1.3%. According to Statistics Canada, the national average for university costs in 2015/2016 was approximately $19,500 for students in residence, and $10,000 for Guide to Education Costs in Canada projects that first year tuition could climb to over $14,000 by 2034. These figures do not account for living expenses, students who lived at home or did not have to pay for residence and meals. Students in Ontario have the greatest challenge, where tuition is the highest in the country.
These high costs have resulted in a record-high number of students applying for loans, which is putting them in debt. According to the 2015 survey of 18,000+ graduating university students conducted by the Canadian University Survey Consortium, the average student owed $26,819. Costs are not limited to university degrees, with 37 per cent of Canadians with student loan debt being non-degree students, attending vocational schools or other certificate programs, says Stats Canada.
RESP from Ottawa
By Carlie Weinreb
Special to the Financial Independence Hub
I lectured about RRSPs and TFSAs this November 3rd at the CPA Mastering for Money Conference for 45 minutes. I was a bit nervous because I knew that Former Prime Minister Paul Martin was also speaking. My example was very detailed with lots of Excel spreadsheets.
I then had a sleepover at my friends house the next weekend after dance class. My friend’s parents heard I lectured to over 400 Chartered Professional Accountants about RRSPs and TFSAs. They asked “OK what’s better?” I said “Well, it depends on your income and a couple of other things.” I knew they were not satisfied. I could tell they wanted like a 15 second answer.
The following week I was lecturing at the Canadian Personal Finance Conference presenting on RRSP and TFSAs again but they gave me only 20 minutes. And most recently, I presented on RRSPs versus TFSAs at Microsoft. They only gave me ten minutes.
3 quick rules
