All posts by Financial Independence Hub

Young, saving, and hopefully one day buying a house

IMG_7264By Helen Chevreau

Hub Staff

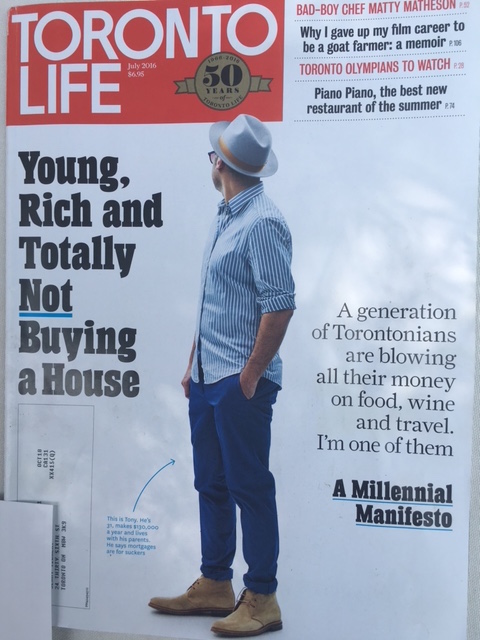
The cover story of this month’s Toronto Life magazine caught my eye straight away. “Young, Rich, and Totally Not Buying a House” it boldly claims.

As a young, not-yet-rich millennial who has no immediate plans to get into the housing market, I was intrigued. The article is written by 31-year-old Tony; a pharmacist who lives with his parents and eschews the traditional rites of passage of his peers, like home ownership.

Before I actually read the article, I was sure I wouldn’t like Tony, wouldn’t relate to him. Growing up in Toronto I’ve seen his type countless times. Money is no object, and he’s not shy to show it. A common defence from this kind of person is that ‘normal’ or ‘rational’ people who are judging him are jealous or boring (or both).

What I found interesting about this piece is that Tony seems very self-aware about his spending and lifestyle choices. He’s accepting of his friends who do choose to be “shackled to a monstrous mortgage for the next 30 years,” and he understands that sometimes it just isn’t possible to have it all.

Though much of what Tony talks about in this article is out of reach for most normal millennials (last minute trips to Asia, $200 bottles of wine), I appreciate the sentiment. Continue Reading…
Is CPP expansion based on myths or facts?

Keith Ambachtsheer Head_Shoulders2_Jan 2016
Keith Ambachtsheer, photo courtesy KPA Advisory Services

By Keith Ambachtsheer

Special to the Financial Independence Hub

“The case for CPP expansion is weak and built on flawed arguments not supported by the facts.” — The Fraser Institute

Five Myths about the CPP

There must be something in the Vancouver air. Reacting to the recent Federal-Provincial agreement to expand the Canada Pension Plan (CPP), our friends at the Fraser Institute have launched another CPP-bashing barrage. It appeared in a June 20 Vancouver Province article under the title “Case for expanding the CPP based on myths – not facts.”

The article explains that there are five CPP myths masquerading as facts. If people only understood that these five things were myths rather than facts  … the plan to expand the CPP would surely be quickly be aborted.

Here are the five purported myths:

  1. Canadians are not saving enough for retirement
  2. Higher CPP contributions will increase overall retirement savings
  3. The CPP is a low-cost pension plan
  4. The CPP produces excellent returns for individual contributors
  5. Expanding the CPP will help financially vulnerable seniors

However, when the five myths are placed in their proper factual context, it is the Fraser Institute’s arguments that turn out to be flawed.

The Two ‘Savings’ Myths

Continue Reading…

Big changes for mutual fund investors

graham-bodelBy Graham Bodel, CFA, Chalten Advisors

Special to the Financial Independence Hub

Transparency, education and competition should drive better outcomes for investors.

Recent enhancements put in place by the Canadian Securities Administrators (CSA) have sought to better align the interests of investors and the investment industry that serves them.

Initiatives like the Customer Relationship Model (CRM) are designed to increase transparency and help investors make more informed decisions about the kind of advisor with whom they work and the type of products in which they invest.  The idea is that with full disclosure, investors will be armed with the right information to make better decisions and protect themselves from bad products and sales practices.

Banning fund trailer commissions

So, we were somewhat surprised by last week’s announcement by the CSA that indicates they will be moving ahead, subject to consultation with investors and the industry, with banning embedded trailing commissions on mutual fund sales.  It seems even the regulators have lost faith in transparency to properly do the job of protecting investors.  This represents a significant next step in a progression of possible measures, one that regulators in countries like the UK and Australia have already taken. Continue Reading…

7 ways to cushion volatility in second half

Turtle with open mouthBy Adrian Mastracci, KCM Wealth

Special to the Financial Independence Hub

“Behold the turtle. He makes progress only when he sticks his neck out.” — James Bryant Conant, (1893 – 1978), American chemist.

Investors are on edge about the prognosis for the second half of 2016. Plenty of disarray, uncertainty and chaos is gripping stock and bond markets.

Companies will soon be reporting second-quarter earnings and future prospects. Revenue growth is the biggest challenge for companies in this environment.

The remaining central banks tools are losing effectiveness. Best to assume the second half 2016 is not a cakewalk, so be well prepared.

Some currencies have developed their own wall of worries. A sense of unease prevails as bond yields get even slimmer.

Investors may also be sticking their necks out like the turtle. Some of the risks present opportunities for the strong willed.

Consider these three pointers Continue Reading…

8 Reasons to get Permanent Life Insurance before 2017

Depositphotos_80154384_s-2015By Chantal Marr, LSM Insurance 

New tax legislation is set to take effect on January 1, 2017 that will change the way policyholders are taxed for deposits toward certain life insurance policies.

Policies issued after 2016, also know known as G3 tax generation policies, will offer less exempt room over the long term.

This new legislation will mostly affect affluent policyholders as the tax deferral features of these life insurance products typically benefit people in the higher tax brackets.

One major change is that surrender charges will no longer impact the allowable tax-deferral room in universal life insurance policies. Previously, if a policy had high surrender charges it would allow for high deposits eligible for tax deferral. Within the new framework, surrender charges will no longer impact how much tax exempt room is allowed.

Level Cost of Insurance (LCOI) Universal Life Insurance policies will be hit the hardest by the new legislation. Under the new rules, the amount of deposits allowed for tax-deferral purposes will decrease drastically.

Another type of permanent life insurance product known as Participating Whole Life, has an investment element but does not need to be managed by advisors.

Jim-Ruta
Jim Ruta

Industry veteran and life insurance expert, Jim Ruta (pictured on the right), explains in his recent column in the Investment & Insurance Journal why it’s a good investment to purchase Participating Whole Life insurance before the new legislation takes effect in 2017.

Here is a summary covering some of the points he made: Continue Reading…