All posts by Financial Independence Hub

Jack Mintz on Pension Reform: What is the Problem? What is the Solution?

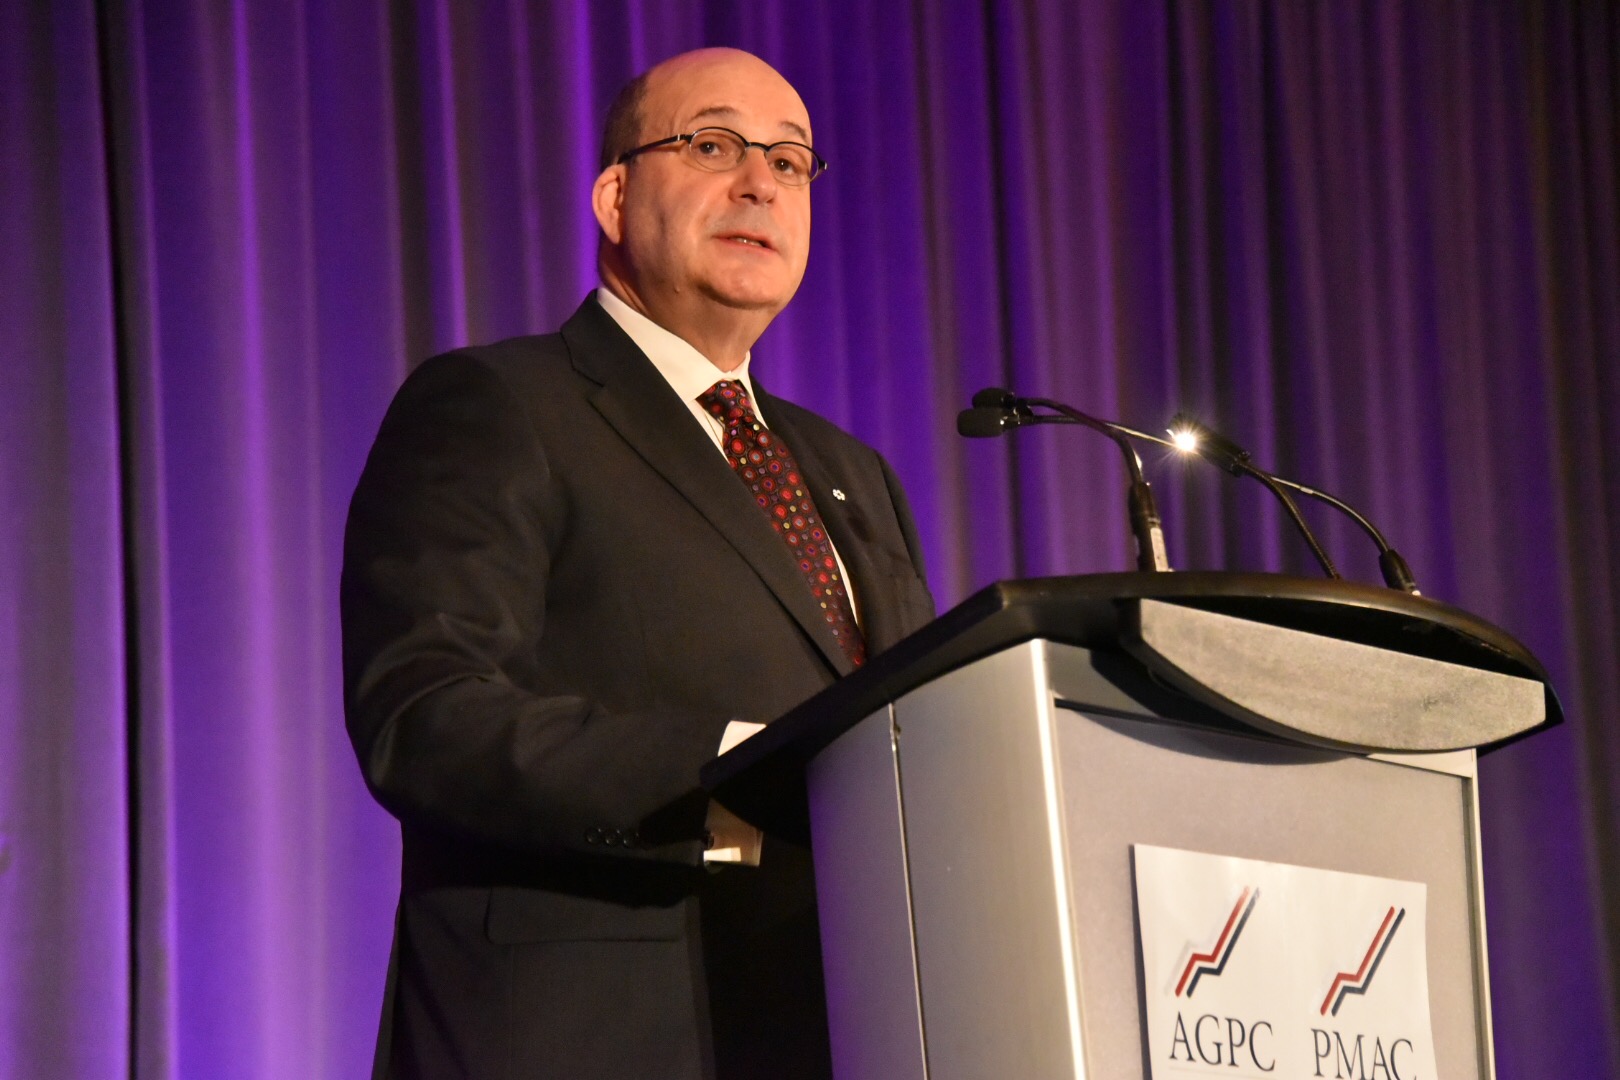
This blog is based on a talk prepared for the influential industry investment lobby, the Portfolio Management Association of Canada. It was delivered by Jack Mintz at the Fairmont Royal York, Tuesday, November 24, 2015, and  reproduced with permission of the organizers.
IMG_5885
Jack Mintz speaking today at PMAC


By Jack M. Mintz, President’s Fellow

School of Public Policy, University of Calgary

Special to the Financial Independence Hub

These days many governments, including the newly elected federal Liberal party, espouse the need for public policy to be evidence-based. I am sure everyone in this room would agree that evidence-based policy is far better than policy dependent on conjecture and the whims of a politician.

When it comes to pension reform, many politicians pushing for a much bigger public pension plan in Canada have based their policy prescriptions on an argument that Canadians do not save enough for retirement. The issue has been charged for almost a decade with some suggesting that Canada faces a pension crisis.

Four in five have adequate retirement income

In 2009, I was asked by the federal-provincial-territorial ministers of finance to be a research director of a project to determine whether there was evidence as to whether Canadians did not have adequate income for retirement.   The overwhelming conclusion based on expert studies was that most Canadians – almost four-fifths – had adequate retirement income although a pocket of Canadians with modest incomes should be of concern.

The evidence developed at that time had a remarkable impact on the pension income debate. The words pension crisis disappeared and many experts understood that Canadians had many types of investment to ensure sufficient retirement wealth. This not only included CPP, QPP, registered pension plans, tax-free saving accounts and RRSPs but also home equity, which on an after-tax basis was more valuable than all other tax-favoured retirement accounts.   With other financial and business assets, it was clear that most Canadians were doing just fine without expanding the Canada Pension Plan. Even our new Minister of Finance, Bill Morneau, concluded in a 2013 book with Fred Vettesse that the pension crisis was overblown although some issues needed to be addressed.

Low interest rates making investors nervous again
Continue Reading…

Health is a higher priority than Wealth

Sandy Cardy - photography 3
Sandy Cardy

By Sandy Cardy

Special to the Financial Independence Hub

I’ve been advising clients the same thing for many years:  “Wealth is built with returns over time.”

It’s sound, life-long, investment strategies that have the greatest impact on the financial health of your retirement.

All the while I was giving this advice, I’d thought of investing as being all about money,  so my coaching involved objectives such as:

  • Minimizing income tax
  • Investing for children’s education
  • Investment planning and asset allocation
  • Tax-efficient earnings
  • Navigating government retirement and savings plans
  • Income splitting
  • Retirement needs analysis

Health should come before Wealth

All of these being quite essential to providing safeguards for when there won’t be any more paychecks. But all this while I had been focusing too narrowly! Sound investing is not just about money. It’s about more than that, and it begins with something else entirely: Health comes before wealth – or should.

Continue Reading…

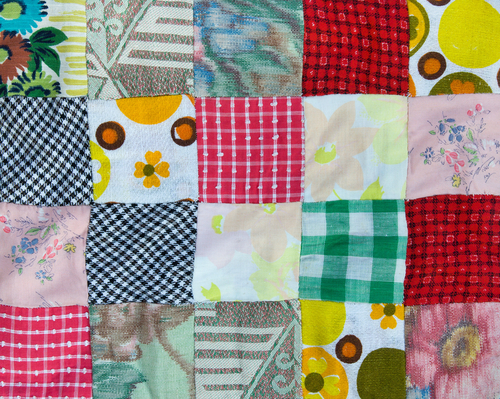
Retrofit your portfolio patchwork of stuff: does anyone need 35 investment funds?

Section of a hand-stitched patchwork quiltBy Adrian Mastracci, KCM Wealth

Special to the Financial Independence Hub

Is your nest egg a tangled patchwork of stuff in need of a retrofit?

Perhaps, purchased over time for no apparent reasons?

I’ve kept tabs on portfolios that I reviewed seeking second opinions. Investors range from do-it-yourselfers to those dependent on advisers, representing all ages.

The portfolio with the least number of investments had just three, while the highest had 97.

Most portfolios hold a patchwork of 15 to 35 mutual funds.

It’s a daunting task for anyone with a full time job to keep track of a dozen or more investments.

Several potholes can get in the way of your investing roadway.

There are two questions that every investor ought to ask:

▶ “Do I own a portfolio patchwork of stuff?”
▶ “If so, how did I get there?”

Here’s my summary of vital signs you’re a candidate for a portfolio retrofit: Continue Reading…

The value of financial advisors — how to preserve it

GregPollock_Advocis-2_sized_-266x177
Greg Pollock, Advocis

By Greg Pollock, Advocis

Special to the Financial Independence Hub

Over the years I have had the opportunity to have many meaningful conversations with members of Advocis across the country. They often tell me about the positive relationships they have with their clients and about the difference they are making in their clients’ lives.

As the president and CEO of a voluntary professional association of financial advisors, I take my role to heart and recognize that the work our members do plays an important part in helping millions of Canadians be financially prepared and protected. But I’ve often wondered if others, whether they be government, regulators, media, or the general population, truly understand the value of professional financial advice.

Do media, government, regulators and the public understand true value of advice?

This is part of the reason Advocis decided to conduct a national survey earlier this year to examine the level of value investors place on the advice they receive from their financial advisor and how satisfied they are with the services they receive and the fees they pay. More than 1,500 Canadian investors, whose financial advisors are Advocis members, participated in the study.

At Advocis, we have long proclaimed the value of advice and its impact on people’s lives. But we decided it was time that we formally heard from our members’ clients. The financial advice industry is currently at a crossroads, and two expert panels are set to present their recommendations on the regulation of financial advice in Ontario in the coming months.

Banning trailer commissions could lower access to advice

Continue Reading…

Market timing usually costs investors money in the long run

patmckeough
Patrick McKeough, TSInetwork.ca

By Patrick McKeough, TSI Network.ca

Special to the Financial Independence Hub

Some investors believe that market timing—trying to figure out if the market will rise or fall—is or can be an aid to their investing decisions.

However, most investors who try to time the market find that it costs them money in the long run. When it works, it may help them make some modest profits or avoid some modest losses. When it fails, on the other hand, it often does so in a bigger way. At times it leads to ghastly losses.

The key risk in market timing is the “false signal.”  That’s when the market does exactly the opposite of what the timer expected. In fact, some false signals may seem like sure things until they fail.

Danger of false signals

Market timers may multiply the danger from false signals by making much bigger transactions than usual. They can also raise their risk by shifting to more aggressive and highly leveraged forms of trading — delving into stock options or futures trading, for instance.

Right now, some investors are venturing into market timing without realizing it. They are trying to base investment decisions on the next movement in interest rates. Continue Reading…