All posts by Financial Independence Hub

“Stop Doing” #5: Stop Overpacking for Your Financial Journey


stevelowrie
Steve Lowrie

By Steve Lowrie, Lowrie Financial

Special to the Financial Independence Hub

We still haven’t finished our list of financial “STOP Doing” tips. In fact, the list may well be endless, given the endless supply of popular financial products and promotions continuously appearing, disappearing and reemerging, each one allegedly new & improved.

It’s no wonder so many individual investors end up with so much excess baggage along the way. This month’s post is dedicated to making sense of all those competing investment “opportunities” with our simple advice: STOP overpacking for your financial journey.

During my years as an adviser, most of my clients have come to me weighed down by the volume and complexity of their overly packed portfolios. They desperately want to lighten the load, but they’re unsure what should be preserved and what can be safely jettisoned.

I’ve generally found three areas to focus on, helping clients lighten up after years of stocking up, keeping up, and/or moving up. Raise your hand if any or all of these traits sound familiar to you:

Stocking up

You’ve been knocking around Bay Street for a while and have accumulated quite a packed portfolio. Continue Reading…
Stress test your nest egg

Adrian
Adrian Mastracci

By Adrian Mastracci, KCM Wealth Management

Special to the Financial Independence Hub

Financial stress testing is an indication of how portfolios fare during tough times.

Some US banks have had difficulty passing their stress tests.

Many a portfolio can also benefit from a form of stress testing. Investors often make high demands on the nest egg.

Our tests may reveal cracks in your financial foundations. The analysis is straightforward with “Yes/No” answers.

We survey all new inquiring clients.
“Will your nest egg pass our battery of simple tests?”

Test on 6 issues

Continue Reading…

How to Choose a Retirement Location

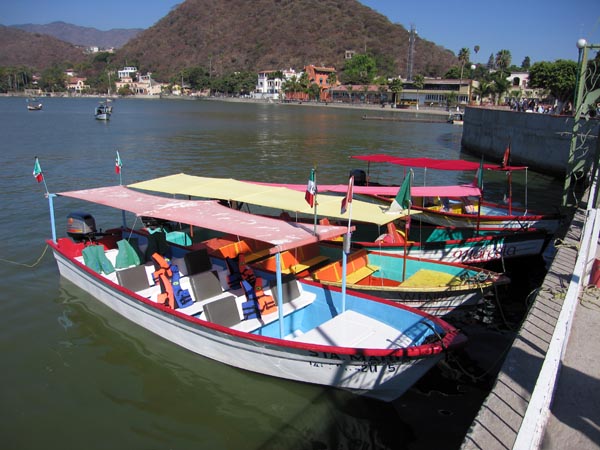
Lake Chapala, Mexico

By Billy and Akaisha Kaderli

Special to the Financial Independence Hub

So you and your spouse have decided to retire. At some point in your retirement planning you must ask yourself where you would like to spend your Golden Years. The following questions and insights should place you on the right path for finding just the location that suits your needs.

First things first

The first question you must ask yourselves is whether you want to stay in the home in which you are currently living or would like to move elsewhere. Retirement is a big step and sometimes people feel more secure staying in familiar surroundings because it makes the transition to your new lifestyle smoother.

Others, for financial reasons, a change of pace, health reasons, or for better weather, want to relocate. In this case, the next decision you must make is whether you want to stay in your home country or move overseas.

If you want to stay in your home country you must then decide what sort of climate is most attractive to you. Do you want to experience the four seasons or have a more moderate, year-round climate? Do you like mountains or beaches? What size of city or town do you most enjoy? These questions are important because they will automatically exclude places you won’t need to research. Knowing what you prefer in climate, city size and geographical configuration carries much weight in terms of your happiness quotient.

Another thing to consider is that if you choose a town or small city, are there adequate medical facilities nearby? Larger cities tend to have a full range of medical care. Smaller towns generally have clinics and a variety of doctor’s offices, but perhaps not the equipment needed for complex medical situations.

Narrowing your search

Continue Reading…

Investor Toolkit: Why you should avoid “theme investing”

1
Patrick McKeough, TSInetwork.ca

By Patrick McKeough, TSInetwork.ca

Special to the Financial Independence Hub

Today’s tip: “Theme investing may seem to be a good way to simplify your investments by following a developing trend. But it can force investors to pay too much attention to investment fads and predictions and too little to the fundamentals of good companies.”

Theme investing has natural appeal. It simplifies things. Investors like it because they feel it can put their investment returns into overdrive. Some also feel it adds fringe benefits to their investing, by letting them support social objectives.

Brokers like it because it gives them a rationale to recommend a variety of stocks.
If a client thinks gold prices are headed up, a broker can think of all sorts of gold-themed investment opportunities. They include established gold miners; junior gold companies that are working on a promising gold property; or penny golds that are outright speculations. Other possibilities are financial companies that sell gold-related merchandise like gold coins.

If the client supports environmental causes, the broker can propose investments with a “green theme.”  They include solar-power equipment makers; companies that claim their products are less harmful to the environment than competitors’ products; or companies that claim to operate with a high degree of environmental concern.

When you focus on an investing theme, however, it’s easy to overlook the fundamentals. If you’re sure gold prices are headed up, for instance, why trouble yourself with tiresome matters like finances or geology?

Predictions are the hard way to make investment decisions

Continue Reading…

Maximizing your Pension Tomorrow takes Planning Today

MattArdrey
Matthew Ardrey

By Matthew Ardrey

Special to the Financial Independence Hub

At last count, over 6 million Canadians are part of a registered pension plan. Unless you are one of the truly lucky few who have a defined benefit (DB) pension plan, you’re likely part of a defined contribution (DC) pension plan – which means you need to be a bit more proactive if you hope to reach your retirement goals.

A DB pension plan is what comes to mind when most people think of a pension. It pays you an income stream in retirement. A DC pension plan is more like an RRSP. You save to the plan, but do not know what the end result will be at retirement. Even though your plan may be a DC instead of a DB, with proper planning you can take advantage of this benefit and be a step ahead on the path to retirement.

Step One: Asset Mix

Your asset mix is the combination of equities, fixed income and cash that you hold in your account. What percentage you allocate to each area will have a significant impact on the long term performance of your portfolio and the volatility you experience while investing.

Generally speaking, when you are more than 10 years away from retirement, a growth mix of 75% equities and 25% fixed income is appropriate. Once you are closer than the 10-year mark, a shift to a balanced mix of 60% equities and 40% fixed income would be more suitable. In all cases, your equities should be diversified geographically with an equal allocation to Canada, the U.S. and international markets.

Continue Reading…