In our last piece, we described why most investors should ignore the never-ending onslaught of unpredictable financial news and tend to three strategies that can be much more readily managed – at least once you know they are there. Hidden in plain sight, these potent strategies include:
Being there
Managing for market risks
Controlling costs
Plain-Sight Strategy #2: Managing for Market Risks
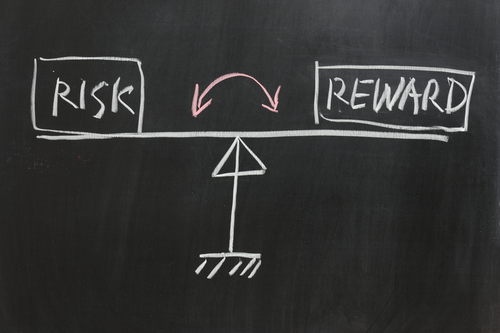
Don’t take on more risk than you must.
There’s no getting around the fact the market does not deliver rewarding returns without periodically punishing us with realized risks. That’s why it’s so challenging for most investors to “be there,” consistently capturing available returns by remaining invested over time. It’s also why it’s vital to avoid taking on more risk than you must in pursuit of your personal goals. For this, we have two powerful tools at our disposal, best used in tandem: Continue Reading…
Last month, we explored Jim Collins’ “Good to Great” suggestion that we would be well served by having a STOP-Doing List to pair with our To-Do Lists.
For starters, we advised investors to STOP reacting to market noise and start heeding the long-term evidence. Another worthy addition to your financial STOP-Doing List is to stop picking active money managers (or hiring someone else to try to do this for you).
As a reminder, my definition of an active money manager is someone who is engaging in some form of forecasting, whether it be picking stocks, timing markets or a combination of both.
Predicting the Unknowable
In our personal and financial lives alike, we worry about so many things that we cannot control. One of the greatest of these things is the future. When speaking with investors about the dangers of trying to accurately forecast the market’s or a stock’s pricing moves, many can accept that it’s difficult to succeed on their own. But the next leap is harder to make. Most investors want to believe that, while they may not personally have the time, energy or expertise to beat the market, they can still turn to well-heeled professional managers to do the forecasting for them.
Financial Services Attracts the Best and Brightest
In most pursuits in life, more practice and more experience makes perfect. So if someone is really good at some occupation or trade, it’s a safe assumption to assume he or she will continue to be good at it in the future.
The Federal Government has started consultations on its newest retirement savings concept: allowing individuals to make voluntary contributions to the Canada Pension Plan.
While details are sketchy, it would appear that basic agreed-upon concepts mean contributions would be voluntary and that employers would not be forced to make or match contributions.
While the Federal Government made it clear that it would not let the Canada Revenue Agency be used by the Ontario Retirement Pension Plan proposed by Premier (Kathleen) Wynne, presumably a voluntary CPP would allow use of the existing machinery to collect these new savings.
The core design issue rests with the form of benefit that this voluntary plan would offer: defined benefit or defined contribution?
If the goal here is to create a supplement to the current CPP benefit, presumably contributions would have to be locked in, and without member investment directions.
The mechanism to convert the fixed defined contributions coming into the supplemental CPP account into defined benefits would have to rely on partial deferred annuities, or self-annuitization.
This would distinguish the Supplemental CPP from an RRSP or TFSA.
Tip of the week: “When you work out a plan for your retirement, make sure that you aren’t basing your future income on over-optimistic calculations that will end up leaving you short.”
Every year as RRSP season heats up, many investors are confident they are taking concrete steps toward a secure retirement. But are those steps based on realistic calculations?
Let’s say you’re 50 and you want to retire at 65. You have $200,000 in your RRSP, and you expect to add $15,000 in each of the next 15 years. To determine if this is enough to retire on, you need to make assumptions about investment returns and income needs.
• What you can expect
Long-term studies show that the stock market as a whole generally produces total pre-tax annual returns of 8% to 10%, or around 6% after inflation. For purposes of this retirement plan, we’ll assume a 6% yearly return, and disregard inflation. Continue Reading…
Editor’s note: the piece below was written a few weeks before the market chaos of last Friday and this Monday, which only makes it that much more relevant now. Even more prescient was a B&E guest post on August 13th entitled What you can do about the upcoming stock market crash.
Marie Engen, Boomer & Echo
By Marie Engen, Boomer & Echo
Special to the Financial Independence Hub
The stock markets have shown some volatility this summer and this has concerned some investors who have been riding the latest “full steam ahead” bull market and think a market correction is imminent.
These concerns have increased interest in investment products that have a principal guarantee. But are they worth it? These guarantees come with a steep cost.
Market-linked GICs
Market-linked GICs, also called equity-linked GICs, are hybrid products that proclaim to capitalize on the growth potential of the stock market without risking your original investment. The return is derived from gains in the equity markets over the term of the GIC – usually 3 or 5 years.
The portion of the return derived from the equity markets depends on various components:
The benchmark used to calculate the return e.g. S&P/TSX Bank Index or Capped Utility Index, Nikkei 225 Index
Pre-set maximum return e.g. 6% for a 3-year term
Dividends are not included in the calculations
Interest income is paid on maturity. If the equity portion produces no return, you receive no interest at all. Pay particular attention to how the equity portion of the return is calculated.
Like conventional GICs they are guaranteed by the Canada Deposit Insurance Corporation to the maximum allowable limits and are available for purchase in registered and non-registered vehicles.
Segregated Funds
A segregated fund is essentially an insurance product based on an underlying mutual fund that is offered by insurance companies. Under the insurance contract – usually for 10 years – part, or all, of the original principal amount may be guaranteed. In some cases there is the ability to reset the guarantee at a higher amount in future years. Continue Reading…


 Posted By