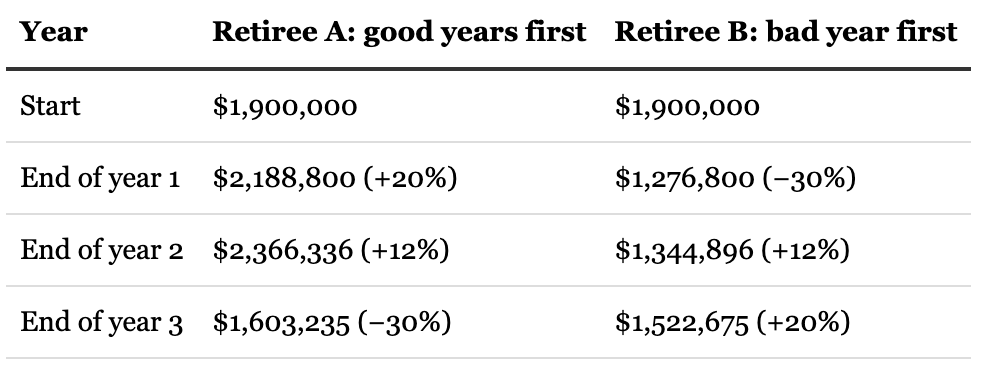Budget 2026 — unveiled Thursday — contains many tweaks to the personal and corporate tax system. Unlike previous years, I refrained from posting initial comments in the hour after release. Over the years and decades, Canadian governments have tended to make the federal budget an event normally held in the first few months of the new year, so I found this particular budget snuck up on me, and perhaps on you!
Not being in Ottawa for the lockup, it’s no simple quick read. You can find out yourself by downloading the more than 500 pages here. Pretty overwhelming, so it’s no surprise that the Globe & Mail’s Andrew Coyne cynically summed it up thusly (hyperlinked headline for subscribers): “A strange budget, as opaque as it is complacent.”
“I give up,” Coyne quipped, saying federal budgets have “become utterly incoherent, wandering, purposeless and, frankly, impossible to understand.” He laments the reality that “with federal debt at about 40 per cent of GDP, and provincial government debts adding up to about 30 per cent of GDP, total net public debt is now in excess of 70 per cent of GDP.”
Other than that, I’m not going to reprise the mass media’s major points on the exploding Debt and rises in Defence spending. What follows is what captured my own attention as an investor and semi-retiree, not to mention someone whose daughter is finally dipping her toes into the costly Toronto housing market.
I found the highlighted RBC Wealth Management’s key takeaways mercifully succinct. Thus, it says there are “no proposed changes to the general personal or corporate income tax rates” but a number of proposals to simplify the Canadian tax system. I can’t help but reflect that the very phrase “simplify the Canadian tax system” is the ultimate oxymoron!
Later annual Tax Filing deadline
Extending the annual tax filing deadline from the traditional April 30th to May 15th will no doubt be welcome for procrastinators, although if enacted it would not apply until the 2027 Tax Year (i.e. May 2028). Our family typically tries to escape winter in January and much of February, so if that measure takes hold, we will welcome the eventual filing respite. The measure would also apply to the self-employed.
RRSP for Life
I’m still scratching my head about the concept of an “RRSP for life,” well explained in this Investment Executive article: Budget proposes RRSP for life, eliminating need to convert to RRIF. Minimum withdrawal requirements wouldn’t be affected and would still begin at age 71, it said. It “also plans to simplify transfers to a surviving spouse by allowing them to be named a successor holder for an RRSP, as is currently allowed for successor annuitants in RRIFs and TFSAs. This could permit the RRSP to remain open until the death of the surviving spouse.” IE quotes CIBC Wealth’s Tax guru Jamie Golombek to the effect the proposal is “a novel approach … It sounds like they want to get rid of the whole RRIF concept altogether, and just have the RRSP, and the RRSP goes on forever until death or until the last to die, if you have a spouse or common-law partner.”
However, the changes necessary to implement all this could mean it will take a few years to get it in place, Golombek warned.
The article also describes pre-budget recommendations for Ottawa to raise the RRSP-to-RRIF conversion age from the current 71 to 74 or 75.
Doug Carroll, tax and estate specialist at Aviso Wealth, points out in this G&M article that the RRSP for Life reform “would not change the obligation to make those minimum withdrawals after age 71. Instead, it would simply spare Canadians the paperwork and hassle of converting their account.”
Higher Foreign Content limits on T1135 form
One measure I didn’t see emphasized in the initial wave of publicity was about Form T1135, the Foreign Income Verification Statement. Up until now, Canadian residents, corporations, trusts and certain partnerships had to file this form above a threshold of $100,000 in specified foreign property held in taxable (non-registered) investment accounts. Budget 2026 proposes to double this threshold to $200,000, which any investor in (mostly) US securities would surely welcome. According to RBC, the CRA “would also increase the threshold for simplified reporting from less than $250,000 to less than $500,000.”
As I understand the current rules, the existing $100,000 threshold applies to foreign securities (like US stocks and ETFs) held in taxable accounts and is defined as the initial cost, not current market value. For couples it’s $100K per spouse. Because it is a laborious process to track and report, I’ve always been careful to stay well below this threshold. If and when the measure is official, it would be nice to be able to add to non-registered foreign investments. But I’ll believe it when I see it.
Affordability Measures
As expected, Budget 2026 proposes several measures aimed at mitigating the high cost of daily living, particularly for young families. Thus, Ottawa is proposing a one-time supplement to the Canada Groceries and Essentials Benefit, which helps lower the GST for low-income taxpayers. As noted in the same G&M overview, the one-time supplement to the benefit would be equal to half the amount that beneficiaries are eligible for in the current benefit year, which runs until the end of June 2027. To be delivered as a one-time payment early next year, the supplement would be up to $223 per adult and $117 per child, with a $117 top-up for single adults. It added that Ottawa has “already delivered a one-time 50-per-cent benefit supplement in June, followed by a 25-per-cent increase to the regular, quarterly benefit payments that is set to last until 2031.” Continue Reading…
As we telegraphed in the September installment of my MoneySense Retired Money column, this month’s column is a book review of David Booth’s Stay Calm, published early in September. For the full review in the October column, click on the highlighted headline: The calming genius of passive investing.
David Booth is founder of Dimensional Fund Advisors (DFA), maker of DFA Index Funds and DFA ETFs. I have long invested some of our family’s money in DFA funds, along with many of the other usual indexing suspects.
They are famously champions of taking a passive set-it-and-forget it approach to investing while minimizing the noise of what they have dubbed “financial pornography” propagated by traditional and social media, and the self-appointed experts who claim they can pick individual stocks or consistently time the markets.
As someone who takes a decidedly hybrid approach to investing in ETFs in various asset classes, — and occasionally indulging in a bit of high-conviction “index skimming” — I found Booth’s Stay Calm to be a refreshing reminder of the sound principles that underlie DFA.
Those who need a refresher on the virtues of passive investing will not be disappointed but as the book’s subhead implies, there are also quite a few lessons about embracing uncertainties in life in general, as well as investing in particular.
Stay Calm was published early in September by Authors Equity and is aptly subtitled “Learn to Embrace Uncertainty in Investing and Life.” The book is divided into three main parts. Part 1 is on the science of investing and covers the Gift of being an Outsider, how Markets work and how to harness public markets. Part 2 is titled “The Mindset to Stay Calm” and the four chapter titles all make for excellent bullet points; Flexibility is the key to navigating Life’s Uncertainties; Don’t Predict, Plan; Control what you can control and manage what you can’t; and Tune out the Noise.
Sequence of Returns Risk: Chart by Stefano Starkel
My latest MoneySense Retired Money column touches on a number of blogs that regular readers of Findependence Hub may already have seen, but ties together a few disparate threads that may warrant revisiting. Click on the highlighted headline here for the full article: The CAPE ratio, the 4% rule and retirement anxiety.
The focus is on the 4% Rule, Sequence of Returns Risk early in Retirement, and stock valuations measured by the CAPE Ratio.
The 4% Rule is one of those Personal Finance chestnuts, a topic we explored in Retired Money as recently as late 2025 (here.) My Findependence Hub blog on the 4% Rule appeared late in July here.
Robert Shiller’s CAPE Ratio: the Cyclically Adjusted Price-to-Earnings ratio (CAPE), is a measure of how fairly valued or overvalued stocks may be. The blog on the CAPE Ratio ran late in August here. Both are under my byline: Each contains full raw quotes from a variety of business owners and investment professionals on both sides of the border, gathered on Linked In and a service called Connectively, formerly Featured.com.
A useful primer on the CAPE Ratio was provided by blogger Michael J. Wiener, on his Michael James on Money blog (from early August), also republished here on Findependence Hub in August. He says the CAPE Ratio is “just the current price divided by the average inflation-adjusted earnings over the past decade.” Investopedia defines the CAPE Ratio as “a valuation measure that uses real earnings per share over a 10-year period to smooth out fluctuations in corporate profits.” You can find more on CAPE here on Wikipedia.
See also this recent Findependence Hub blog by Stefano Starkel titled the The Alternative to the 4% Rule isn’t a different number: It’s a different mechanism. There, Starkel argues that “the fragile part of a fixed-withdrawal plan is Sequence-of-Returns risk.” He shows a chart [shown above] that demonstrates how early losses in Retirement can have a dramatically negative impact on returns and thus Retirement income.
Stay Calm
Sure, proper diversification and asset allocation should allow you to Stay Calm, which happens to be the title of a new book published early in September by David Booth: he’s a founder of Dimensional Fund Advisors (DFA), one of the better indexing companies out there. I have finished reading it and plan to review it for MoneySense in the near future.
The main principles of the DFA approach to investing is to keep costs low by minimizing trading and using passive investing vehicles like ETFs, and above all trust the markets over the long term while avoiding picking individual stocks and attempting to time financial markets.
As we aim to do roughly every month, today’s blog on Financial Independence taps the expertise of multiple business owners and investment experts on both sides of the border gathered through Connectively in partnership with LinkedIn.
This edition looks specifically at the FIRE movement, which of course is an acronym for Financial Independence Retire Early.
The paragraph reproduced below is how we posed the question.
The subsequent replies chosen are presented almost in full, with links to the source contained in their bios at the end of each section. I’ve added subheadings to speed readers through the content I hope is relevant to them.
What is your take on the FIRE movement (Financial Independence Retire Early)? Do you prefer a different term, do you believe in the FI part but not the RE part? How early is too early to “retire?” How do you define Retirement? Full-stop never work again, or just no longer being a corporate salaried employee. Any favorite FIRE blogs or podcasts you subscribe to or recommend?
“Most FIRE folks I’ve encountered don’t actually stop working; they stop working for someone else.”
Ah, the FIRE movement: where twenty-somethings eat rice and beans for a decade so they never have to attend another Monday morning meeting. I love the “FI” part with my whole heart. Financial Independence isn’t a trend; it’s just smart adulting. Building an emergency fund, crushing high-interest debt, investing consistently: that’s timeless wisdom dressed up in a catchy acronym.
The “RE” part, though? That’s where I raise a legal eyebrow. Retiring at 32 sounds thrilling until you realize you’ve got 50+ years of healthcare costs, inflation, and “what if the market tanks in year three” anxiety ahead of you. I’ve seen too many bankruptcy filings from people who front-loaded their optimism and back-loaded their income planning. So my official stance: FI, yes. RE, only if your math is bulletproof and you have a contingency plan tighter than a loan shark’s payment schedule.
How early is too early? There’s no magic number, but if you’re retiring before you’ve stress-tested your plan against a recession, a health crisis, and at least one kid’s emergency root canal, you’re retiring on hope, not strategy. I’d rather see someone retire at 45 with a fortress of a financial plan than at 35 with a house of cards.
As for defining “retirement”, I don’t buy the full-stop-never-work-again version. Most FIRE folks I’ve encountered don’t actually stop working; they stop working for someone else. They pivot to consulting, passion projects, or that Etsy shop selling hand-painted rocks. That’s not retirement—that’s career emancipation. And frankly, that’s healthier. Purposeless days can be as damaging to your well-being as an unpaid credit card is to your credit score.
Favorite resources? I keep an eye on “ChooseFI” for community-driven inspiration and practical steps, and “Mr. Money Mustache” for someone who’ll bluntly tell you to stop buying lattes and start buying index funds. But I always tell people: read these for motivation, not gospel. Your debt situation, your state’s laws, and your risk tolerance are yours alone—no blog can litigate your specific financial life like a good advisor (or attorney) can.
Bottom line: chase Financial Independence like it’s your job. Just make sure “Retiring Early” doesn’t quietly become “Filing for Bankruptcy Early” instead. — Loretta Kilday, DebtCC Spokesperson, Debt Consolidation Care
“I prefer the term Financial Autonomy.”
Financial Independence is the ultimate risk management strategy, yet the “Retire Early” label often misdiagnoses the goal as an escape from productivity rather than an acquisition of professional autonomy.
I prefer the term Financial Autonomy because it reflects a shift in capital allocation rather than a cessation of value creation. After two decades overseeing financial strategy and delivery operations, I have found that high-performing leaders rarely want to stop contributing; they simply want to stop answering to inefficient structures. Retirement should not be defined as a full-stop end to work, but as the pivot point where professional activity is driven entirely by intellectual curiosity rather than financial necessity.
The math of independence must be approached with the same discipline as a corporate balance sheet. Many proponents of early retirement rely on withdrawal models that fail to account for long-tail risks like global healthcare inflation or currency volatility across a 50-year horizon. It is too early to step away until a portfolio has been stress-tested against at least two distinct economic cycles. True independence requires ensuring that passive cash flow exceeds lifestyle burn even during prolonged periods of market stagnation.
Durable financial planning relies on economic history and financial biographies rather than the fleeting trends of modern hustle culture. Understanding how capital markets and labor value have shifted over the last century provides a more stable framework for long-term planning. The objective is to reach a stage where you are no longer a salaried employee by obligation, but a contributor to the economy by design. Sustainable returns are not just about the balance in a brokerage account; they are about the continued growth and leverage of your human capital. — Abhishek Pareek, Founder & Director, Coders.dev
“Real freedom is being able to say no to what drains you and yes to what sustains you.”
I’ve seen too many high achievers burn out chasing Financial Independence, then realize they don’t know who they are without the hustle. The problem isn’t the FIRE framework itself, it’s that people use it to escape rather than create. They’re running from burnout instead of asking why they’re burned out in the first place.
I believe in the FI part because autonomy matters. But retiring at 35 or 40 can backfire if you haven’t figured out what actually fulfills you beyond hitting achievement metrics. I think of retirement as the freedom to choose work that aligns with your values, not necessarily stopping work altogether. Some of my most miserable clients were financially independent but spiritually empty because they’d built their entire identity around accumulation. Real freedom is being able to say no to what drains you and yes to what sustains you, whether that happens at 45 or 65. — Samka Keranovic, Founder, Drwmbs
“Financial Independence is about buying your freedom to choose.”
I love the ambition behind FIRE, but I’d reframe it slightly: Financial Independence is about buying your freedom to choose, and that’s something I think about constantly running operations.
The FI part is undeniable. When you’ve built enough cushion that a bad month doesn’t sink you, you make sharper decisions, negotiate better, and sleep easier. The RE part is where I’d push back on the label, because most people who “retire early” at 35 or 40 are really just changing what they work on, not stopping work entirely.
That’s my definition of retirement, honestly: it’s not never working again, it’s never being forced to work on something you don’t care about. Full-stop retirement sounds like a fast track to boredom for a lot of driven people. The folks I admire treat FI as leverage. They leave the salaried corporate role and pour energy into something they own, whether that’s a business, a portfolio of projects, or in my world, building free tools like our customizable QR code generator because they want to, not because payroll depends on it.
How early is too early? Whenever the math only works if nothing ever goes wrong. I apply the same logic I use with clients: we back our SEO plans with a six-month performance guarantee, continuing services for free if KPIs aren’t met, because we’d rather absorb the risk ourselves than ask a small business to bet everything on hope. That’s the FIRE mindset done right, protect the downside first, then race toward freedom. If someone at 32 has a plan that survives market crashes, health surprises, and inflation, more power to them. If it only works in a spreadsheet, they’ve built a fantasy, not a plan.
For reading and listening, I’d point people to Mr. Money Mustache for the no-nonsense math and ChooseFI for the community side of the equation. Both do a great job separating hype from substance, which is the same standard I’d hold any advice to, financial or otherwise. — Melissa Basmayor, Marketing Coordinator, Freeqrcode.ai
“The financial objective, in my view, should be freedom of choice rather than freedom from all work.”
I strongly believe in the FI part of FIRE, but I am less attached to the idea that financial independence should automatically lead to retiring as early as possible.
For me, Financial Independence means reaching the point where your decisions are no longer dictated by the next paycheck. That could mean leaving a corporate job, changing careers, starting a business, working fewer hours, or simply having enough financial security to say no to work you no longer want to do.
I therefore prefer to think of FIRE as “Financial Independence, Reclaiming Employment” rather than necessarily “Retire Early.”
I do not think there is a universal age that is too early to retire. The bigger question is what someone is retiring to. Work provides more than income: routine, social contact, intellectual challenge and a sense of usefulness. If someone reaches financial independence at 40 but removes all of those things without replacing them, early retirement may not feel as rewarding as expected.
My definition of retirement is not “never earn another dollar.” It is reaching the point where paid work becomes optional rather than compulsory.
The financial objective, in my view, should be freedom of choice rather than freedom from all work. — Cem Oner, Founder / Finance & Public Data Publisher, Hesap Cebimde
“My definition of retirement is not ‘never work again.’ It’s never being forced to work again. Huge difference.”
I’m a believer in the FI part, one hundred percent. The RE part is where I push back, and here’s why: I built Scale By SEO from scratch, and I’ve watched consistent effort compound the same way money does. Walking away from work you love at 35 to sit on a beach sounds like quitting a marathon at mile twenty because your legs feel fine.
My preferred term is “Financial independence, work on your terms.” The money buys you optionality, not an exit. It means you take a client because you want to, not because rent is due. That’s the real win.
How early is too early? There’s no magic number, but too early is when you retire from something instead of to something. If you don’t have a reason to get up in the morning that isn’t a paycheck, the money won’t fix that. I’ve watched business owners sell out and go stir-crazy within a year. Purpose doesn’t have a price target.
And my definition of retirement is not “never work again.” It’s never being forced to work again. Huge difference. I run an SEO agency out of Harlingen, Texas, and I genuinely enjoy helping small businesses, plumbers, healthcare practices, auto body shops, get found online. Would I stop doing that because a portfolio hit a number? Absolutely not. Work you choose is one of life’s great pleasures.
On resources, Mr. Money Mustache is still the best voice in the space, and his writing is funny on top of being smart.
The ChooseFI podcast is my go-to for practical tactics, and JL Collins’ “The Simple Path to Wealth” is the book I’d hand anyone starting from zero. His stock series alone is worth hours of your time.
One warning: the FIRE crowd can obsess over the math and skip the meaning. Independence is a tool. Decide what it’s for before you chase it. I’d rather be sixty and excited about my work than forty and bored on a beach. — Wayne Lowry, CEO, Scale By SEO
“Buy the freedom, skip the recliner.”
Buy the freedom, skip the recliner. That’s my FIRE philosophy in one line, and I think it’s the healthiest version of the movement.
I buy the FI part completely. Financial Independence is just margin in your life: low overhead, real savings, the ability to say no. Running a small roastery teaches you that fast. Since Craig Keel founded Equipoise Coffee in 2021, every day has been about prioritizing when resources are tight. Do we spend on another single-origin like the Ethiopian Yirgacheffe, or on brewing guides that help people make better coffee at home? Margin is what lets you make those calls from strategy instead of panic. Personal finance works the same way.
The RE part is where I’d edit the script. I prefer “financial independence” plain and simple, maybe “financial autonomy,” because “retire early” sells an ending when most people actually want a beginning. I define retirement as the point where work becomes a choice rather than an obligation. By that definition, I know plenty of “retired” people who work more passionately than any salaried employee, and plenty of employed people who retired emotionally years ago.
How early is too early? When you’ve funded decades of pure consumption with nothing you’re building toward, you’ve traded one imbalance for another. Our whole brand philosophy is balance, in the cup and in life. A coffee that’s all brightness and no body falls flat, and so does a life that’s all freedom and no purpose.
On resources, Mr. Money Mustache is the classic and still worth reading, less for the math than for the “build the life you want, then save for it” ethos. ChooseFI is a solid podcast with a wide range of guest stories worth sampling.
So if FIRE means engineering the freedom to do work you love, I’m all in. If it means never working again, that just sounds like a long, quiet fade. — Rory Keel, Owner, Equipoise Coffee
My honest take: the “FI” half matters far more than the “RE” half
My honest take: the “FI” half matters far more than the “RE” half — the math (25 times your annual expenses, per the 4% rule) doesn’t care whether financial independence means quitting work entirely or just no longer needing the paycheck, and that distinction gets lost when people fixate on “retiring early.” I’d define retirement less as “never earning another dollar” and more as your paycheck becoming optional — once a portfolio can sustain a lower, safe withdrawal without more contributions, working becomes a choice about meaning rather than survival. The lever that actually moves someone’s FIRE date isn’t income, it’s savings rate: saving 10% of your income buys roughly one year of retirement for every nine years worked, but push that to 50% and it gets close to one-for-one, a bigger shift than most raises ever deliver. I build the free FIRE and compound-interest calculators at TheSmartWealthTools.com, so I watch that one input move people’s timelines by decades more than any other number on the page. — Haggai Tzouk, Founder, TheSmartWealthTools.com
Financial Independence is real. The “retire early” part is where people lose the plot.
I’m Runbo Li, co-founder and CEO of Magic Hour. The FIRE movement gets the diagnosis right but the prescription wrong. Financial independence is real. The “retire early” part is where people lose the plot.
I watched my parents run small businesses my entire life. They never talked about retirement. They talked about freedom. Freedom to pick which problems they wanted to solve, which customers they wanted to serve, which days they wanted to work. That’s a fundamentally different orientation than “stop working as fast as possible.” Continue Reading…
As those who follow me on social media may already know, financial guru David Chilton interviewed me on his popular The Wealthy Barber podcast, which dropped Tuesday on YouTube.com. You can find the full 39-minute clip here: try 1.5x speed if you’re pressed for time!
David is a good interviewer and got me to confess a few things I might not have coughed up otherwise. Mostly, we chatted about personal finance in Canada, retirement and retirement planning and — a particular concern for David — the plight of young Canadians priced out of the Canadian real estate market. This included a discussion of our own family’s situation and how the “Bank of Mum and Dad” may be enlisted to supplement down payments scraped up by some combination of TFSAs, the RRSP Home Buyers Plan and the new First Home Savings Accounts (FHSAs) that David is quite enthusiastic abøut.
Naturally we talked about Retirement. David himself is retiring at the end of this year soon after he turns 65, so he will have “beaten” me to Full Retirement by roughly eight years. I wrote about his looming Retirement recently in my MoneySense Retired Money column, which was also flagged here on Findependence Hub.
A Who’s Who of Canadian Personal Finance
I was David’s 71st interview on the podcast since he launched it two years ago: he says he plans to keep it going at least until the end of this year. As I comment in the interview, his many guests constitute a veritable “Who’s who” of Canadian personal finance, with a handful of Americans thrown in.
Glad to be part of it and to join such luminaries as Ben Felix, Preet Banerjee, Rob Carrick, Fred Vettese and many more. As David notes, a lot of his guests are younger newer voices known as “Finfluencers,” a group I also wrote about in Retired Money earlier this summer.
We also discuss other more “seasoned” financial commentators, including Bruce Cohen, Ellen Roseman, Jim Daw, Mike Grenby and other pioneers of the genre. Some of those veterans’ names came up in another Retired Money interview I did after Rob Carrick retired a year ago from his full-time job at the Globe & Mail.
The financial novels spawned by The Wealthy Barber
With an estimated 4- to 5- million copies of his books sold worldwide, it’s no surprize that Chilton’s pseudo-fiction financial format spawned many imitators. I fondly recall Jim Daw (retired from the Toronto Star) cracking a joke about the many financial novel knockoffs inspired by The Wealthy Barber. Rather than a “branch” of personal finance literature, Jim quipped in his review of my own Findependence Day that this specialized field consituted merely a “twig” of the genre.
While much of the interview was perforce about investing and retirement, good interviewer that he is David manages to coax some confessions about my own lifestyle and choices. For example, I tackled headon the fact that the title of my own similarly titled The Wealthy Boomer was not initially conceived as a ripoff of Chilton’s far more commercially successful The Wealthy Barber: that title was just a description of the possible demographic target for the book’s publisher.
We also talked about 12 Good Years, the blog that blogger Fritz Gilbert originally ran on his Retirement Manifesto blog. That article make she case that new or aspiring retirees should strive to make the best of the years between ages 60 and 72, whether for strenuous travel or demanding hobbies, physically or mentally. Continue Reading…


 Posted By