Hub Blogs

Hub Blogs contains fresh contributions written by Financial Independence Hub staff or contributors that have not appeared elsewhere first, or have been modified or customized for the Hub by the original blogger. In contrast, Top Blogs shows links to the best external financial blogs around the world.

A Wake-up Call for those choosing Mutual Fund fees over Robo-Advisors

Image courtesy Questrade/iStock

By Scarlett Swain

(Special to Financial Independence Hub)

It’s that time of year. The leaves have started to shift to brilliant shades of crimson, orange, and yellow. The days are getting shorter. And, suddenly, it’s “jacket weather” again. For many Canadian families, the transition into cooler months signals a time to begin the process of reviewing their finances from the past year with the goal of being better prepared in the years ahead.

With the cost of living in Canada incrementally higher than it has been in recent memory, there is a renewed opportunity for families to ask a familiar question: what is a simple, one-step investment strategy that they can use to help stretch the most out of their money, both now and for the long haul?

Well, like the changing seasons, it may be a good time for families to consider changing up a dated investment approach in favour of one that will take their money a little further. That is, using a low-fee, low-touch, robo-advisor in place of costly mutual fund investments … and, here are a few reasons why:

Accessibility

Robo-advisors have ushered in a new era of accessible investing. Designed to be user-friendly from the get-go, they are an excellent choice for both novice and experienced investors. With just a few clicks, investors can select a portfolio that matches their risk tolerance and fund it with little to no hassle.

Diversification

A well-constructed portfolio needs variety. Robo-advisors excel at this by spreading investments across different asset classes, thus reducing risk. Mutual funds, while also diversified, often lack the customizability and personalization offered by low-fee robo-advisors.

Automated Rebalancing

Investing with a robo-advisor provides nimble, automated rebalancing, ensuring that investments stay aligned to goals, even as market conditions shift. Mutual fund investors often need to manually (and worse, reactively) adjust their portfolios, potentially missing out on market opportunities or exposing them to unnecessary risk. Continue Reading…
Before you Retire: 5 things to do before Pursuing a Conservatorship

Conservatorships can be a great tool for protecting finances in the right situations. Learn about some vital things to do before pursuing a conservatorship.

Adobe Image by contrastwerkstatt, via Logical Position

By Dan Coconate

Special to Financial Independence Hub

As you approach retirement, you want to accelerate your planning for the future, and one crucial consideration might be a conservatorship.

A conservatorship is a legal arrangement that provides a responsible adult (the conservator) with the authority to make decisions for another person (the conservatee) incapable of making them on their own.

This not only affects individuals within the United States, but it can be done throughout the world.

If you’re considering pursuing a conservatorship, you should be as prepared and informed as possible. We’ll discuss five things you should do before pursuing a conservatorship so you can make the best decision for your loved one or for yourself.

Learn all you can

The first step in conservatorship planning should always be to learn as much as you can about the process, requirements, and potential pitfalls. Start by asking some important questions, such as what are the different types of conservatorships, how they function, and whether you even need one. You should also consider consulting an attorney with experience in conservatorship law, who can help answer these questions and provide further guidance.

Assess the Need

Next, carefully assess whether a conservatorship is the best option for your situation. Consider alternatives like power of attorney, living trusts, or other legal arrangements that may be less restrictive. If possible, involve the person who may be the subject of the conservatorship in discussions about their needs and desires. This can help ensure you hear and respect their wishes in your decision.

Evaluate your own Capability

Before pursuing a conservatorship, another thing you should do is think hard about your own capabilities. Remember that these legal bindings involve significant responsibility. Ask yourself whether you’re able and willing to dedicate the necessary time and effort to managing someone else’s affairs. Do you possess the knowledge and skills to make sound decisions about their financial, legal, and personal matters? It may feel daunting, but honestly assessing your readiness can help ensure you’re making the right choice.

Understand the Costs

Additionally, prepare yourself for the financial implications of pursuing a conservatorship. Pursuing a conservatorship can be expensive, from court fees to ongoing legal, accounting, and fiduciary costs. Factor these expenses into your decision-making and explore ways to reduce costs if necessary, such as seeking pro bono legal assistance. Continue Reading…

Half of new Canadian families targeted by financial fraud

A survey by Interac Corp. (Interac) released Wednesday (Nov. 8) on Canada Newswire found 70 per cent of  new Canadians polled believe they are more susceptible to financial scams than the general population.

53 per cent of newcomers say they and/or immediate family members have been targeted by fraud, while 55% are very concerned about becoming a victim in the future.

Scammers appear to be preying on a record number of immigrants arriving in Canada, who have to navigate an unfamiliar financial landscape. The top scams they face include fake job postings (witnessed by 40% of new Canadians surveyed), phishing attempts (37%) and scammers disguising themselves as representatives of official government institutions (34%)

“Being targeted for financial scams is an all-too-common experience for newcomers. We all have a role to play in providing advice to help build their financial literacy and spot scams before it’s too late,” says Rachel Jolicoeur, Director, Cybermarket Intelligence and Financial Crime at Interac. “Newcomers want to feel in control and most prefer to spend their own money versus borrowing. As they get used to life in Canada, we need to build their trust when transacting in new ways – such as using Interac e-Transfer or Interac Debit for the first time.”

The Interac survey reinforces that high scam rates are taking a toll on the financial fortitude of newcomers. Only 22% of newcomers polled strongly agree they would know what to do if they were the victim of a financial scam. 56% say being targeted makes them feel less financially confident, compared with 36% of all respondents polled.

New digital learning program helps arm against fraud

73% of these newcomers to Canada want to learn more about how to protect themselves from fraud, and 83% see the value of having access to tools that help manage their spending. Seeing as November is Financial Literacy Month, Interac and Conscious Economics have teamed up to offer Mindfulness & Money for Newcomers and International Students, a digital learning program that teaches financial literacy and fraud prevention techniques. Continue Reading…

How to find your likely estate value and lifetime tax bill (for free!)


By Ted Rechtshaffen, CFP

Special to Financial Independence Hub

In my role as a Portfolio Manager, Financial Planner and President at TriDelta Private Wealth, the number one question that people ask is “Will I run out of money?”

This question comes from people with a $10 million net worth, a $3 million net worth, and a $300,000 net worth.  There may be different levels of angst involved but they still wonder.

The fundamental issue is fear.  Even if it isn’t rational, there is always a bit of fear about running out of money.  Even if running out may mean different things to different people.

Of course, for those with more wealth, the related question is almost always “Am I paying too much in tax?” and “Is there tax smart things that I should be doing that I am not?”

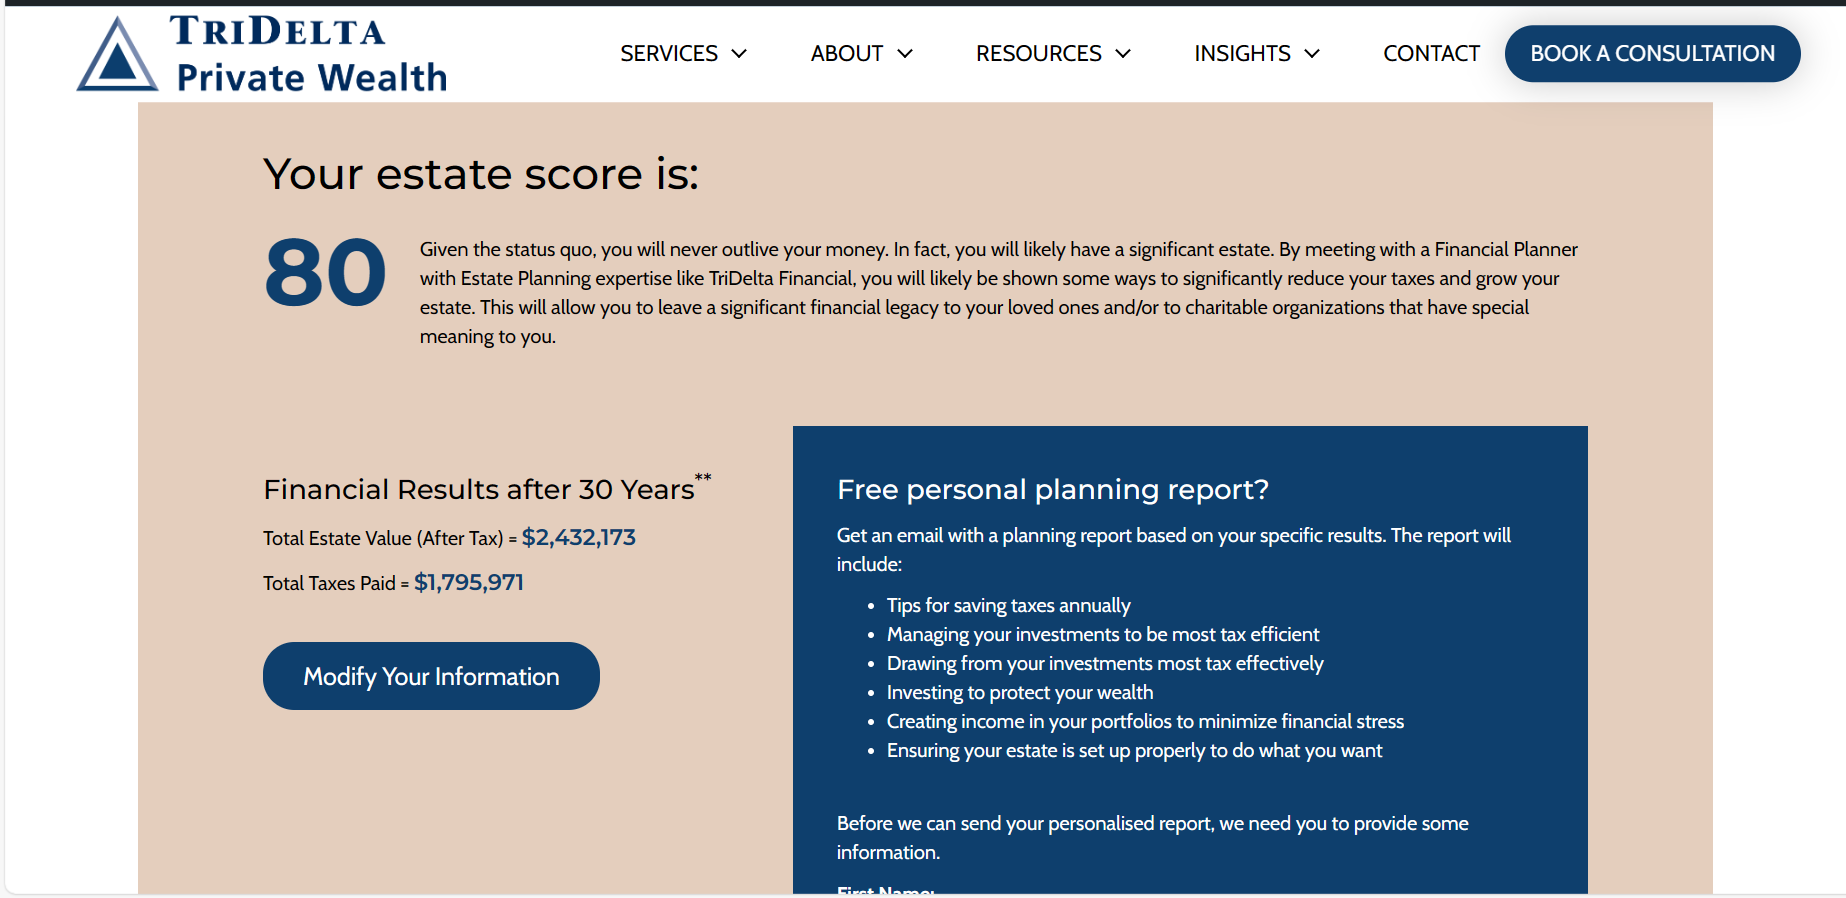
While we do a lot of work in each area with Canadians, we decided to build a free tool to help answer that number one question.  We have done this through our TriDelta My Estate Value calculator.  By someone entering in several core pieces of financial information, the calculator does some pretty heavy lifting.  Behind the scenes are actuarial tables to show life expectancy, tax tables, and a variety of stated assumptions around inflation, real estate and investment growth expectations.

The output is an estimate of your likely estate value in future dollars, along with a lifetime estimate of your income taxes paid.

You will find the calculator here:

My Estate Value Calculator – TriDelta Private Wealth

Donation Calculator

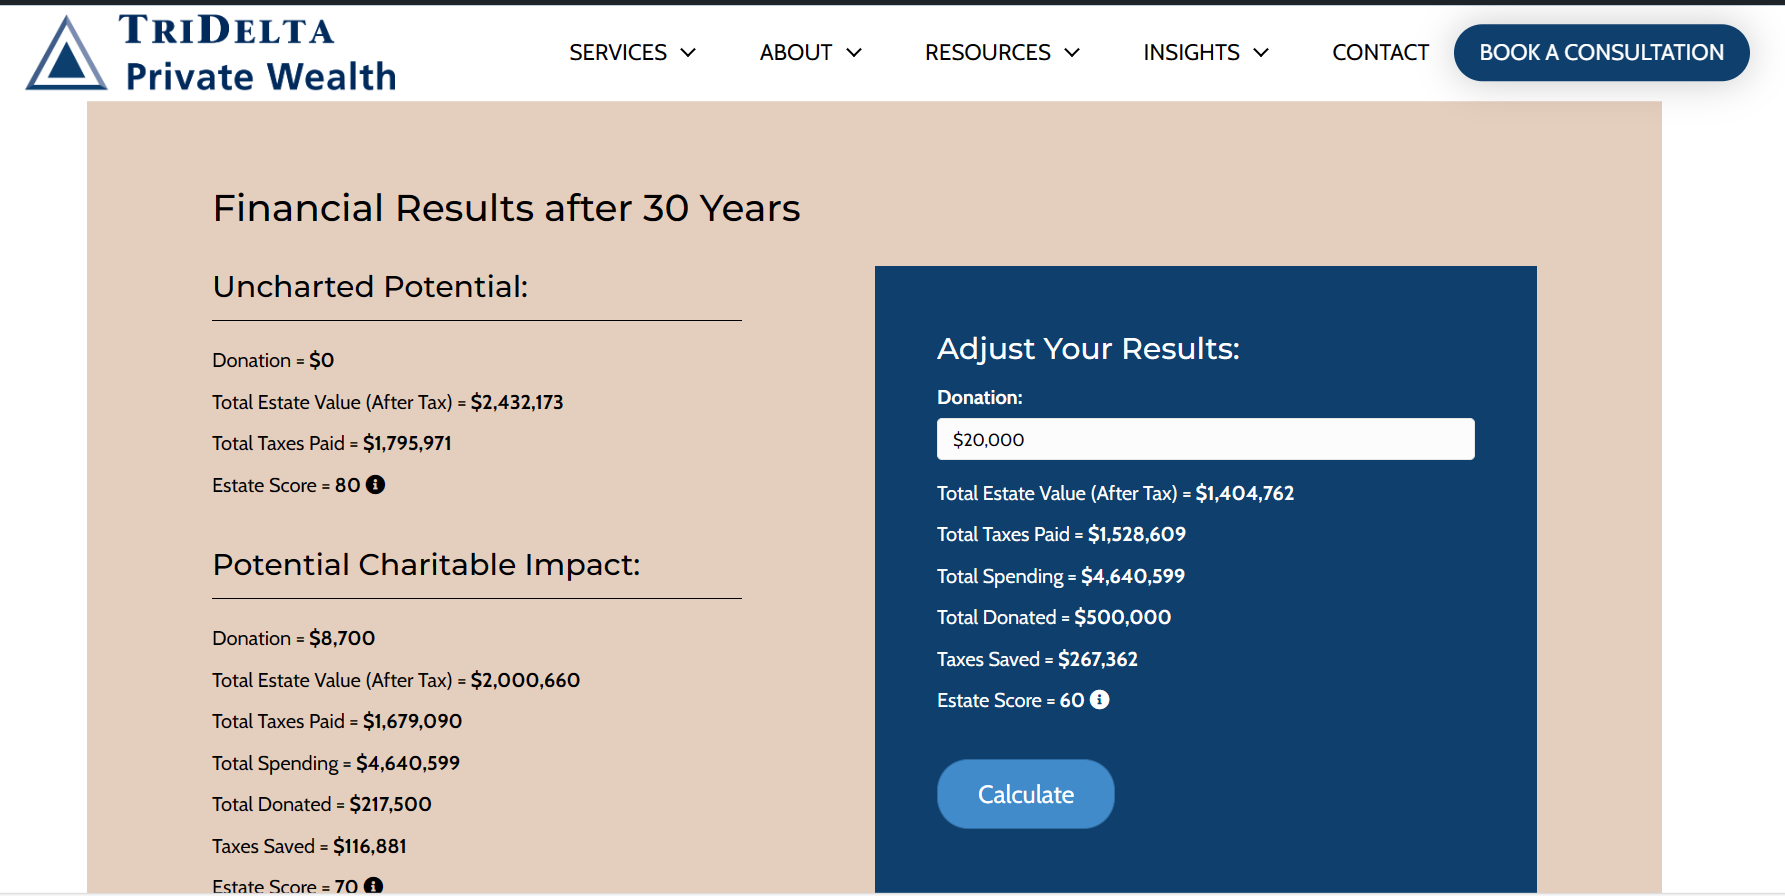
One other tool we have put together is a donation calculator.  It takes the information from the My Estate Value calculator and provides some ability to see the impact of annual charitable giving.  What if you gave $5,000 a year?  What would be the impact to your likely estate value and to your lifetime tax bill?  What if you gave $10,000 or $20,000 a year?  One of the reasons that we put this together is that many Canadians would give more to charity of they felt confident that they could afford to do so.  This calculator helps to show in real time the impact of higher levels of giving.  The link is here: Donation Planner – TriDelta Private Wealth

We have found that even among the free tools online, most are focused on retirement savings, and deliver a monthly savings target.  The My Estate Planner calculator is focused on the years after retirement, and what potential estate you will be leaving to your family and/or charity. Continue Reading…

Most near-retirees would keep working if they could reduce hours and stress

Statistics Canada

Canada’s aging population means more retirees but most Canadians contemplating retiring say they would keep working if they could reduce their hours and stress. That was the top line of a Statistics Canada Daily release issued early in August. It was also the subject of a CBC Radio interview I conducted that aired in multiple cities on Thursday, Nov. 2.  Here’s the link.  Go to Episodes, then Nov. 2nd, then click on the line that says Canadians would choose to work past 65 under certain circumstances.

The interviewer is CBC Business columnist Rubina Ahmed-Haq, who focuses on money, workplace and financial wellness.  The 4-minute interview with me and others touched on most of the topics this site does, including semi-retirement, entrepreneurship, Findependence and Victory Lap Retirement (the latter a book I co-authored with ex banker Mike Drak.). At the outset I clarified that I myself am still working at at 70, albeit self-employed through this web site and regular writing and editing for MoneySense.ca.

I was asked about the FIRE movement (Financial Independence/Retire Early) and I explained that while there are many FIRE proponents who claim to have “retired” in their 30s, in my experience these people have not really retired: rather, they have ceased to be salaried employees with the commuting grind, bosses and meetings and all that comes with it. Most have in reality become self-employed or semi-retired entrprepreneurs: in fact, many of the FIRE bloggers I have read are running web sites that accept advertising, and/or writing books that pay royalties and in some cases are on the speaking circuit accepting speaking fees. Having done all of these myself over the years, that’s not my idea of full retirement!

10% of 70-plus cohort still working at least part-time

Statistics Canada

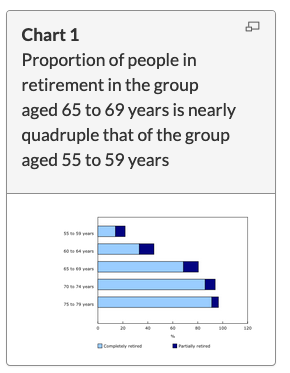
Going back to the Statistics Canada Daily, it reported that in June 2023, 21.8% of Canadians between ages 55 and 59 were either completely or partially retired. That doubles to 44.9% for those aged 60 to 64, and doubles again to 80.5% for those 65 to 69. By the time Canadians reach my age (70), it plateaus around 90% who are at least partially retired.

Interestingly, as I may have alluded to on-air, I can think of several people who are working well past 70, including some prominent journalists and financial gurus. I guess both are seen by proponents as a relatively satisfying occupation, particularly those who like myself do both by writing (or editing) about money.

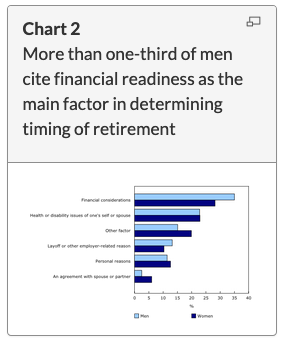
Not surprisingly, for those who are completely retired, the main factor in determining the timing was financial: usually having qualified to start receiving pension benefits. This was cited by 35% of the men and 28.2% of the women who reported being completely retired.

Continue Reading…