Victory Lap

Once you achieve Financial Independence, you may choose to leave salaried employment but with decades of vibrant life ahead, it’s too soon to do nothing. The new stage of life between traditional employment and Full Retirement we call Victory Lap, or Victory Lap Retirement (also the title of a new book to be published in August 2016. You can pre-order now at VictoryLapRetirement.com). You may choose to start a business, go back to school or launch an Encore Act or Legacy Career. Perhaps you become a free agent, consultant, freelance writer or to change careers and re-enter the corporate world or government.

Are you prepared for the new Income Tax rules for Private Corporations?

By John Fisher

Special to the Financial Independence Hub

As many of you are aware, the Canadian government announced new rules in February concerning the taxation of passive income in Canadian controlled private corporations (CCPCs).

The Liberals’ original draft legislation proposed to target tax strategies that have been used by small businesses and professionals since the early 1970s, so naturally the initial announcement in July 2017 drew widespread condemnation.

The government’s concern with the accumulation of passive income-generating investments in private companies stems from the fact that CCPCs pay a blended federal and provincial small business tax rate of 13.5% (in Ontario) on active business income up to the small business deduction (SBD) limit of $500,000 in 2018. This compares favorably to the tax rates on income earned by individuals. On a combined federal and provincial basis, the differential between the highest marginal tax rate on personal income and the small business tax rate ranges between about 36% and 41%, depending on the province in which a CCPC resides.

As a result of this tax rate differential, owners of a CCPC are almost always better off retaining corporate earnings and investing within their corporation. While a similar amount of combined corporate and personal tax is ultimately paid by business owners when monies are withdrawn through dividends, taxes can be deferred until such time as the money is required personally. This effectively allows business owners to temporarily obtain the benefit of investing a larger amount of money than would otherwise be available if they earned the money personally or immediately withdrew profits from their corporation.

One side note worth highlighting here: it is a common misconception that passive investment income earned within a corporation can be taxed at the lower small business tax rate. This is incorrect, as passive income is generally taxed at about the same rate (over 50%), whether earned inside or outside a corporation; so there is no real benefit, per se, from earning investment income in a corporation. Rather, the advantage is that the corporate entrepreneur is able to temporarily invest the amount of taxes deferred by delaying the withdrawal of funds from his/her company.

So what are the new rules governing passive income?

The government has announced its intention to introduce legislation that will reduce the SBD limit by $5 for every $1 of investment income above a $50,000 threshold, beginning in 2019. Once passive investment income exceeds $150,000, the SBD limit will be reduced to zero and the CCPC will pay tax at the general corporate tax rate of 26.5% as opposed to the 13.5% SBD Rate (for Ontario CCPCs).

The $50,000 threshold applies to passive income earned on both legacy and new investments which is important to note given the government’s original promise to “grandfather” any passive income earned from investments previously accumulated

How will the rules affect you as an owner of a CCPC?

Many entrepreneurs are asking if the new rules will result in them paying additional taxes if their corporations generate passive income in excess of $50,000. In most circumstances, the answer is that they will pay more corporate taxes, thereby reducing the size of their tax deferral advantage (from 40% down to 27% on their 2019 corporate income earned in Ontario).

The loss of the entire SBD limit would cost an Ontario CCPC about $65,000 in additional annual corporate taxes ($500,000 x 13% increase in the corporate tax rate). However, once income is paid out by way of dividends from the CCPC, the analysis we have reviewed suggests that the combined personal and corporate tax burden will increase by only about 1% as compared to the current tax regime.

What can you do in light of the proposed changes? Continue Reading…
Is typical retirement advice good? – Testing popular Retirement rules of thumb

Special to the Financial Independence Hub 

You want to retire soon. How should you set up your retirement income?

You talk with some friends, read about it on the internet, and talk with a financial advisor. Are you actually getting good advice?

When it comes to retirement income, most financial advisors rely on a few rules of thumb handed down from one generation of advisors to the next. The rules appear to be common sense and are usually accepted without question.

Do these rules of thumb actually work?

Before giving clients this advice, I tested them with 150 years’ history of stocks, bonds and inflation. I wanted to see if these rules were reliable for a typical 30-year retirement. (The average retirement age is 62. In 50% of couples that reach their 60s, one of them makes it to age 92.) 

These five rules are the “conventional wisdom” – the advice typically given to seniors:

  1. “4% Rule”: You can safely withdraw 4% of your investments and increase it by inflation for the rest of your life. For example, $40,000 per year from a $1 million portfolio.
  2. “Age Rule”: Your age is the percentage of bonds you should have. For example, at age 70, you should have 70% in bonds and 30% in stocks.
  3. “Sequence of returns”: Invest conservatively because you can’t afford to take a loss. You can run out of money because of the “sequence of returns.” You can’t recover from investment losses early in your retirement.
  4. Don’t touch your principal. Try to live off the interest.
  5. Cash buffer: Keep cash equal to 2 years’ income to draw on when your investments are down.

The results: NONE of these rules of thumb are reliable, based on history.

Let’s look at each to understand this.

1.) “4% Rule”: Can you safely withdraw 4% of your investments plus inflation for the rest of your life?

Based on history, the “4% Rule” was safe for equity-focused investors, but not for most seniors.

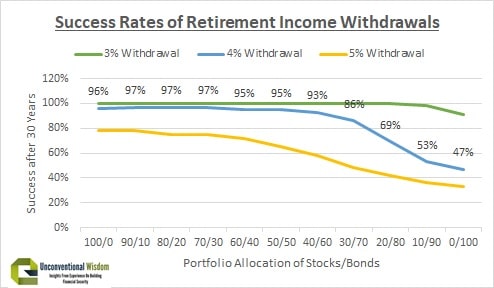
In the results shown in the graphic at the top of this blog, the blue line is the “4% Rule,” showing how often in the last 150 years a 4% withdrawal plus inflation provided a reliable income for 30 years.

The “4% Rule” only works with at least 50% in stocks.

The “4% Rule” worked only if you invest with a minimum of 50% in stocks. Even safer is 70-100% in stocks. It is best to avoid a success rate below 95% or 97%. They mean a 1 in 20 or 1 in 30 chance of running out of money during your retirement.

Most seniors invest more conservatively than this and the 4% Rule failed miserably for them.

A “3% Rule” has been reliable in history, but means you only get $30,000 per year plus inflation from a $1 million portfolio, instead of $40,000 per year.

These results are counter-intuitive. The more you invest in stocks, the safer your retirement income would have been in history.

To understand this, it is important to understand that stocks are risky short-term, but reliable long-term. Bonds are reliable short-term, but risky long-term. Why? Bonds get killed by inflation or rising interest rates. If either happens during your retirement, you can easily run out of money with bonds.

The chart below illustrates this clearly. It shows the standard deviation (measure of risk) of stocks, bonds and cash over various time periods in the last 200 years. Note that stocks are much riskier short-term, but actually lower risk for periods of time longer than 20 years.

Stocks are more reliable after inflation than bonds after 20 years.

Ed’s advice: Replace the “4% Rule” with “2.5% +.2% for every 10% in stocks Rule.”  For example, with 10% in stocks, use a “2.7% Rule.” If you invest 70% or more in stocks, then the “4% Rule is safe.

2.) “Age Rule”: Your age is the percentage of bonds you should have. For example, at age 70, you should have 70% in bonds and 30% in stocks.

Continue Reading…

The Case for Financial Assets over real estate

Billy kicking back on Mexico’s Pacific Coast

By Billy Kaderli

Special to the Financial Independence Hub

When I was a stock broker in California — one of the hottest housing markets in the US — real-estate was my competition. “Everyone” was making money in real-estate, so why would they invest in the stock market?

I needed an angle

I went to the Board of Realtors and got prices for 2-, 3- and 4-bedroom homes in the area, both at the current price and for 10 years prior. I did the math to calculate what annual return these houses were creating for that ten-year span, then compared that to the S&P 500 Index for the same time period.

The index clearly beat all three home styles without the hassles of ownership. Now I had my argument to help people invest in the market.

Ok, that was then and this is now

Using Zillow.com I looked up what the home we used to own was now worth. It was listed at US$862K. Again I did the math and found that over the last 31 years since we bought it, that house has appreciated 6.4% annually. Sounds OK, except that there were property taxes, maintenance and repairs that would need to be deducted lowering that annual return.

Then, I wondered, what if we had put the money to buy our home into the S&P 500? So I calculated that figure also.

Are you ready?

It would be worth 3 million (US) dollars today! Over three times the current value of the home, as the Index produced a 10.46% annual return during those 31 years. Continue Reading…

Why and how Financial Independence is achievable

By Jade Anderson

Special to the Financial Independence Hub

Financial independence can mean different things to different people, but the widespread definition is to be financially secure and on the right track to a safe retirement.

Sometimes people will still need to work in order to maintain their financial independence (aka “Findependence”), but the main idea is that you are free from any debt or outside help from financial institutions. This may seem like something that is unachievable for anyone outside of retirement age, who isn’t well established; however, because of the different types of financial independence, it may not be so difficult after all. Adjusting your spending habits, creating a budget for your self and several other things can lead you towards Findependence, if you know the right things you need to consider.

Reduce unnecessary expenses

Setting up a budget for the long term is extremely important if you’re wanting to become financially independent. If you can cut down on any unnecessary expenses (such as extra food, clothing, and entertainment) in your weekly spending, then you’ll find it will be a lot easier to save. If you are not used to saving money, starting small is important because it will help you establish a pattern of saving properly, and it will be easier for you when you move up to saving more of your average income.

Plan your savings and spending

Planning not only your savings, but also your spending is crucial for ensuring your financial independence. If you have a few debts, and you can make plans to pay off certain amounts by certain dates, you’ll find that the overall debt is easier to pay off, than if you paid it off in a lump sum. Using one of the financial calculators like those on Brighter Finance can help you calculate your budget and repayment periods for your loans, so you can keep track of your money more easily.

Continue Reading…

FP: A look at three retirement income planning software packages

My latest Financial Post column looks at a few retirement income planning software packages that help would-be retirees and semi-retirees plan how to start drawing down from various income sources: Click on the highlighted text to retrieve the full article: How you draw down your retirement savings could save you thousands: this program proves it.

There may be as many as 26 distinct sources of income a retired couple may encounter, estimates Ian Moyer, a 40-year veteran of the financial industry and creator of the Cascades program described in the article.

When he started to plan for his own decumulation adventure, five years ago, he felt there was very little planning software out there that was both comprehensive and easy to use. So, he hired a computer programmer and created his own package, now called Cascades.

While the main focus of the FP article is on Cascades, (available to financial advisors for $1,000 a year; do it yourself investors can negotiate a price directly), the article also references a couple of other programs we have looked at previously here on the Hub: Doug Dahmer’s Retirement Navigator and BetterMoneyChoices.com, the latter currently nearing the end of beta testing.

Dahmer has been writing guest blogs on decumulation here at the Hub almost since this site’s founding in 2014. See for example his most recent one, or the similar articles flagged at the bottom: Top 10 Rules for Successful Retirement Income Planning.

Dahmer says he’s pleased that others are waking up to the need for tax planning in the drawdown years: “Cascades provides a very good, easy-to-use introduction to these concepts.”

Planning for peaks and valleys in spending

Retirement Navigator’s Doug Dahmer

However, Dahmer would like an approach that doesn’t assume yearly spending remains relatively static: his Better Money Choices(available on line for $108 a year) allows for the “peaks and valleys” of spending as retirees pass through their Go-go to their slow-go and finally their “no-go” years.  Most retirees have to plan for sporadic large purchases like renovations or replacement of roofs or furnaces, plus of course vacations with widely varying price tags. Each spending peak represents a tax challenge, while the valleys are where the tax planning opportunities exist. Dahmer likens Better Money Choices to a gym monthly membership and Retirement Navigator to a personal trainer.

Personally, I found going through both firm’s programs a fascinating exercise, very much like putting together a jig saw puzzle. For me, Better Money Choices helps you visualize the final picture you’re trying to assemble, showing how much money you’ll need and when you’ll need it. Cascades provides vivid yearly snapshots of your year-by-year progress in putting the pieces together.

Powered by the Financial Independence Hub.
© 2013-2026 All Rights Reserved.
Financial Independence Hub Logo

Sign up for our Daily Digest E-Mail!

Get daily updates from the FindependenceHub.com straight to your inbox.