Once you achieve Financial Independence, you may choose to leave salaried employment but with decades of vibrant life ahead, it’s too soon to do nothing. The new stage of life between traditional employment and Full Retirement we call Victory Lap, or Victory Lap Retirement (also the title of a new book to be published in August 2016. You can pre-order now at VictoryLapRetirement.com). You may choose to start a business, go back to school or launch an Encore Act or Legacy Career. Perhaps you become a free agent, consultant, freelance writer or to change careers and re-enter the corporate world or government.
“Can you believe it, honey? Friday’s my last day at work! Time sure flies. I can’t wait to start spending all of our free time together!”
Did this thought warm your heart, or get your pulse racing in panic? That probably depends on whether you’ve given some good thought to what you’re doing after retirement.
But what do you actually want to do after you stop working? Your retirement income goals will depend much on your answer to that question, as your financial adviser is apt to tell you.
We’re living longer — and that’s a good thing, if you plan for it
‘Retirement’ wasn’t really a thing, until recently. You lived, you worked, you died … and the world kept turning as youth picked up the baton of life’s track meet. That’s partly the reason pension age was set at 65: few were expected to live long enough to claim it! When the USA passed their Social Security Act in 1935, American men were expected to live to about 58.
But with our longer life spans, you could still be shuffling around decades after you’ve stopped working. According to Statistics Canada and the 2016 Census, “there were 5.9 million seniors in Canada, which accounted for 16.9% of the total population. In comparison, there were 2.4 million seniors in 1981, or 10% of the population.”
There are more retirees than ever! So, our question is a practical one: how do you retire and still fill 40 hours a week?
What Canadian retirees are already doing with their time
Does this all seem inspiring … or overwhelming? Is the room spinning at the prospect of playing shuffleboard and doing yard work for the next two or three decades? Fortunately, we’ve picked up an important idea from doing retirement income planning with countless clients. Continue Reading…
Have you ever thought about seasonal work in retirement? My friend, Kirk, recently leveraged seasonal work to experience something for the first time in his life. He became a cowboy, through a seasonal job at a Dude Ranch.
At Age 58!
You may remember Kirk, he’s visited with us before (including his thru-hike on the Appalachian Trail, his broken foot on the Pacific Crest Trail and the story of breaking his ribs when he Lived Life At The Limits on a mountain bike ride with yours truly). This Fall, he’s heading to Nepal to do some trekking around Mt. Everest. Interesting guy, my friend Kirk, and we can all learn something from the way he lives his life in retirement.
Today, he tells us the story of doing seasonal work in retirement at a Dude Ranch, which he did in the Spring of 2018.
The old military and corporate guy became a cowboy. Well, that may be a bit of an exaggeration, but he did “wrangle horses” for 6 weeks at a Dude Ranch. How cool is that?
Here’s his story…
Working On A Dude Ranch
Kirk. A “FIRE Guy In His Prime”
I promised myself I would write three “potential” blog posts for my friend this year covering what could possibly be my most adventurous year since my retirement began 2 ½ years ago. Caution: I am not the spectacular writer that Fritz is; however, here is my latest adventure …
(Note from Fritz: I don’t know about my writing skills, but I do know that Kirk lives life more “on the edge” than anyone I personally know. Nepal, really? That Kirk guy is nuts!)
When I retired roughly 2 ½ years ago I decided to do away with my “LinkedIn” account. I was cleaning up some old things from my work years and didn’t think I would need a resume in my retirement life. As I started checking off things in my Dump Truck List (Buckets are no longer big enough) I started realizing that I had some skill gaps. Ultimately, I wanted to be a wrangler for a cattle drive in Montana but realized that wasn’t going to happen if I didn’t have some experience handling a horse.
I researched some possible jobs through www.coolworks.com and drafted a list of the qualifications for some of the wrangling jobs which interested me. Much to my surprise, I met them all with one exception:
I had no experience in riding a horse.
Having grown up on a farm really prepared me well for many aspects of the job, but we never had horses. How could I learn to ride a horse, handle the tack, teach the ranch’s customers, etc. if I didn’t know how to handle horses myself? While I suppose I could have paid for the experience — I am FI [Financially Independent], after all — there was something in me that kept gnawing in the deep recesses of my mind.
Thoughts which whispered, and thoughts that led to my decision to pursue seasonal work in retirement:
You have been so frugal all your life to get to FI, is this really how you want to spend your money?
Would you really be able to buy this experience or is this something you have to spend time acquiring skill, talent, and familiarity?
What other experiences do you need now in order to pursue the future adventures of your dreams?
(Note from Fritz: I like how Kirk thinks several moves ahead. Dream for your tomorrow, and identify what you should be doing Today in order to achieve your dreams. Move your life from Good To Great).
After much thought, I decided to venture out to an unknown area for me and listen to the younger crowd who said many of their wonderful experiences were as “Workaway” people. Workaway is simply a web service that connects people who are looking for experience with people that are looking for help. The Workaway people generally work 4 – 5 hours per day, 5 days per week in exchange for room/board and experience. Given that I have plans to travel through Asia in the coming years, this approach could help with some international options as well. I looked into the site http://www.workaway.info and decided to give it a try.
It was somewhat difficult to determine where I would go to gain this experience. I wasn’t sure how it would all work out, so I decided to minimize my risk by choosing a location that:
had good/great reviews by those who participated
was close so if it was horrible I could bail
had more than just myself as a workaway so I could learn from the experience of others
I ended up selecting a Bed and Breakfast Dude Ranch in upstate NY, only an hour away from where I grew up and where my mother still lives. If it was a horrible experience I had a solid Plan B. I would simply bail out and stay with my mom, working around her house to complete some things on her “To Do” list. It would also afford me the opportunity to spend time with some aunts, uncles, and cousins which I had not seen in far too long. Continue Reading…
These days, don’t be surprised to find a senior citizen standing behind the counter of your favourite fast food spot taking your order instead of a braces-wearing teen. What retirement looks like today has changed quite significantly from what it was even just ten years ago, and there’s no stopping this trend. More and more seniors are staying in the workforce, and for many of them, they have no choice.
Last June for Seniors Month, our agency, Credit Canada co-sponsored a seniors and money study that looked at the financial difficulties Canadian seniors are facing; the results, while shocking, were no surprise.
As a non-profit credit counselling agency, our counsellors are on the forefront of what’s happening when it comes to people and their financial hardships, and we are seeing a large number of people who should be starting to settle into their “golden years” still working, maybe even taking on an additional side job, just to pay off their debt, let alone get a time-share in Florida.
When we conducted our study in June 2018, it revealed that one-in-five Canadians are still working past age 60, including six per cent of those 80 and older. And while one third do so simply because they want to — which is fantastic, kudos to you — 60 per cent are still working because of some form of financial hardship, whether it’s too much debt, not enough savings, or other financial responsibilities, like supporting adult children.
The truth is the golden years have been tarnished, and I don’t know if we’ll ever get them back.
Half of 60-plus carrying some form of debt
Many of today’s retirees are living on fixed incomes, making them vulnerable to unpaid debt. In fact, our study revealed more than half of Canadians age 60 and older are carrying at least one form of debt, with a quarter carrying two or more types of debt. What’s even more alarming is that 35 per cent of seniors age 80 and older have debt, including credit-card debt and even car loans.
Staring at the problem isn’t going to help, nor is hiding from it. The best thing we can all do is to face the facts head-on and devise a plan of action that we know will work, whether it’s getting rid of any debt while building up savings, taking on a side job, delaying retirement by a few years, or all of the above.
Sizing up Government support
Before delving into the numbers it’s important to understand what income you can expect to have during your retirement. A few numbers have been compiled here as an example, but if you wanted to get more detailed information you can visit the Government of Canada website and click on the Canada Pension Plan (CPP) or Old Age Security (OAS) pages.
Did you know a looming Bear Market Crisis is approaching?!
I just read it on the internet, so it’s got to be true!
To make matters worse, I just retired a month ago.
Uh Oh! (Am I screwed?)
Today, some reality about Bear Markets, along with 6 steps to consider as you structure your retirement portfolio.
A Looming Bear Market
Ok, I’m having a bit of fun with the “read it on the internet” line, but the reality is that a Bear Market WILL happen. I’m not being prophetic, just stating the facts. Since before the days of the tulip mania in 1637, bear markets have always been will us, and they always will. We’ve benefited from a very nice bull run. We’re being naive if we think that it will never end.
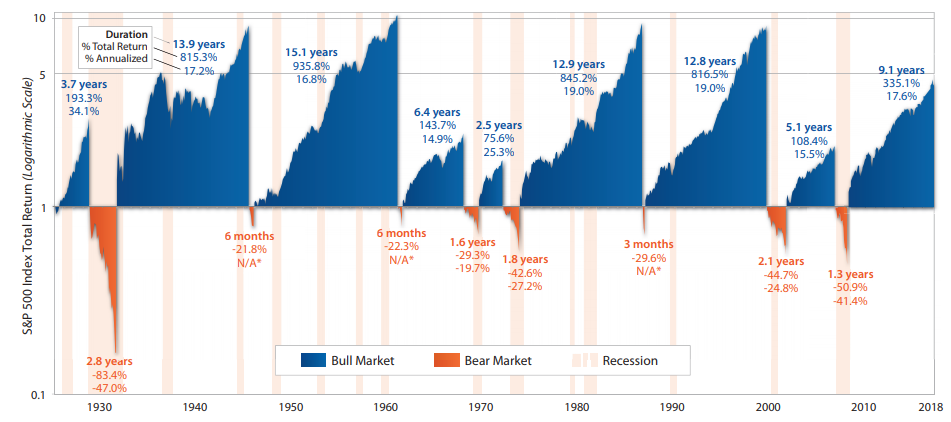
Since 1900, we’ve had 32 Bear Markets, defined as a correction of 20% or more. Do the math, and that averages out to a Bear Market every 3.7 years. The average bear market lasts 367 days (the longest was 34 months!). Here’s what they look like graphically:
The Looming Bear Market Will Drive A Retirement Crisis
“A recession could decimate even substantial retirement portfolios.”
Further, the author goes on to say that Social Security and Medicare, and the resulting increase in taxes, increase in eligibility age and reduction in benefits “would be a disaster” for those dependent on the safety net.
Add to that the Voices Of Worry over the global debt pile up and the underfunded status of many state & local pension funds and things could get really, really ugly.
Maybe I shouldn’t have retired early.
Too late now, I guess I’d better get to work on building a Bear Market Crisis Prevention Plan.
The Looming Bear Market Crisis
We all know a Bear Market is coming. It’s been an increasing theme in the blogosphere, with even the esteemed Financial Samurai taking risk off the table. America’s wealthy are moving to cash. Ben Carlson of A Wealth of Common Sense has 36 Obvious Investment Truths to remind folks that you should protect yourself.
I’m not a panic-driven investor, screaming a scare tactic headline to drive traffic (tho, if you’re reading this, I guess it worked, right?). Rather, I’m reminding folks of the reality of how the markets work and encourage you to think about it as you develop your retirement portfolio strategy. Yes, stocks have historically outperformed over the long-term, and will likely continue to do the same. Just recognize that the road can be bumpy, and plan accordingly to avoid getting bitten by a bear when you can least afford it.
A Bear Market Crisis Contingency Plan
The reality is that bear markets have always been with us, and always will. Unfortunately, we never know when that snake is going to strike, so it’s best to wear snakeproof boots along the path of retirement. Following are some steps I’m taking, as an early retiree, to defend our portfolio against the risk of a bear attack. View them as suggestions, and pick and choose as appropriate for your situation.
Whether you’re a late starter or seasoned saver, the five years or so leading up to retirement just might be the most crucial time to get your finances in order.
Most retirement-ready checklists suggest your final working years is a time to double-down on retirement savings. The idea being that major financial burdens, such as paying down the mortgage and raising children, should be behind you and those savings can be parlayed into big contributions to your retirement nest egg.
High-income earners should look to their unused RRSP contribution room and contribute as much as possible in their final working years. This has the added benefit of generating big tax returns, which can be reinvested into your RRSP or used to pay down any outstanding debts.
Procrastinators have a final chance to break any bad spending habits and set their finances straight. The first step is to draw up a financial plan. Make it a top priority to pay down any remaining debt and get spending under control. You should then have a rough idea when debt-freedom is in sight and from there decide how long to continue working to meet your retirement savings goals.
Retirement income target
The often-used retirement income target is 70 per cent of your final pay, meaning if you earned a $100,000 salary in your final working years then you should aim for a retirement income goal of $70,000 per year. But new research suggests a more realistic retirement income target may be closer to 50 per cent.
Regardless, you’ll need to find YOUR retirement number and determine whether you can reach your income goals through some combination of workplace pension, personal savings (RRSP, TFSA, non-registered investments), CPP, OAS, and/or GIS.
Piecing that puzzle together takes a lot of planning (and still plenty of guess work). No wonder choosing a retirement date can seem like such a daunting challenge!


 Posted By
 By Tea Nicola

 Posted By