Debt & Frugality

As Didi says in the novel (Findependence Day), “There’s no point climbing the Tower of Wealth when you’re still mired in the basement of debt.” If you owe credit-card debt still charging an usurous 20% per annum, forget about building wealth: focus on eliminating that debt. And once done, focus on paying off your mortgage. As Theo says in the novel, “The foundation of financial independence is a paid-for house.”

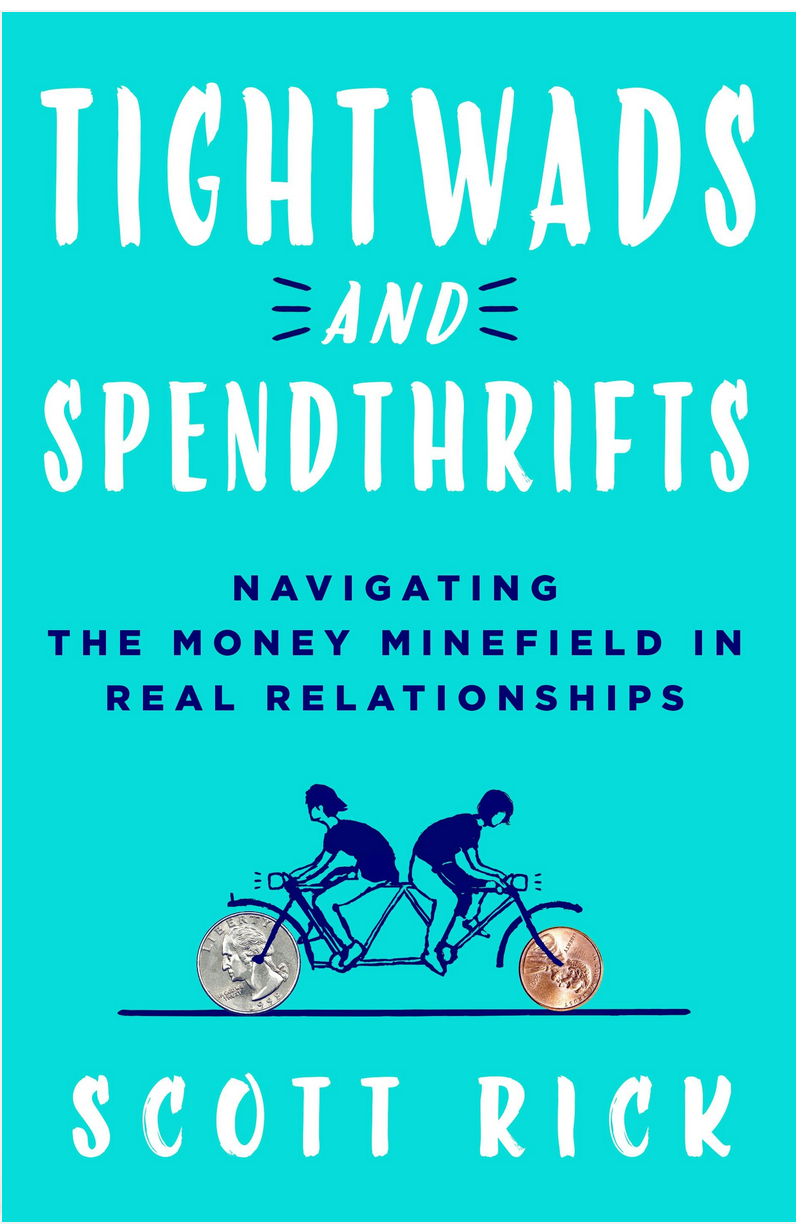
Book Review: Tightwads and Spendthrifts

By Michael J. Wiener

Special to Financial Independence Hub


In his book Tightwads and Spendthrifts, marketing professor Scott Rick promises advice for “financial aspects of intimate relationships.”

What got my attention early is that his guidance “is rooted in rigorous behavioral science.”  Applying the scientific method to human interactions is challenging, but it is generally better than relying on opinions.  The book gives useful insights into how people think about spending money.

The introduction gives a four-question quiz designed to place the reader on a scale from 4 to 26.  Those at the low end of the scale are called tightwads, and those at the other end are spendthrifts.  Roughly half the respondents fell in the middle third of the range and are called “unconflicted consumers.”  Most of the book deals with tightwads, spendthrifts, and their interactions; little is said about unconflicted consumers.

Demographic differences

Extensive surveys revealed some interesting demographic differences between tightwads and spendthrifts. “Tightwads are slightly older than spendthrifts,” but it’s not clear why.  Do people become tighter with money over time (perhaps from getting burned by debt), or are there differences between generations?

“Women were somewhat more likely than men to be spendthrifts, and somewhat less likely than men to be tightwads.  Tightwads were somewhat more likely to be highly educated, and they tended to opt into more mathematical majors, such as engineering, computer science, and natural science.  The most popular college majors among spendthrifts were social work, communication, and humanities.”

How tightwads think

Being a tightwad is not the same as being frugal; “the highly frugal love to save, and tightwads hate to spend.”  “The highly frugal are generally much more at peace in their relationship with money than are tightwads.”

It might seem intuitive that people are the way they are because of how much income they have available to spend, but “in survey after survey, we find no income differences between tightwads and spendthrifts.”  However, “tightwads have far more money in savings and significantly better credit scores than spendthrifts.”

Having higher savings “offers no guarantee that tightwads feel financially comfortable.  Subjective feelings of financial well-being are only loosely related to objective aspects of financial well-being.”  For many tightwads, financial “anxiety stems from economic conditions early in life.”

Tightwads tend to think in terms of opportunity costs when considering spending some money.  In one experiment where some participants had opportunity costs highlighted to them and others didn’t, “spendthrifts were twice as likely to buy the cheaper option” when opportunity costs were highlighted.  “This framing did not influence tightwads.”

While tightwads spend less than spendthrifts in almost every area, “the amount of money both types had donated to charity was the same.”

How spendthrifts think

“Spendthrifts report high susceptibility to shopping momentum and what-the-hell effects.  They commonly report going to buy one thing, then getting carried away.”  “Spendthrifts are significantly more impatient than tightwads.”  Interestingly, spendthrifts tend to understand these facts about themselves, and are not surprised when they later regret their purchases.

“Spendthrifts and compulsive buyers might spend similarly on any given shopping trip, but their underlying psychology differs significantly.  Spendthrifts do not appear or report to be driven by anxiety management or mood repair.”

“Spendthrifts score slightly lower than tightwads on a financial literacy quiz.”  However, Rick says that this is not a defining difference between tightwads and spendthrifts.

Is “spendthrift” an oxymoron?

The word “spendthrift” appears to blend contradictory elements: spending and thriftiness.  However, “thrift here is used as a noun — meaning ‘savings ’— as it was in the seventeenth century.  So spendthrifts are traditionally defined as people who recklessly spend their savings.”

Compensating for financial tendencies

Rick offers ways for tightwads and spendthrifts to compensate for their feelings about money.  The first is to change “payment salience.”  The book offers ways for tightwads to feel the pain of paying money less, and for spendthrifts to feel it more (e.g., by using cash more often).

Tightwads can reframe high-end purchases to think of them as a means to get high quality items.  They can add a line item for indulgences into their budgets to make spending a “to-do” item.  They can also reexamine their finances to confirm that all is well and, hopefully, reduce financial anxiety.

Spendthrifts can be mindful of opportunity costs, try to delay spending (e.g., sleep on it), and set saving reminders for themselves.  Interestingly, spendthrifts might understand “better than tightwads” that “the excitement that comes with a new product usually fades over time,” but this knowledge doesn’t appear to help them reduce spending.

Relationships

When we consider marriages among tightwads and spendthrifts, but not including any “unconflicted consumers,” 58% are between a tightwad and a spendthrift, and only 42% are between two people at the same end of the tightwad-spendthrift scale.  “We tend to marry people who share characteristics that we like in ourselves.  However, a key insight about tightwads and spendthrifts is that they do not particularly enjoy being tightwads and spendthrifts.”

Although some prominent people who advise their followers on personal finance topics consider any money secrets between spouses to be “financial infidelity,” Rick thinks there is room for a small amount of secrecy as long as it’s not the cause of financial shortfalls.  How much secrecy is desirable or tolerable probably varies from one couple to the next.

“Latte factor myth”

Rick adds his two cents to the endless debate on whether we should engage in small indulgences by siding with those who say it’s fine to buy expensive coffee.  Like most others, Rick approaches this debate as a binary choice: lattes are either universally good or universally bad. Continue Reading…
You are too young to retire

By Mark Seed, myownadvisor

Special to Financial Independence Hub

Inspiration for this post arrived from attending a few retirement parties of late with work colleagues, another one as recently as yesterday and a few more to attend this spring.

Is age 50 too young to retire?

What about age 55? Age 60?

After talking to some work colleagues who submitted their retirement letters and who are now moving on, I know their ages. The celebration yesterday was for someone in their early 60s. They talked and yearned about more time at their cottage, doing small home reno projects, and leaving early morning Microsoft Teams calls in the rearview mirror.

They also talked about their desire to retire now since they “had enough” both mentally and financially: support from the latter after working with their financial advisor or planner and doing some retirement math on their own to bridge the gap between spending needs now and when their pension benefits would kick in, at age 65, including their firm intention to take CPP and OAS at that age too.

Although I’m leaping to lots of assumptions here, this makes me believe that the personal retirement savings of some work colleagues (the sum of RRSPs, TFSAs, non-registered investments or other assets) is likely small to modest beyond a workplace pension: in that they needed to work to ensure they were not sacrificing their personal portfolio too much, too soon. I get that. After decades of raising a family, buying a cottage, paying down a mortgage or two along with other expenses I’m sure, it seems my colleague was more than ready to permanently slow down; cut the cord from work and enjoy their time more while they still have decent health. Good on them. 🙂

This individual is however not the first person to mention the following to me:

“Oh, I can’t afford to retire yet but thinking age 63 or so should be fine since that’s when I can get my full OAS and decent CPP income.”

And my work colleague is hardly alone …

In looking at some stats (Source: StatsCan) the average age of retirement is hardly for anyone in their 50s:

You are too young to retire

These are also not easy times to retire…

Rising general inflation, uncertain tax rates, and higher healthcare costs could very well impact many retirees at any age. Myself included. Certainly, starting to save for retirement early and often and getting out of debt faster than most would be enablers – and I hope they have been for us.

You are too young to retire – is early retirement right for you?

Although many Canadians seem to expect to retire between the ages of 60 and 70 above, there is absolutely no hard and fast rules about when you need or must stop working of course.

Your retirement timeline will depend on many factors, I’ve highlighted some milestone ideas below:

3-5 Years Before Retirement

This is where dreams might start becoming a reality. I was there. I wrote about the emotional side of early retirement back in 2021 as my own evidence.

Somewhere between 3-5 years before retirement, it’s probably wise to get some retirement details in order. Accuracy isn’t overly important IMO but the process of planning is. 

I recall focusing on our desired lifestyle and spending habits to go with it: what early retirement or semi-retirement or full retirement might look like:

  • We started estimating our retirement spending levels, our income sources, and inflation factors.
  • We started evaluating our portfolio returns over the last 5- or 10-years.
  • We looked seriously at our sustainable cashflow from our portfolio (passive dividend and distribution income since we’d be too young to accept any workplace pension or any CPP or OAS government benefits).
  • We started tracking our spending in more detail to challenge those spending assumptions.

1-2 Years Before Retirement

As recently as early 2024 for us, things got more serious.

You might recall we became mortgage and debt-free almost 18 months ago.

You might also recall we realized our financial independence milestone last summer. 

In the year or so leading up to any big decisions, more detailed planning kicked into higher gear:

  • We started to explore ways at work to test some semi-retirement assumptions; the desire but also the financial flexibility to work part-time vs. full-time (i.e., could we still make ends meet).
  • We started to look into post-retirement healthcare insurance options, where needed.
  • We started to talk about our purpose (if not working at all) – what would we do with our time?
  • We started to position our portfolio for upcoming withdrawals.

< 1 Year To Go Before Retirement

Although we might be in this timeline, not sure, since part-time work is now occurring with our solid employer (this could continue for both of us??) but this is where the real retirement countdown calendar probably begins for most people…as you strike full-time working days off your calendar: Continue Reading…

Unconventional Wealth-Building Strategies: 10 Surprising Paths to Financial Freedom

Photo by Tony Schnagl on Pexels

Discover unconventional paths to Financial Freedom that go beyond traditional advice. This article presents surprising strategies, backed by expert insights, that can transform your approach to wealth-building. From maintaining your lifestyle despite income increases to investing in non-financial assets, these innovative methods offer fresh perspectives on achieving financial success.

  • Maintain Lifestyle Despite Income Increases
  • Access High-Value Real Estate Through Syndications
  • Build Wealth with Niche Websites
  • Invest in Non-Financial Assets for Growth
  • Profit from Surplus Business Equipment Sales
  • Turn Discarded Inventory into Profitable Ventures
  • Monetize Legal Downtime with Tech Solutions
  • Transform Teaching into Wealth-Building Opportunity
  • Generate Passive Income by Renting Unused Space
  • Leverage Prop Trading Firms for Capital Growth

Maintain Lifestyle despite Income Increases

One unconventional yet effective method I tried to grow wealth and become financially independent is strategically managing lifestyle deflation in alignment with income changes. In simpler words, this means continuing to maintain the same lifestyle and budget even when your income increases, instead of adjusting your expenses alongside it.

I learned to prioritize this in my younger years after seeing people around me struggling to maintain their lifestyles despite rising income. I noticed they were increasing their expenses as their income grew. Most of these expenses were smaller differences that usually go unnoticed but compound to a bigger sum when you see them in total. Examples include subscribing to more services than before, buying more expensive items because they can now afford them, etc. Seeing all this, a thought nagged me often: “What would happen if they saved the raise they got instead of spending it immediately?”

As I learned more about personal finance, budgeting, etc., I started making a conscious effort to maintain the same lifestyle as always even as my salary grew. I funneled the extra sum into various investments instead. Over the years, this habit helped my net worth increase without compromising my quality of life.

Here are some tips I will offer others in this regard:

  1. Automate the transactions into specific accounts: Immediately redirect your extra amount into another savings account for debt repayment and investments. This will help you avoid impulsive spending.
  1. Understand wants vs needs: Take a broader look at your budget, including things you spend on usually. List all the expenses you make and consider which are important and which you can postpone for later since there is no immediate need. Doing this will help you stay focused.
  1. Track net worth monthly: Make sure to track your investments frequently. Seeing your net worth grow will keep you motivated to continue your habit and avoid unnecessary purchases. — Lyle Solomon, Principal Attorney, Oak View Law Group

Access High-value Real Estate through Syndications

One unconventional way I’ve built wealth that surprised me on my journey to Financial Independence is through the strategic use of real estate syndications. While many focus on buying individual properties, I discovered that pooling resources with other investors allowed me to access high-value opportunities I wouldn’t have been able to tackle alone.

This method allows you to invest in larger commercial properties with a group of people, benefiting from economies of scale and shared risks. I first came across this approach through networking with experienced investors and learning about the power of group investment.

My advice to others would be to build a solid understanding of how syndications work and start small with reputable groups. It’s a unique way to scale wealth while minimizing individual risk, and it’s often overlooked compared to traditional property purchases. Collaborating with experienced partners can unlock doors to lucrative projects that wouldn’t be accessible otherwise. — Jonathan Ayala, Licensed Real Estate Salesperson | Founder, Hudson Condos

Build Wealth with Niche Websites

One unconventional way I’ve built wealth that really surprised me was by doubling down on building tiny niche websites. Early in my career, I thought the only path to success was creating huge, authority-style blogs. But after some experimentation, I realized that smaller, hyper-focused sites could generate a steady income without requiring a massive team or overhead.

I stumbled onto this by accident while testing out ideas that didn’t quite fit my main business. A few of these small projects started making a few hundred dollars a month each, and when you scale that up across multiple sites, it becomes something compelling. The magic is in finding a narrow topic where you can be the absolute best resource online, even if it’s something super specific.

For anyone interested, I suggest thinking smaller, not bigger. Find those underserved niches where competition is low, but passion or need is high. Focus on genuinely helpful content, optimize it properly, and be patient. It’s not a get-rich-quick strategy, but it is an incredibly reliable way to build passive income streams.

This approach allowed me to diversify without putting all my eggs in one basket and played a big part in reaching Financial Independence sooner than I expected. — James Parsons, CEO, Content Powered

Invest in Non-Financial Assets for Growth

One unconventional way I built wealth was by keeping a “no-market” year. For twelve months, I chose to remove myself from investing in anything that required speculation, interest, or growth. Instead, I focused on building non-financial assets: time, skill, energy, and relationships. I tracked it like a portfolio: hours of learning, time saved by simplifying routines, days reclaimed from overcommitting, and people I could count on for collaboration. That “quiet compounding” brought in far more than my typical quarterly gains ever did. I walked into the next year with three new paid projects, two solid partners, and almost double the free time.

I discovered it accidentally after turning down a contract that would have pulled me out of integrity. I gave myself permission to step back and see what kind of return I could build without putting money anywhere. I suggest trying this as a 90-day experiment. Track the non-financial gains as seriously as you would your net worth. Value created in learning, trust, and creative space often turns into money later. The catch is, you have to believe it is real before anyone else does. Once you see it, it is hard to go back. — Adam Klein, Certified Integral Coach® and Managing Director, New Ventures West

Profit from Surplus Business Equipment Sales

Purchasing and selling surplus business equipment was much more profitable than previously thought. Initially, it was just a game of turning what companies didn’t want into something useful. But as time went by, I learned what had actual value was an awareness of where the demand was: what buyers were searching for but couldn’t be found easily. That gap became an opportunity.

I became interested in it on a whim when assisting someone with liquidating their lab, and saw its inefficiency. So we built a system around it. My advice? Identify supply chain omissions or inefficiencies in industries that people do not pay much attention to. The more untrendy it sounds, the more opportunities you’ll have if you’re willing to master it inside out. — Joe Reale, CEO, Surplus Solutions

Turn Discarded Inventory into Profitable Ventures

I started buying leftover inventory from failed event suppliers. Half the time they were happy just to offload it for $0.10 on the dollar. I mean, we once picked up $35,000 worth of LED wall panels for $2,800, stacked them in our warehouse, and rented them out per gig for $650 a pop. In under four months, they paid for themselves, and we have since generated over $48,000 in revenue from those same panels. Everyone wants to build wealth from stocks or SaaS. I just bought junk others walked past and turned it into profit. Continue Reading…

How maintaining your Car can save you Thousands

The clatter of an engine, the screech of worn brakes, or the ominous glow of a check engine light are often precursors to hefty repair bills that can drain a bank account. Many vehicle owners view car maintenance as an unwelcome expense, yet a proactive approach to servicing your vehicle can be one of the most effective ways to safeguard your finances. By adhering to a regular maintenance schedule, you’re not just ensuring your car runs smoothly and reliably; you’re actively preventing minor issues from escalating into catastrophic failures that can cost thousands of dollars to rectify, ultimately saving you a significant sum in the long run.

Image Adobe Stock, courtesy Logical Position

By Dan Coconate

Special to Financial Independence Hub

Car repairs can suck the cash right out of your wallet if you aren’t careful. But with regular, proactive care, maintaining your car can save you thousands by helping you avoid surprise bills.

This post breaks down how a few simple habits and a bit of attention can help everyday car owners save more over the life of their vehicle.

Why Car Maintenance pays off

Your vehicle is an investment, and treating it appropriately will pay off in the following ways:

  • Prevents expensive breakdowns: Small problems caught early rarely balloon into wallet-busting repairs. You can save money and avoid the headache (and expense) of having to rent a vehicle. Most importantly, you’ll never be the person stranded with smoke pouring from their engine on a busy freeway.
  • Extends car lifespan: Well-maintained vehicles last longer, delaying the need for a new (and costly) purchase. Instead, you can trade in or sell your vehicle on your terms and timeline.
  • Boosts fuel efficiency: Clean filters, fresh oil, and inflated tires mean fewer stops at the pump. Even if you have good fuel efficiency, the less you have to fill up, the more you save.
  • Higher resale value: Service records and a tidy vehicle earn top dollar if you decide to sell. You can put that money toward your next vehicle, which means you’re ahead of the game.

Key Maintenance Tasks that save Money

Not sure where to start when it comes to maintaining your car to save thousands? Try this checklist:

  • Oil changes: Stick to your manufacturer’s recommended oil change schedule. Old oil leads to engine wear and potentially catastrophic (read: very expensive) failure.
  • Brake pads and fluid: Replacing worn pads is much cheaper than replacing your entire brake system.
  • Air and cabin filters: When clogged, filters make your engine work harder, burning more fuel and costing you more at the pump. Continue Reading…

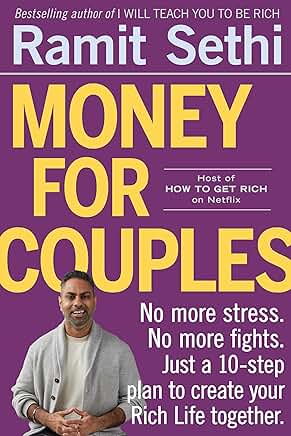
Review of Money for Couples

Amazon.ca

By Michael J. Wiener

Special to Financial Independence Hub

Having listened to a few episodes of Ramit Sethi’s podcast where he helps couples face and conquer their money issues, I looked forward to reading his book, Money for Couples.

In it, Sethi distills his experience helping hundreds of couples into strategies that cover a wide range of problems.

It’s clear that Sethi has the skills and experience necessary to help couples with their financial problems.

However, creating a book to help people solve these difficult issues on their own is a different challenge.  I’m optimistic that this book will be helpful for some couples with big money problems.

For many couples, talking about money is painful and ends in a fight.  A common theme throughout this book is that couples need to find a way to have money discussions that feel good.  To this end, Sethi provides many strategies as well as actual scripts of what to say.  These strategies go a long way to help draw in a spouse who avoids all talk about money.

Money personalities

Although many people think they’re just bad with money, “there’s no question you can get good at managing money, just like you became good at driving and speaking English.”  The way forward depends on your money personality.  Sethi sees four common money types: avoiders, optimizers, worriers, and dreamers (who think some big score will come soon to solve all their money problems).

The book gives specific advice for each money personality.  For example, “Worriers change when they have skin in the game (for example, they manage part of the family finances), when they’re educated about money, and when their finances are extremely simple so they can understand them.”  In the case of dreamers, “I have no advice, because you’re not reading this book.”  Instead, Sethi offers advice to spouses of dreamers.

I saw myself a little bit in the optimizer personality description, but not much in the other personalities.  Even the optimizer personality doesn’t fit well, though: I’ve never tried to maintain a budget and have only tracked spending a few times.  I don’t seem to fit into any of these personalities.  Perhaps, these are the money personalities of people who have money issues, and there are other money personalities for people who don’t have money issues.  I’m not sure.

Moving toward a rich life

Sethi is known for saying people should stop focusing on $3 questions and start focusing on $30,000 questions.  This is the difference between deciding whether to buy $3 coffee vs. big-ticket items like “automating investments,” “minimizing investment fees,” and “creating a debt -payoff plan.”

Some take this to mean that it’s always okay to spend small amounts.  I’m not sure this is what Sethi means.  In any case, as I see it, it’s a mistake to agonize over small amounts every day.  Analyze how you spend money in small amounts, add up a full year’s worth of small amount spending in each category, and then decide if each category of spending fits in your financial plan.  You now have a quick yes or no answer to every type of small amount for the next year.  This frees up some mental bandwidth for thinking about bigger questions.

This shift to thinking about big money questions is an important part of what Sethi calls “designing your rich life vision.”  When a couple agree on what really matters to them and how they want to live in the future, they can take steps to make their vision a reality.  Otherwise, they might just continue wasting money on things they don’t care much about and never get where they’d really like to be.

As I read this book, I decided to do some of the exercises myself, and I squirmed a little as I got to the big questions about what kind of life I really want.  These questions can be daunting, but they’re important.  Even for a retiree like me who has already found the life I want for now, thinking about what I want my future to look like isn’t easy.  Facing these questions and coming to agreement with a spouse matters.

Couples dynamics or … how to stop fighting over money

The book describes three common problematic couples dynamics: sitcom (where couples take jabs at each other to entertain others rather than really communicating), chaser/avoider, and innocent doe/enabler.  For each dynamic, Sethi describes specific ways to break dysfunctional patterns, create meaningful communication, and handle money better.  He also provides scripts of what healthy conversations about money look like.

After solving some of these emotional issues, couples are ready to move into some of the more numerical pursuits, like creating what Sethi calls a Conscious Spending Plan (CSP) and setting up an automated system of bank accounts and credit card accounts.  A CSP lays out what percentage of income should go toward fixed costs, short-term savings, long-term investments, and guilt-free spending.  Putting an end to feeling guilty every time you buy something is a dream for many people!

I’ve seen enough young couples mess up their finances to see the value in Sethi’s methods, but I wonder how many couples out there are like my wife and me.  We kept all our accounts separate, which Sethi doesn’t recommend.  We never automated our savings and just saved what was left over.  This turned out to be a lot of money most of the time, despite the warnings from the Wealthy Barber, Sethi, and others that you must pay yourself first.

Although we’ve made good strides in spending meaningfully, my wife and I tend more toward underspending.  Many joke about how they wish they (or their spouses) were underspenders, but it can be a real problem.  The book mainly focuses on the more common problems relating to overspending, but it does have a subsection specifically about underspending.

Calling out businesses

One thing Sethi does that I find useful and amusing is calling out businesses to avoid.  In one example, a couple closes their Wells Fargo account “because they are one of the worst predatory banks in the world.”

For many people, “their parents never talked about money, so when they reached adulthood, they were defenseless, left to make sense of the world against companies like Wells Fargo and Ameriprise as well as whole-life insurance scammers.”

Specific advice

Sethi advises couples to set a “worry-free spending number.”  The idea is that anything under some threshold, like $20, is automatically not subject to criticism by a spouse.  I find this lacks a time component.  My wife and I have a number like this, but the threshold is very different depending on whether it is a one-off or if it’s daily.  I can buy $1,000 worth of sports equipment a few times a year without a family discussion, but I can’t spend $200 on lunch a few times a week. Continue Reading…