Debt & Frugality

As Didi says in the novel (Findependence Day), “There’s no point climbing the Tower of Wealth when you’re still mired in the basement of debt.” If you owe credit-card debt still charging an usurous 20% per annum, forget about building wealth: focus on eliminating that debt. And once done, focus on paying off your mortgage. As Theo says in the novel, “The foundation of financial independence is a paid-for house.”

How to Create a Crisis Budget that Supports your Path to Findependence

Image by Rilson S. Avelar from Pixabay

By Devin Partida

Special to Financial Independence Hub

No one expects a monetary crisis to strike until it does. Some events that might throw you into a tizzy include losing your job, a pet getting ill and needing emergency veterinary services or the family vehicle breaking down.

To stick to financial goals, you must have a plan for when the current one falls to pieces. Creating a budget that allows you to survive a sudden catastrophe while saving for a home, travel or retirement is the secret ingredient to keeping the nest egg you need.

Amid the Storm: Identify and Prioritize Essential Expenses

An annual emergency savings report by Bankrate, YouGov and SSRS found that 59% of Americans are not comfortable with their emergency savings. For millions of people struggling paycheck to paycheck, anything outside their normal costs spells trouble.

The first thing to do when you experience fewer funds than bills coming in is to assess where you are and how much money you need to survive.

Identify Needs versus Wants

Although your favorite treat from the grocery store may seem like a need, you can likely find something less expensive to fuel your body. Some examples of needs include:

  • Shelter
  • Food
  • Heating and cooling

Once you have a list of the things you can’t live without, you’ll be better able to assess your priorities. In the short term, calling creditors or subscription services to pause payments or end plans can free up enough money to get through the predicament or assess how much money you need now.

Renegotiate Bills

The next step is to call each company to see what flexibility you have. For example, you need utilities to cook, heat your home and use the lights. Many local utility companies will put you on a payment plan so the bill remains the same around the calendar year rather than increasing exponentially during extreme weather.

For credit cards or subscriptions, explain your financial crisis and ask how to reduce monthly payments. Remember that delaying them may increase the total interest paid on the debt, so only use this technique to survive a short-term spending mess.

Cut to the Bare Bones

If you lose your income or have an unexpected expense, you may need to slash spending even more. Look to local resources for help. Food banks can provide sustenance when you lack grocery funds. Talk to your local county, township or public trustee about help with power bills and other resources in your area.

3 things to do to prepare for Financial Emergencies and Unexpected Expenditures

Life is filled with surprise charges. One way to plan for any crisis is to budget for it now. Weathering the next monetary tsunami will feel more like jogging up a hill than crawling up a steep mountain when you’re prepared. Here are some things you can do to be ready:

Create Multiple Streams of Income

Prepare for extra expenses like medical emergencies or the added costs of parenthood by finding ways to bring in more income. If the raises at work are lower than inflation, you can pick up a side hustle and join the gig economy to cover emergency funding.

In addition to diversifying your income sources, you can receive education to become eligible for higher-paying roles at work. Get an online certification, take a course through the local community college or enter management training through the workplace.

Add apps that earn you money for doing things like walking, taking surveys or buying things online. Look for creative ways to bring in extra cash, such as selling art you create or selling used items. Continue Reading…

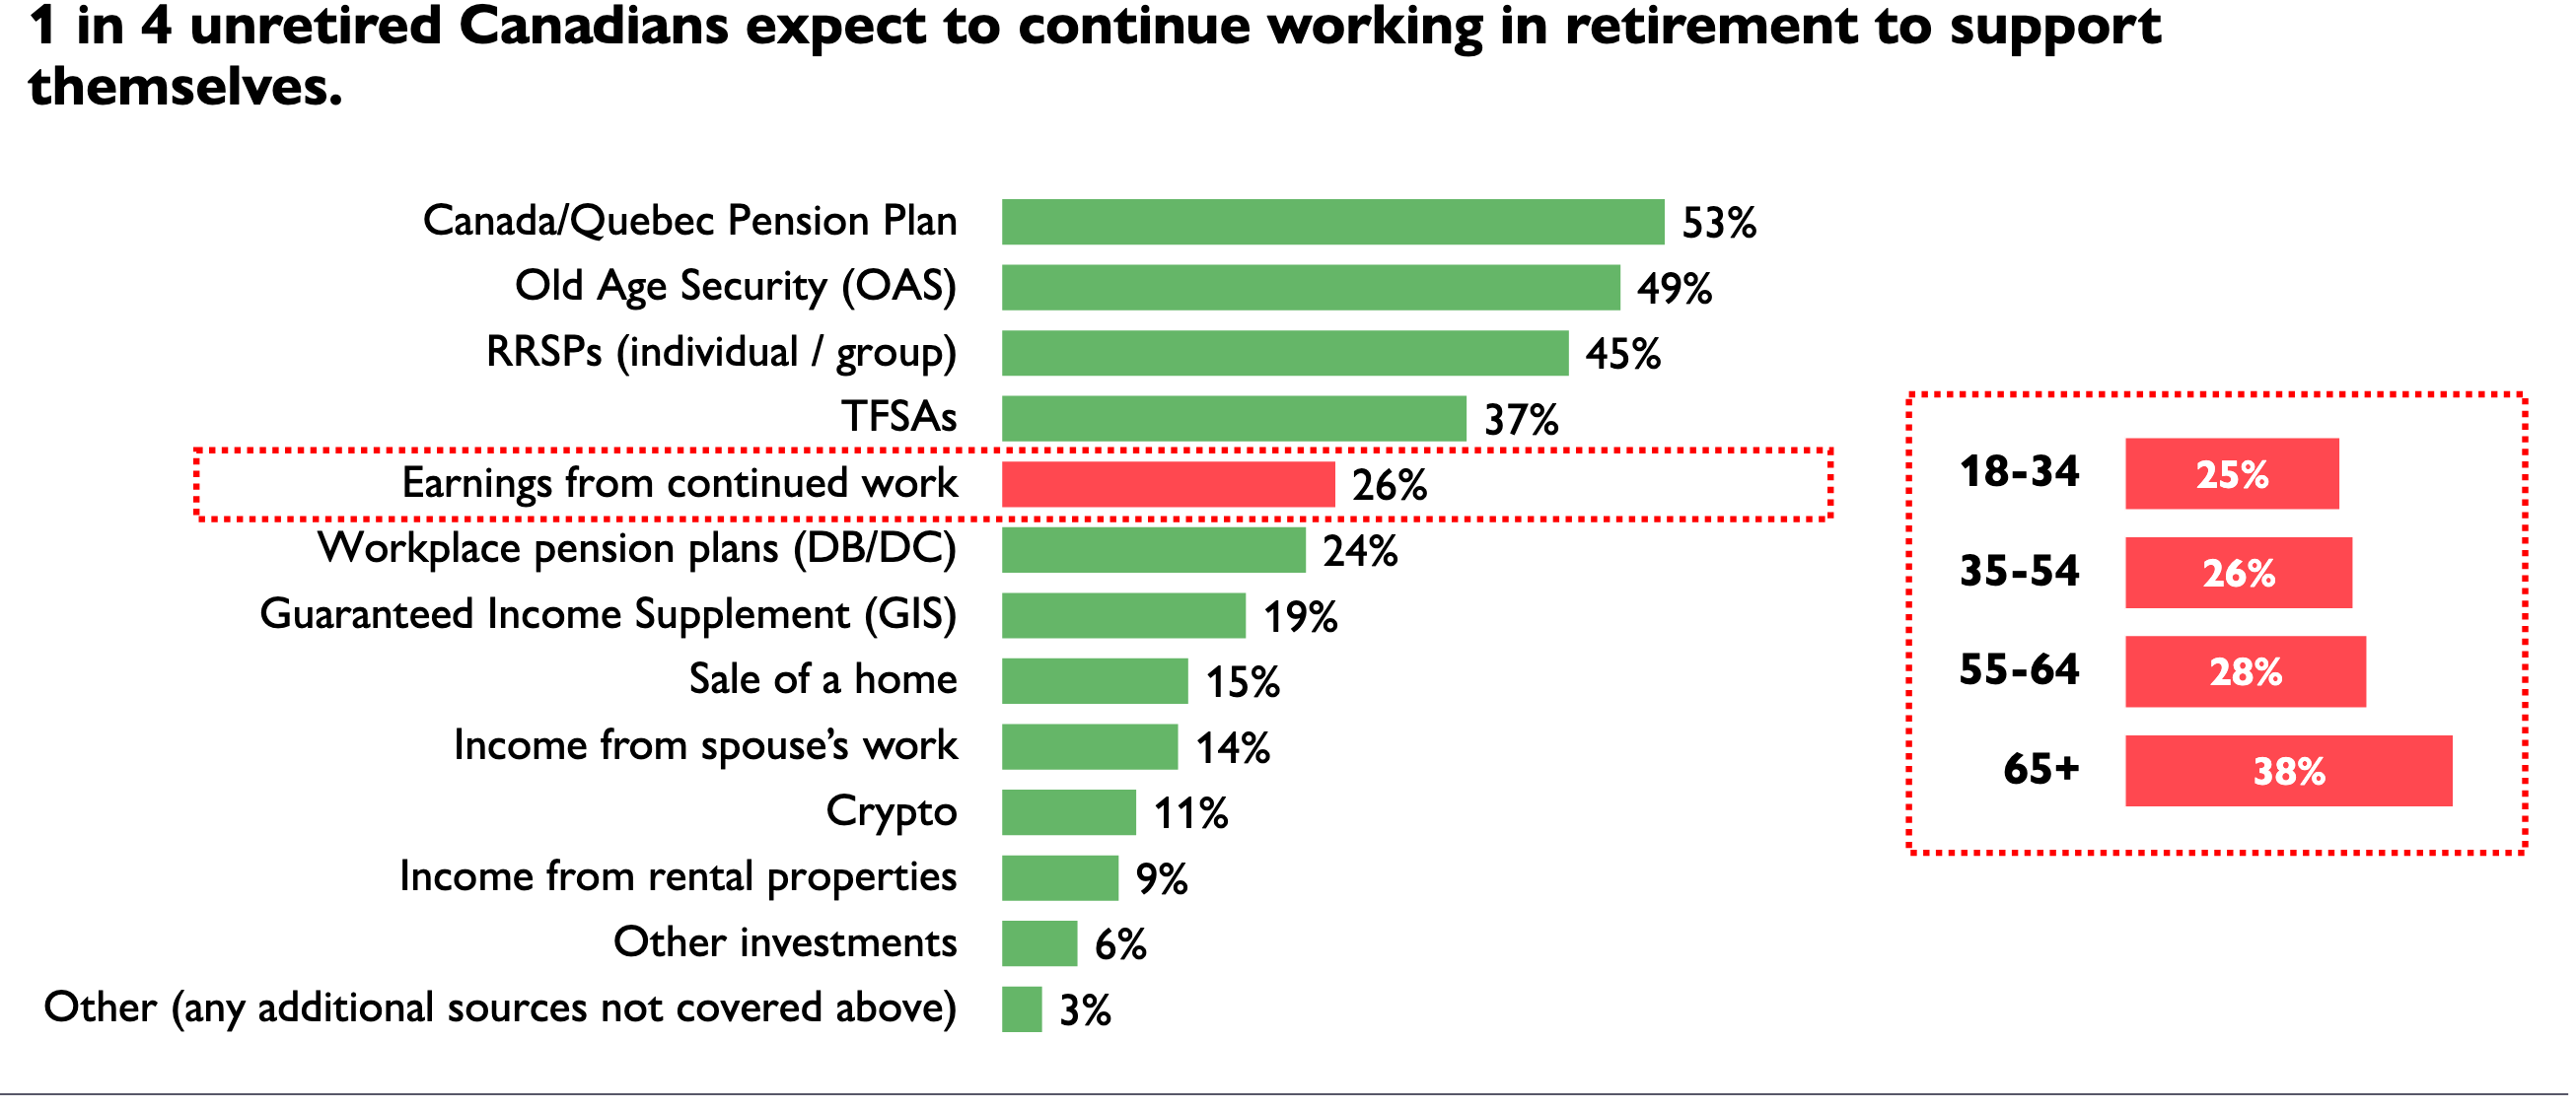
“Unretirement” — more than one in four near-retirees plan to work in Retirement to make ends meet

My latest MoneySense Retired Money column has just been published. You can find it by clicking on the highlighted text here: Why “unretirement” may be the fate of so many Canadians.

Even before the Tariffs threats emerged under Trump 2.0, Canadian seniors were starting to find the economic uncertainty and rising living costs to be unmanageable. No surprise then that many seniors approaching Retirement Age are delaying their exit from the workforce.

According to a report by HealthCare of Ontario Pension Plan, 28% of unretired Canadians aged 55-64 say they expect to continue working in retirement to support themselves financially.  Here’s a screenshot from the HOOPP survey:


The Healthcare of Ontario Pension Plan (HOOPP) commissioned Abacus Data to conduct its sixth annual Canadian Retirement Survey in the spring of 2024.  The latest survey finds “persistent high interest rates and a rising cost of living continue to have a significant negative impact on Canadians’ ability to save and manage the cost of daily life, threatening their retirement preparedness.” While all Canadians are struggling, “women and those closest to retirement are especially hard hit with lower savings and higher levels of financial stress.”

While most Canadians are struggling to save amidst a high cost of living, HOOPP finds women are particularly affected. Half (49%) of all Canadian women have less than $5,000 in savings and almost a third (28%) have no savings (compared to 33% and 17% of men, respectively), similar to the 2023 results


The MoneySense column also looks at more recent Retirement surveys that also reveal anxiety about rising costs of living. One is from Bloom Finance Co. Ltd., conducted by founder Ben McCabe after Trump’s Tariffs started to kick in this year.

A Bloom study conducted with Angus Reid found 46% of Canadians thinking of working part-time in Retirement. That’s in line with a Fidelity survey in 2024 that found half of Canadians plan to delay Retirement. According to the Bloom Report [in March 2024], 67% of Canadian homeowners over 55 were concerned their savings would not sustain their quality of life through retirement. Only 29% considered downsizing or alternative living situations to access their home equity earlier than expected. 59% of the same cohort agreed accessing micro-amounts of their home’s equity would help maintain their desired living standard. Continue Reading…

Saving vs. Investing: Understanding the best approach for Findependence

Image by unsplash

By Devin Partida

Special to Financial Independence Hub

Achieving Findependence [aka Financial Independence] requires a balanced strategy combining short-term stability and long-term growth.

Saving and investing both play crucial roles in this journey, serving different financial goals and timelines.

Explore how you can navigate these strategies to optimize your financial portfolio.


The Role of Saving: Security and Liquidity

Savings are the foundation of Findependence. An accessible savings account provides a safety net for emergencies, such as medical expenses or job loss. Experts recommend maintaining at least three to six months of living expenses in a high-yield savings account or money market fund for quick access.

Here are some key advantages of saving:

  • Risk-free growth: In addition to offering modest interest, savings accounts protect your principal from market fluctuations.
  • Short-term goals: Savings are ideal for upcoming expenses like vacations, home repairs or a new car.
  • Liquidity: Saving provides liquidity during unexpected situations. Certain saving vehicles — like 529 plans — also allow for tax-free growth and withdrawals for qualified expenses.
  • No market risk: Unlike investments, savings are not exposed to fluctuations, making them a reliable choice for safeguarding funds.
  • Psychological benefits: Having a financial safety net reduces stress and fosters confidence in your ability to handle unexpected events.
  • Flexibility: Savings provide liquidity without penalties, making it easy to pivot funds as priorities change.

However, relying solely on saving limits wealth-building potential due to inflation, which can erode the purchasing power of idle cash over time.

The Role of Investing: Growth and Wealth Accumulation

Investing is essential for long-term financial growth, particularly for goals like retirement or major life milestones. By allocating funds to stocks, bonds or mutual funds, you can potentially achieve higher returns that outpace inflation.

Here’s how investing can benefit you:

  • Compound returns: Investments grow exponentially over time due to reinvested earnings.
  • Inflation protection: Historically, investments in the stock market have delivered higher returns than inflation.
  • Wealth generation: Investing enables you to build significant assets over decades.
  • Diversification opportunities: Investments allow you to spread risk across various asset classes, industries and geographies.
  • Passive income generation: Certain investments — like dividend-paying stocks or rental properties — create ongoing income streams.
  • Long-term tax benefits: Investment accounts like individual retirement accounts (IRAs) or tax-free savings accounts (TFSAs) offer tax advantages that amplify growth over decades.

Investing does involve risks, including market volatility and potential losses. It requires a clear understanding of your risk tolerance and financial goals.

Savings and Investments: Finding the right balance

A well-balanced approach integrates saving and investing to address immediate needs and future aspirations. Here are steps to consider:

  • Assess your financial situation: Calculate your emergency savings and allocate sufficient funds to cover unexpected expenses.
  • Define your goals: Short-term goals may require savings, while long-term aspirations like retirement demand an investment strategy.
  • Evaluate risk tolerance: Younger individuals with longer timelines can generally afford higher-risk investments, while those nearing retirement may prefer conservative options.
  • Diversify your portfolio: A mix of savings and investments minimizes risk while capitalizing on growth opportunities.

Practical Tips for Success in Saving and Investing

Finding the perfect balance between saving and investing can seem daunting, but taking specific action steps can make the process manageable and effective. Here are additional practical tips to enhance your financial strategy: Continue Reading…

Canada’s best Asset Allocation ETFs


By Dale Roberts

Special to Financial Independence Hub

When the Canadian asset allocation ETFs were introduced several years ago, the investment community hailed them as “game changers.” That is, the final nail in the coffin for high-fee / low-performance Canadian mutual funds.

The asset allocation ETFs are well-diversifed, managed global portfolios available at 5 risk levels. The fees represent about a 90%-off sale compared to the typical mutual fund. The fees range from 0.17% to 0.25%. It’s a no-brainer for most Canadians. You can open an account with a discount brokerage, enter one ticker symbol (XEQT for example), enter an amount, press Buy and own thousands of companies around the globe. Are these the best funds available in Canada? Yes, that’s a rhetorical question.

Here’s an ode to XEQT from Loonies and Sense.


Cut The Crap Investing is the only blog that tracks the performance of the leading Asset Allocation ETF providers. I also sort them by risk level. For example, you’ll see the performance comparison between the balanced portfolios from Vanguard and BlackRock and the rest of the AA gang. You’ll also see the surprising outlier “winner” that includes modest amounts of bitcoin in its offerings.

Check out the ultimate Canadian asset allocation ETF page. Here’s a teaser: the balanced growth models. They range from 80% stocks / 20% bonds to 90% stocks / 10% bonds. The returns listed are average annual.

Build your own portfolio

While the asset allocation ETFs are the easiest, hands-off way to go, you can certainly build your own ETF portfolio. You’ll save modestly on fees, and you will be allowed some flexibility on how you would like to shape the portfolio. I’ve offered examples of core portfolio models.

Here’s the updated (to the end of 2024) total returns for the core Canadian ETF Portfolios on Cut The Crap Investing. The build-your-own models have outperformed the asset allocation ETFs, in modest fashion. Continue Reading…

7 Tips to Save on Health Insurance in 2025

Image courtesy Pexels: Leeloo The First

By Evan Tunis

Special to Financial Independence Hub

As healthcare costs continue to rise, finding ways to save on health insurance is becoming increasingly important.

In 2025, it is estimated that the average American family will spend over $25,000 a year on healthcare expenses.

This high cost not only affects individuals and families but also puts a strain on the overall economy.


Here are 7 tips to save on health insurance in 2025

Compare Plans

With the rise of online marketplaces, comparing health insurance plans has become easier than ever. Take the time to shop around and compare different plans from various providers. Consider factors such as premiums, deductibles, and coverage options before making your decision. You may find a plan that offers the same coverage for a lower cost.

Consider High-deductible Plans

High-deductible health plans (HDHPs) typically have lower premiums but higher deductibles. This means you will pay less each month for insurance, but will have to pay more out of pocket before your insurance kicks in. If you are generally healthy and do not require frequent medical care, an HDHP could save you money in the long run.

Utilize Preventive Care Services

Many health insurance plans cover preventive care services at no additional cost to the patient. Take advantage of these services — such as check-ups, screenings, and vaccinations — to catch any potential health issues early on and avoid expensive treatments in the future. Continue Reading…