Debt & Frugality

As Didi says in the novel (Findependence Day), “There’s no point climbing the Tower of Wealth when you’re still mired in the basement of debt.” If you owe credit-card debt still charging an usurous 20% per annum, forget about building wealth: focus on eliminating that debt. And once done, focus on paying off your mortgage. As Theo says in the novel, “The foundation of financial independence is a paid-for house.”

More time is a goal worth chasing

By Mark Seed, MyOwnAdvisor

Special to the Financial Independence Hub

“Happy Weekend!” this blog or friends or others will exclaim!

On that note, most of us (myself included) are always so happy to see the weekend arrive, or a given weekday dawn, depending upon your schedule or shift of course to enjoy some well-deserved time off from work.

Yet as I inch closer to fulfilling my semi-retirement dreams (our latest financial independence update you can find right here) I often wonder if every day is going to feel like a Saturday in the years to come.

I mean, part of me hopes so, when I think of time. Finding a much broader, balanced approach to work and fun …

Here are some of the perspectives I’ve been thinking recently when it comes to work, play, time, and to the point of this blog, what does money have to do with it.

If you really enjoy your job, does it feel like work?

While there never seems to be enough time for anything these days outside of work (blame your lost downtime on your social media time for starters!), I’ve often wondered about folks who really, really love their job – does it feel like work to them anymore?

Here are some signs of that:

  • New tasks or assignments don’t annoy you or bother you, in fact, you might get your energy from them.
  • You enjoy seeing the results of your craft frequently.
  • You enjoy working with those around you or people you deliver products and services for.
  • You are continually inspired by work.

I’m sure there are more …

There are definitely elements of the above that apply to my current role with my employer but as I get closer to realizing my financial independence, I must say I’m very much looking forward to the day whereby my most of my time (therefore not money whatsoever) is the ultimate management goal.

While time is money can be true in many corporate circumstances, the inverse is true after you realize financial independence – money has purchased some discretionary, finite time for you to use as you please. Financial independence makes work either far more fun or just simply optional.

Money does buy happiness to a point

Despite rising incomes, standards of living increasing around the world over time, people are also feeling increasingly pressed for time, anxious and stressed about well-being. With this rising income, happiness only increases to a point – surveys from various studies have shown that money only buys so much happiness.

Depending on the study you want to draw from, psychologists have found that modest life satisfaction comes from earning anywhere between $60,000 to $75,000 USD per year. Some families with children of course may need (and want) more, let alone individuals as well.

Time Spent and Money Spent

Now, certainly, if you make more money than this income per year could you be happier? I suppose that is quite possible and very likely for many of us. But my point is based on many studies, considerable orders of money beyond this income-level will not buy the equivalent amount of increased happiness. The relationships you have and the stable family environment you might enjoy, probably do. Your health is your ultimate form of wealth. That well-being will give you tremendous happiness too. In fact, with your health, it has been written and studied that volunteering, just as one example of giving, has been shown to minimize stress, reduce incidence of depression, and reduce long-term cognitive impairment – helping us live longer and more notably, a happier life.

So, while making good money is all well and good; while having a high net worth can absolutely signal to you and others “you’ve made it” happiness unlike money has a tipping point. Money is only part of what might make you truly happy.

A good reminder that any art of comparison to others can be the thief of joy.

Time is the ultimate currency

When it comes to investing, we’ve all heard that it’s time in the market that becomes your best friend (not trying to time the market itself).

That’s because the earlier you start investing, the more time your money has to work for you. Continue Reading…
Understanding the Chargeback Process to ward off Credit-card Fraud

By Gary Bordeaux

Special to the Financial Independence Hub

Proper accounting and cash flow management is critical for both big and small business owners. This seems obvious enough, but when we move from accounts receivable into the world of refunds and chargebacks, the water can begin to get muddy, and it can be more difficult to keep track of where you stand. The first action to take towards fixing and preventing the problems this can cause is to understand what chargebacks are, and what to expect when you are presented with one.

The two types of Chargebacks

If you’re a new entrepreneur, you may be asking “what is a chargeback?” A chargeback is a form of fraud dispute that comes in two basic methods. First, a chargeback can be a transaction that is reversed due to activity that may be fraudulent designed to protect a consumer a business or both. In the second type of chargeback, the credit card company demands a vendor replace or make good a loss incurred by the consumer due to a fraudulent charge.

It’s important to mention early that a refund is very different from a chargeback. A refund is instigated by one or both parties, and usually involves the re-exchange of an item for its purchasing price or value. Chargebacks are inherently fraud mitigation processes that may have additional fees that must be paid by the party deemed at fault, usually the retailer.

Who is involved and what is the process?

The key players in the chargeback process begin with the customer, who usually is the one to dispute a charge. They file a complaint with their credit card’s issuing bank, which may be their local branch or a national finance company that has provided them with their card. The issuing bank takes the concern up with their issuing bank processor, which will verify the account balances of the customer and then approve or reject transactions that have come through any of the four major card networks (MasterCard, Visa, Discover, or American Express).

The card networks are responsible for settlement. Their next step is working with an acquiring bank (or acquirer) that accepts funds for the retailer from the buyer. They are responsible for the settling of additional fees like processing, interchange, or network fees. Their merchant account processor does just what their name implies: process payments for the merchant. These go into the merchant commercial bank account, which is simply the retailers’ account; the destination for funds. But this is where funds can be pulled for chargebacks and given back to the customer.

Reason Codes

When dealing with Chargebacks, it’s important for a business to be familiar with reason codes. Reason codes are the shorthand for the card networks, and signify why a charge has been disputed, resulting in a chargeback. Continue Reading…

New data shows location has a big impact on car insurance

By Andrew Webb

Special to the Financial Independence Hub

We all know that location plays some kind of role in car insurance, and it’s a controversial topic in Ontario. There have been discussions about banning territorial ratings for a while now.

However, it’s been difficult to get a bead on exactly how much location affects those rates. Thanks to a study of 2,800 car insurance policies we now have some facts and figures to work with.

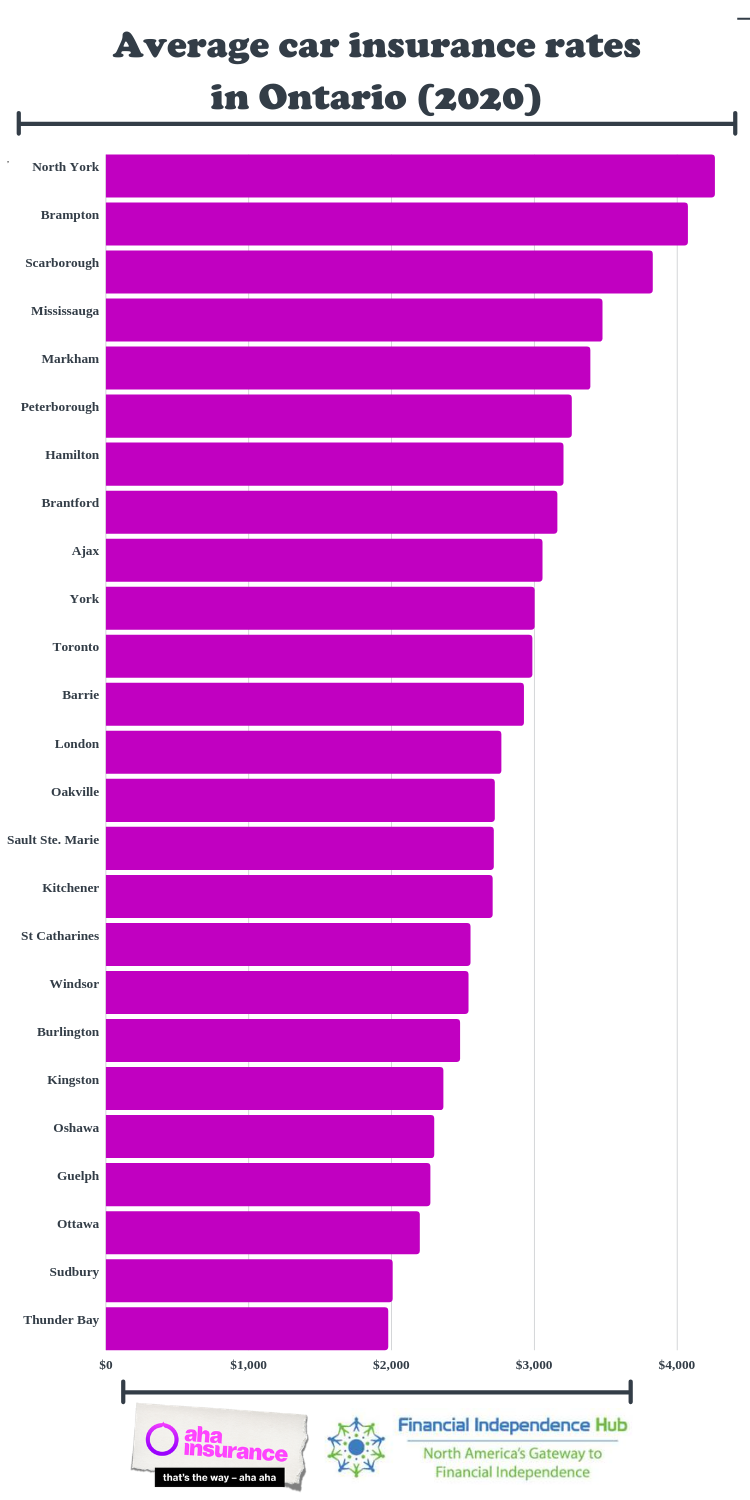
This study reports the average annual cost of auto policies for major towns and cities, so it’s not a substitute for a proper, personalized quote. With that said, the numbers are telling. Location does have a strong correlation to the average rate that Ontarians pay, and that number can vary by more than $2,000 between the most and least expensive cities.

Quantifying average car insurance rates by city

Wasaga Beach comes in with the lowest rate in the study at $1,958, while North York features the highest average rate at $4,261 per year.

That’s a difference of more than $2,000 per year depending on where you live in Ontario. You could pay for a week-long trip to Europe with that money, airfare included.

Here are the numbers, ranked from most to least expensive city:


It’s also worth noting that all of these average prices are higher than the official average price of auto insurance in Ontario as reported by the Insurance Bureau of Canada.

Why do cities have different rates?

Insurance underwriting takes many factors into account, but we forget many of them. For instance, we can see that many of the most expensive cities are in the Greater Toronto Area. Continue Reading…

How to reduce your Household bills

By Jenny Hughes

Special to the Financial Independence Hub

The average American has close to $40,000 [US$ throughout] in non-mortgage debt, also known as “bad debt.” This debt will cost them close to $250,000 in lifetime interest and more than three quarters will die with unpaid balances.

It’s a tragic statistic, and it’s getting worse, which is why so many Americans [and many Canadians too!] are looking into programs like student loan debt relief, tax debt relief, and debt settlement, among others. But as effective as these programs are, the best money-saving methods begin at home.

In this guide, we’ll show you some ways to reduce your household bills, potentially saving hundreds of dollars a year, all of which can go toward clearing your debts.

Get rid of unnecessary subscriptions

North Americans are wasting vast sums of money on subscription services, most of which are underused and unnecessary. It’s such a prevalent issue, that we guarantee everyone reading this will have fallen into the same trap.

Don’t believe us? Here’s a quick test:

Without looking at your bank statements, calculate roughly how much you spend every month on digital subscription services, including TV services, online services, etc.,

If you’re like the average American, you probably calculated a total of between $50 and $80, which is respectable, but probably false.

Did you remember to include Netflix, Amazon Prime, Hulu? What about web domains, Xbox/Playstation subscriptions, loot boxes, and cloud storage services?

The problem with digital subscriptions is that they often cost just a few bucks and are purchased on a whim. The average consumer doesn’t think twice about purchasing them because what’s an extra $5 or $10 a month? But as more of these services are added, that extra $5 turns into $50, and before you know it, you’re spending $600 a year on services you don’t need.

A 2018 survey asked the same question to 2,500 participants and found a massive 84% grossly underestimated how much they spent on digital subscriptions. And this is just the tip of the iceberg, as there are also gym subscriptions, grocery deliveries, and countless other subscriptions that leech money from your bank account every month.

The trick is not to think about the monthly cost but to calculate the yearly one. $5 a month seems like a sensible choice for a new media subscription, especially if it means you can watch that new series everyone’s talking about. But what happens three years down the line when you forget to cancel and only ever watch one episode? You’ve just wasted $150 to consume 45 minutes of TV.

Make your Home more efficient

Install energy-saving lightbulbs, low-flow toilets and shower heads; fix leaky faucets; insulate your doors and windows, and stop relying on costly air conditioning units. All these tips can reduce your monthly bills, but they’re just the tip of the iceberg.

American and Canadian households are filled with electrical devices — TVs, video gaming consoles, computers — and most of these are either active or on standby. They constantly draw a charge, which means you’re paying for them around-the-clock, and those charges can add up.

When a device is not in use, turn it off. This also applies to your heating, cooling, and lighting.

Watch those Food bills

The average family spends close to $3,000 on takeout and restaurant food, and roughly $7,000 on groceries. That’s $10,000 on food, and while it’s a necessity that can’t be avoided, how that money is spent desperately needs to change. Continue Reading…

Yes, you can retire up to 30% wealthier

Questrade touched a nerve with financial advisors with a series of commercials highlighting how lower investment fees over time potentially means you can retire up to 30% wealthier.

Financial advisor extraordinaire Jason Pereira acknowledged that Questrade was right to go after do-nothing advisors who collect fat commissions, but he claimed the 30% wealthier promise was unrealistic and borderline illegal.

Mr. Pereira’s argument is a good one. Advisors like him (and others who put a client’s best interests ahead of their own) can add tremendous value for clients, but not in the way you might think.

The old school notion of a financial advisor is of someone who adds value through their stock-picking prowess. But that argument falls flat when you see the evidence that the vast majority of actively managed funds fail to beat their benchmarks.

Indeed, investors are better off buying the entire market as cheaply as possible using index funds or ETFs.

PWL Capital’s Ben Felix once told me, “investing has been solved … The way for advisors to add value is on planning, behaviour, and transformation.”

With that in mind, I can get behind the idea that financial advisors with this mindset do have a net positive impact for their clients, even after fees.

Which brings me to the point of this article. Canadians have $1.6 trillion invested in mutual funds, most of which are of the expensive, actively managed variety. Those actively managed funds aren’t adding value: the vast majority will underperform their benchmark. Furthermore, most bank-advised clients aren’t getting value in other ways: financial planning, goal setting and prioritization, behavioural coaching, etc.

Traditional advisors are still selling (and charging for) investment expertise, but failing miserably at delivering excess returns while offering little-to-no value for things that would truly make a difference for their clients.

The easy answer is to pair a fee-only advisor with a low-cost investment solution (either a self-directed portfolio of globally diversified ETFs, or through an automated portfolio with a robo advisor). This way, you get the planning, coaching, and behavioural nudges you need to succeed financially, plus the benefit of lowering your investment fees. Win-win.

But the sad reality is that financial inertia is powerful and it’s easier to keep your investments at your bank, along with your chequing, savings, and mortgage. I get it.

Retire up to 30% wealthier without moving your investments

What if I told you that you can still retire up to 30% wealthier without moving your investments to a robo advisor or a DIY investment solution? The answer is sitting right there on the product shelf at your bank: yet rarely if ever talked about by your financial advisor.

I’m talking about index funds. That’s right. Every big bank has a suite of index mutual funds available to investors. These funds charge between one-sixth to one-half the cost of the actively managed mutual funds that are typically sold to Canadian investors.

I’ve monitored and tracked the performance of big bank index funds and their actively managed mutual fund cousins for more than 10 years, and in every single case (when comparing to identical benchmarks), the lower cost index funds outperform the active funds.

So, all you need to do is walk into your bank branch, sit down with your advisor, and ask (no, demand) to move your portfolio from actively managed mutual funds to their index fund equivalents.

Below, I’ll show you the exact index funds to buy to build a 60/40 balanced, globally diversified portfolio of index funds at each of Canada’s five big banks. I’ll compare those index funds to the commonly sold actively managed “balanced” mutual fund.

RBC Index Funds

If you’re an RBC client, chances are you have the RBC Balanced Fund (RBF272) in your investment portfolio. The fund has nearly $5 billion in assets under management and comes with a fee (MER) of 2.16%. Returns have been decent, with a 10-year average annual return of 5.3%. Continue Reading…