Debt & Frugality

As Didi says in the novel (Findependence Day), “There’s no point climbing the Tower of Wealth when you’re still mired in the basement of debt.” If you owe credit-card debt still charging an usurous 20% per annum, forget about building wealth: focus on eliminating that debt. And once done, focus on paying off your mortgage. As Theo says in the novel, “The foundation of financial independence is a paid-for house.”

Borrower and lending practices deepening the burden of debt in Canada  

By Doug Conick, DUCA Credit Union and Chair of Duca Impact Lab

Special to the Financial Independence Hub

Financial institutions play an important role in Canada’s economic well-being. They support growth in personal wealth, job creation and impact the country’s prosperity overall. It is my firm belief that when it comes to the household debt burden of Canadians, there is an even greater role for financial service providers to play. We have a duty to act in the best interest of our clients and proactively contribute to the financial wellbeing of Canadians.

On Wednesday (Jan 15) DUCA Impact Lab released the results of a first-of-its-kind Canadian study to capture the perceptions of Canadian borrowers and lenders, ultimately shining a light on disparities between the two groups. The research uncovers interesting new details about how Canadian borrower and lenders interact with each other and explains how borrowers are impacted by debt. You can find the full report here.

The mounting stress of debt on Canadians

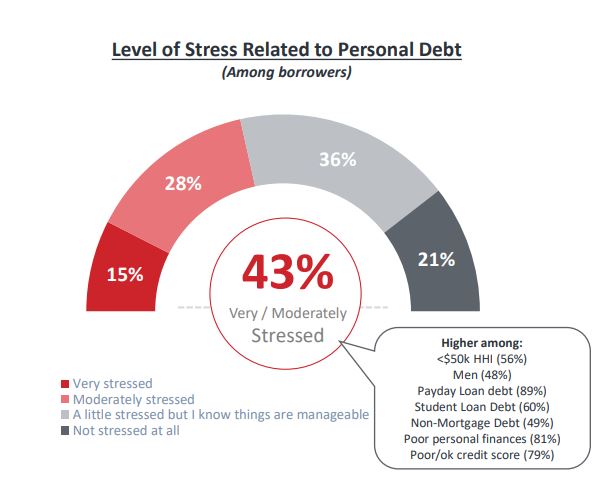
We talked to over 2,000 Canadian borrowers, nearly half of which reported that personal debt has impacted their ability to save and build wealth. It’s concerning that over one-third of borrowers surveyed report avoiding interactions with their financial advisor, despite recent Statistics Canada research which shows Canadians are spending more money than ever on debt payments.

The household debt-service ratio, which represents the percentage of after-tax income used for debt payments, rose to a record 14.96 per cent in the second quarter of 2019. This underscores the increasing need for better understanding among Canadians on how to manage existing debt. Canadians need help but they simply aren’t asking for it.

Our survey also shows debt affects access to healthcare and quality of life. Those surveyed report anxiety, trouble sleeping and poor lifestyle choices like skipping meals, eating unhealthy foods and spending more time alone.
The gap in perception

A quarter of borrowers surveyed say they don’t trust their financial institution to guide them through their debt issues and 37 per cent report avoiding their financial services representatives due to perceived pressures to manage their finances in a way they do not feel comfortable with or because they are recommended products they do not understand. At the same time, 42 per cent of lenders surveyed report they don’t believe their clients fully understand the products they are purchasing.

This demonstrated lack of trust in financial services professionals and gaps in understanding of financial products can lead to a cycle of debt and a missed opportunity to set or prioritize financial goals. Continue Reading…

Don’t make this Life Insurance mistake

Life insurance is a must if you have a spouse or children who depend on your income to get by. But asking a life insurance agent if you need more life insurance is like asking a barber if you need a haircut. Of course the answer is going to be ‘yes’. Indeed, the life insurance business has a long history of commission-hungry agents pushing expensive policies onto consumers who would be better off with simple term coverage.

While you should view any life insurance discussion with a skeptical eye, the reality is that many people are severely under-insured. Most group insurance policies at your workplace only provide coverage for one or two times your annual salary. You might need 10 or 15 times that amount if you have a young family at home.

The other challenge with group life insurance coverage is that it’s not transferable: you can’t take it with you when you leave your employer.

Ending my Group Coverage

That’s the situation I find myself in right now. The group coverage I have with my employer is quite generous at 2.5 times salary. They also offer the voluntary option to add up to an additional $500,000 in coverage at favourable rates (each $100,000 in coverage cost just $4.50 per month). I took the maximum optional coverage and increased my overall life insurance coverage to approximately $700,000. My total premiums cost less than $35 per month.

The rational side of me knew that I’d eventually leave my job and would need to take out a private insurance policy. But I didn’t get around to it. Then I quit my job.

Now I’m scrambling to get an insurance policy in place before the end of the year to avoid any lapse in coverage. First, I performed a life insurance needs analysis. A lot has changed in 10 years. My kids are older (11 and 8 next year). We have a lot more money saved. We have less debt. Do we still need $700,000 in coverage? Do we need more?

A needs analysis considers things like your survivor’s income and spending needs, years of income replacement, personal and household debt, children’s education, non-registered assets, and final expenses. My analysis found that a 15 year term with $600,000 in coverage would be sufficient.

Term Life Insurance quotes

I shopped around for term life insurance quotes using the website term4sale.ca (no affiliation). Continue Reading…

How to keep your Financial New Year’s Resolutions

By Danielle Klassen

(This article originally appeared on the WealthBar blog.)

One of the all-time most common New Year’s Resolutions is to save more and spend less. But about 80 per cent of New Year’s resolutions fail by mid-February. You’ve been there, done that.

This year, you can make it happen. The key? Make a plan and then enlist technology to help keep it on track.

Here are five things you can do today to set yourself up for the best financial year of your life:

1.) Set both short & long-term goals

Often, our long-terms savings goals may be decades out. And frankly, our brains have a hard time relating to these goals, because we tend to think about our future selves as strangers. It’s hard to get excited about saving money if you can’t visualize the reward.

Here’s a pro tip: mixing in some shorter-term goals can help you build better savings habits: and give you the incentive you need to keep going. To keep it manageable, include a target savings amount and a deadline. For example, you might decide to put away $1,000 for a long weekend out of town in three months. That might mean cutting back on day-to-day indulgences, but a weekend away is sure to be more memorable than your daily caramel macchiato.

Once you’re in the habit of spending less, put those lessons towards your long-terms savings to kick your investment contributions into high gear. After all, when you’re saving for a goal that’s decades out, the growth on that money can compound into a much greater value than it’s worth today.

2.) Build a budget

They say money can’t buy you happiness, but the feeling of financial security can positively impact your life satisfaction in a big way. And budgeting is the best way to get to that point.

Think about your money in terms of three buckets: the functional, the fun, and the future. The functional includes all of the things that you’ll need to cover: bills, a roof over your head, food on the table. The fun is everything that goes above and beyond the practical: dinners out, new jeans, etc. The future includes all of those long-term savings goals you set up in step one. Remember: every $1 you put into that bucket, can turn into $5 dollars (or more) in a few decades when invested.

Apps like Mint or You Need a Budget (YNAB) will let you visualize which buckets your money is going into, and can even help make saving feel more like a game.

3.) Give yourself a raise

Want to guarantee a raise this year? Pay yourself first. When you automatically invest a portion of your paycheque, that money can turn into a bigger payout down the road.

To start, make sure to max out any savings matching programs you’re eligible for through your employer. Typically, your employer will set up a group investment account and match your contributions dollar-for-dollar up to a certain percentage of your income. These contributions come right off your paycheque, so you’ll never be tempted to spend that money. Continue Reading…

The Pros and Cons of Store Credit Cards

Photo by unsplash

By Barry Choi

Special to the Financial Independence Hub

Even as another holiday season has arrived and nearly gone, retailers are trying their best to get us to spend money at their stores. One way they hope to achieve this is by offering enticing rewards and promotions when you sign up for their store credit card. This is a great strategy for retailers, but it’s also potentially a good deal for you since store credit cards can help you pocket additional savings.

Since many people already have a credit card, does it make sense to sign up for a new store credit card? Like any other credit card, it really comes down to the pros and cons of the card and how it fits into your spending.

The pros of store credit cards

Instant welcome offers

Although the welcome offers that come with store credit cards aren’t as generous as some other cards out there, sometimes they’re worth paying attention to. For example, the Hudson’s Bay credit card gives you 10% off your first purchase. If you’re buying a big-ticket item, then it might be worth your while to sign up: especially if you shop from Hudson’s Bay on the regular card.

Unlike most credit cards, the savings offered by store credit-card promotions are also instant. You won’t have to wait several statement periods or spend a certain amount (i.e. $3,000 within three months) to access the offer.

  • Great rewards for shopping in their stores

What’s really attractive about store credit cards is their enhanced in-store rewards. This, of course, is only relevant if you happen to shop at the retailer on a regular basis.

For example, with the Triangle Mastercard, you’ll earn 4% in Canadian Tire Money per dollar spent at Canadian Tire stores. There’s no other credit card out there that can beat that return at Canadian Tire, so if the iconic retailer is a regular part of your shopping routine, you could stand to save big with this store credit card.

PC Optimum is another popular retail loyalty program in Canada. If you were to apply for a PC Financial Mastercard, you could earn up to 30 PC Optimum points per dollar spent at Loblaws-owned grocery stores and up to 45 points per dollar at Shoppers Drug Mart: a 3% and 4.5% return respectively. Those earn rates add up to considerable savings on your grocery and pharmacy bills, even compared to what non-retail credit cards offer.

  • Store credit cards are often easier to get

What’s also appealing about store credit cards is that they often have low income requirements and there’s usually no annual fee: so they’re easy to get and free to carry. The reason retailers do this is so you’ll be more inclined to apply. For example, the Costco credit card from Capital One has no annual fee and the application doesn’t list a minimum income requirement.

  • Store credit cards often let you take advantage of unique financing options

Sometimes store credit cards offer special in-store benefits that can’t be ignored, such as Canadian Tire’s credit cards, which offer no interest financing up to 24 months that applies to qualifying purchases of $200 or more at participating stores.

Let’s say an emergency has come up and you’ve had to spend $600 at Canadian Tire. By taking advantage of the no-fee, no-interest financing, you’d only have to pay $25 a month for 24 months with no additional interest or fees. This is handy if you don’t have the funds available to pay off the purchase right away. Continue Reading…

A Look into Tax Debt in the United States

By Mike Brown

Special to the Financial Independence Hub

Despite the financial harm it causes to many, tax debt, or the difference between taxes owed and paid, is an issue that does not receive much coverage compared to other forms of consumer debt like student loan, mortgage, or credit card debt. 

At the end of fiscal year 2018, the Internal Revenue Service (IRS) reported that there were 13.1 million delinquent taxpayer accounts. The combined tax debt in the United States is an estimated US$527 billion, with US$381 billion of that coming from federal taxes and the rest from state-based taxes. 

If a tax debt case goes unresolved, the consequences can be severe, including things like wage garnishment, asset seizure, or an international travel ban. 

Even with its considerable size and consequences, tax debt goes under-reported, but hopefully a new report published by LendEDU and Solvable will help raise awareness. Analyzing over 75,000 unique cases of tax debt, LendEDU’s report broke down tax debt by state, in addition to the most common reasons for tax debt in each state.

New Mexico posts lowest average Tax Debt, Vermont the highest

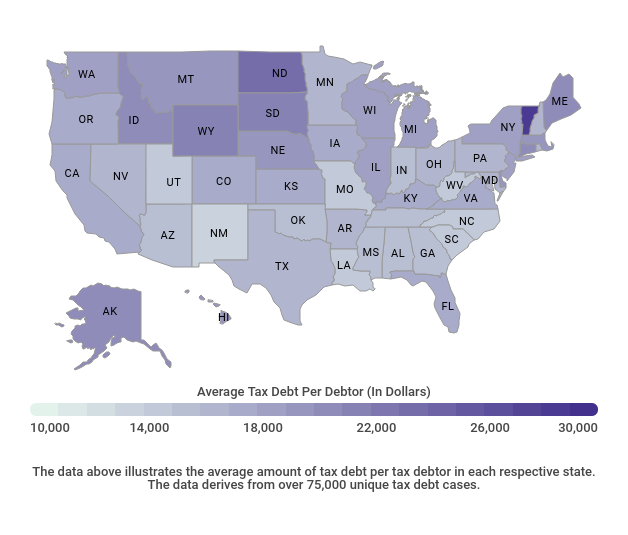
The national average tax debt was US$16,489, and 16 states had a figure below the average, while 29 states and Washington D.C. had higher-than-average tax debt.

New Mexico’s average tax debt of US$13,878 was the lowest in the country; following closely behind New Mexico was West Virginia ($14,325), North Carolina ($14,657), and Louisiana ($14,731). 

On the other end of the spectrum, Vermont’s average tax debt of US$28,862 was the highest and was in the same neighborhood as North Dakota ($23,671), Wyoming ($21,095), and South Dakota ($21,071). 

Regionally, states in the Northeast, Midwest, and West generally had very high tax debt, while states in the South had average tax debt figures on the lower end. 

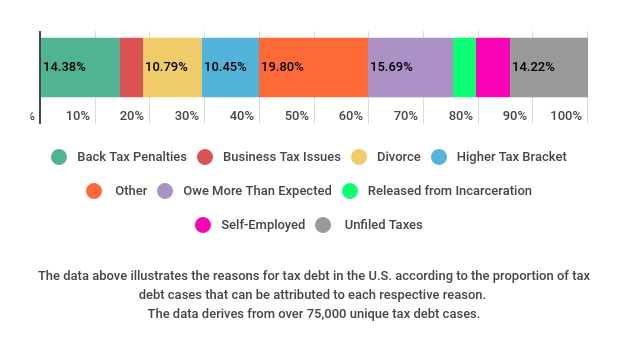
Main Reasons for Tax Debt include Back Tax Penalties and Divorce

A consumer can fall into tax debt for a variety of reasons, like underestimating how much in taxes he or she owes or not accounting for income made as a freelancer. Continue Reading…