Debt & Frugality

As Didi says in the novel (Findependence Day), “There’s no point climbing the Tower of Wealth when you’re still mired in the basement of debt.” If you owe credit-card debt still charging an usurous 20% per annum, forget about building wealth: focus on eliminating that debt. And once done, focus on paying off your mortgage. As Theo says in the novel, “The foundation of financial independence is a paid-for house.”

Home financing options for credit scores

By Michael Plambeck 

(Sponsored Content)

It’s important to go over all your options in regard to home financing to ensure you know what your options are and what’s available to you. This is especially crucial if you are a first-time buyer. Though this can seem like an overwhelming process, knowing what your options are based on your credit score, what types of help are available, and how you can improve your credit score if it’s poor or bad, is the best way to figure out what to do.

How to check your credit score

There are many ways to check your credit score to figure out where you are currently at. You can use a number of institutions and resources to check what your credit score currently is, such as using FICO,or Equifax.

It’s never a bad idea to regularly check all of your credit reports in order to be completely sure that the information is both complete and as accurate as possible. This will help you to know where you need to make improvements, how you can do it, and what your situation is at that point in time. 

Low credit scores and what your options are

Having a low credit score sends red flags to lenders and deems you a credit risk. In short, this will make it very difficult to get a proper credit loan. 

Here is a quick list detailing the range of credit scores and what they mean:

  • 300 – 499: Bad credit
  • 500 – 579: Poor credit
  • 580 – 619: Low credit
  • 620 – 679: Average credit
  • 680 – 699: Good credit
  • 700 – 850: Excellent credit

Having a high credit score means you should have no problem getting a loan from your bank or your credit union. Having a middle credit score, which is a credit score from average to good, you have a wide variety of options available other than your bank or credit union if they deny your application, such as quick loans or by going online.

If you have bad to poor credit, getting credit is going to be very difficult. The fees and interest rates will more than likely be higher than what you can afford, but that’s only if you can get approved at all.

You can do your best to go through the Federal Housing Administration  in order to get a mortgage loan, but they only grant loans through FHA-approved lenders, which may pose a problem. They have a list of requirements that must be met in order to get an FHA mortgage loan, which are listed below for you:

  • A FICO score between 500 to 579, which equals a 10% down payment
  • A FICO score of 580 at the very least, which equals a 3.5% down payment
  • Debt-to-income ratio of under 43%
  • Mortgage Insurance Premium (MIP)
  • The home in question being the primary residence of the borrower
  • Proof of employment and a steady stream of income

However, there are options you can go through in order to get the approval you need for a home loan if you’ve exhausted all your other options, which include going for an FHA mortgage loan. Homeloansforall.com, for example, will help you get approved even if you have bad credit and find the resources you need based on your city and state.

No matter what your credit score may be, the financing options you have in front of you, and what the future may bring, once you are approved for any type of loan, it’s important to keep up with your payments in order to keep the home. 

To help keep up with your mortgage payments and be clear of the debt, check out how to pay off your mortgage in 10 years.
Michael Plambeck, founder and owner of Home Loans For All, bridges the gap between its content team and industry team by being an expert in both areas. Michael is a home loan expert who has worked closely with loan officers and realtors for over four years, and who is engaged in constant continuing education to make sure he’s up-to-date on all real estate laws and regulations.

Suze Orman and the FIRE movement

Photo by QuinceMedia on Pixabay

By Aaron Burdick

Special to the Financial Independence Hub

In a recent interview, Suze Orman provided her opinion about the FIRE (Financially Independent, Retire Early) movement. However, in doing the social media interview, her words were probably taken out of context, and triggered a viral reaction. Everything from Orman being a “shill for the financial industry” to “she doesn’t really want people to be financially independent at all” was thrown around. No surprise, Orman had to step out quickly and put clarity into her words.

First off, Suze Orman makes a point that she’s been advising people to be financially solvent and independent for decades, so she has no outright gut opposition to the idea. Period. But she does add that there should be a balance between spending and saving as well, which is an entirely different idea. Frankly, it’s more about balancing our satisfaction interests versus what we really need to survive and live comfortably. But where the heartburn really kicks in for Orman is on the topic of retiring early. For her, it’s a bit like quitting your job early but having no idea how to pay for health insurance until you reach the age to get Medicare, avoidable and dumb.

What is the Definition of Retirement?

So, it comes down to definitions first. If we are talking about true retirement, for Orman that means stopping working for income altogether. There is no odd job, or a part-time job, or a different job operating a lathe machine; it’s just not working at all for any profit. Second, retirement under the FIRE definition could be 55, but it could be as early as 30 or 40 as well. For the financial planner that Suze is, mathematically, that was pretty much impossible unless one was a millionaire or won the lottery. Mainly, the problem has to do with the fact that people are living really long, and that translates to tens of thousands of dollars needed annually to survive on. Quitting work at 40 or even 50 is just ludicrous.

FIRE’s Definition of Retirement

As it turns out, however, FIRE’s definition of retirement isn’t a complete cessation of retirement. Instead, it involves switching from what you have to do for a paycheck to what you want to do and still earn an income doing it. No surprise, without that clarification, Orman’s original response was not just “no,” but “hell no!” And that caused a kerfuffle on the Internet. In fact, the revised definition is entirely inline with Suze Orman’s general advice direction, pushing people to find what they love doing, but still, earn an income doing it. Some call it FIRE, and Orman calls it Living on Your Own Terms.

So there is commonality with the clarified version of FIRE and Orman’s advice categories. The detail then comes into the “how,” the method used to get from what you have to do for a paycheck to what you want to do. FIRE doesn’t necessarily detail these steps; that’s left up to the user to figure out. This is where Orman finds a gap in the philosophy.

Orman’s Take on Retirement

For Orman, retirement and individual financial independence aren’t about making enough money to quit a job. It’s about keeping stable while finding a life direction more in line with your interests, goals, wants, and happiness. Just getting to retire early with a lump of money isn’t going to translate to happiness per se. And, going back to her financial math, it’s a high risk for even more problems and unhappiness. So, Orman’s not against FIRE per se; but she has an issue with its lack of detail and in that respect, being misleading.


Aaron Burdick is a blogger and personal finance enthusiast with slight “addiction” of planning and organizing whether it’s budget, business or just life in general. Finances, real estate, budgeting and new technological solutions are not the only talking points, that he has his heart set on. Passionate about life. he studies and writes about environmental changes, human rights and quality of life. He is also the proud owner of a Golden Retriever. When he’s not writing articles he’s with his best friend playing fetch or cycling around the streets of Louisville. 

How to get the better of the big Canadian banks

By Larry Bates

Special to the Financial Independence Hub

The big Canadian banks, and by extension the entire Canadian financial industry, occupy a position of paternalistic authority that too many individual investors respect unquestioningly, and even appreciate to some extent. The industry brilliantly capitalizes on a combination of poor understanding of fees, deep loyalty, and misplaced trust by charging Canadians the highest mutual fund fees in the world. This leaves most Canadian retirement investors with 100% of the market risk but only about 50% of market returns.

The impact of these high (and often unseen) investment fees on Canadian retirement accounts is more than a consumer issue, it is a major social issue of our time.

Government pensions will not be nearly enough to provide a satisfactory retirement lifestyle for most Canadians, and guaranteed employer pensions are rapidly becoming a thing of the past. In order to live well in retirement, you now likely need to build significant savings and make those savings grow through investment. So,while previous generations of Canadians with guaranteed pensions could casually observe the markets from the sidelines, most of us today must participate directly in the markets to secure a comfortable retirement.

In other words, you, and only you, have the burden of responsibility to get investing right. But the structure and practices of the investment industry continue to conspire against the ability of the average investor to succeed, to maximize that retirement nest egg. This compromises not only the financial well-being of individual Canadians, but also the health of our retirement system and of our society as a whole.

But there is good news. There are a growing number of very efficient, low-cost investment products such as index ETFs and services such as online discount brokers and “robo-advisors” that enable Canadians to keep a much larger share of their investment returns where they belong … in their retirement accounts. And these lower-cost products and services are offered by the big banks as well as several independent institutions. But you need to know the basics in order to take advantage of these opportunities and build bigger nest eggs. Continue Reading…

Positive if muted returns for most major asset classes in 2019, Franklin Templeton forecasts

Despite Tuesday’s 3% plunge in US stock markets, Franklin Templeton money managers are optimistic most major asset classes will deliver positive if muted returns in 2019.

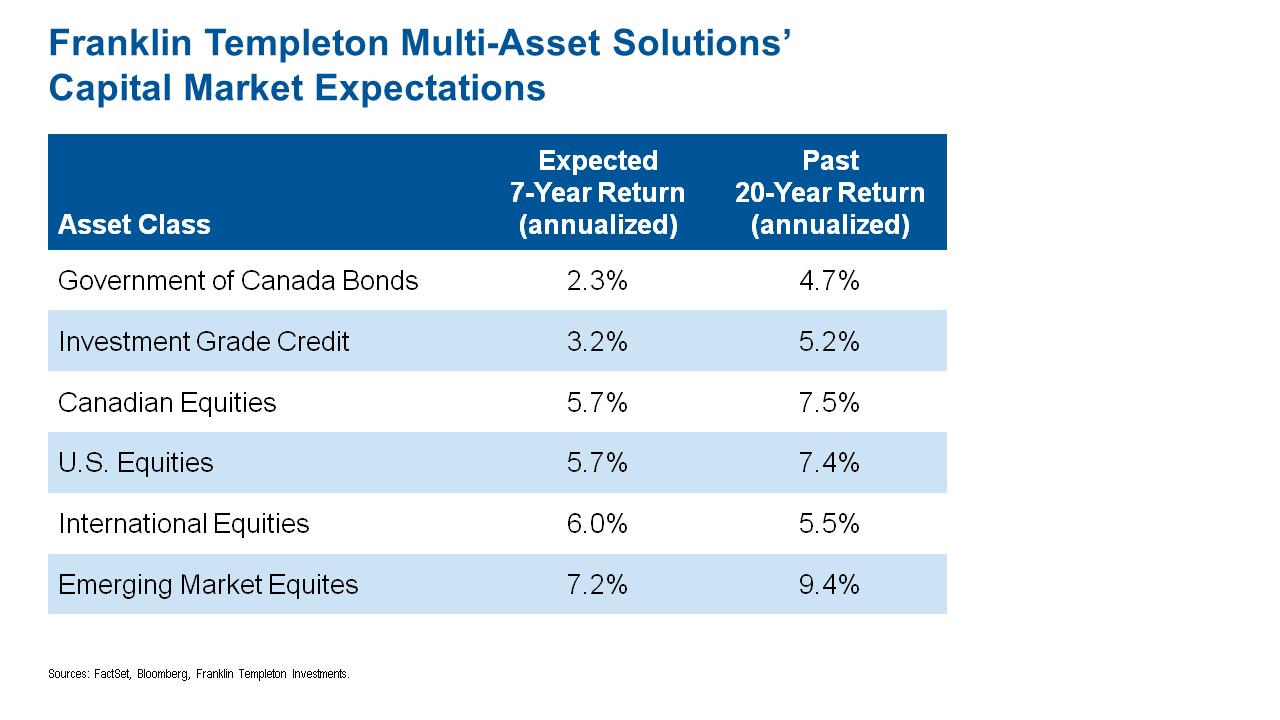
At the 2019 Global Market Outlook event in Toronto, William Yun, New York-based executive vice president for Franklin Templeton Multi-Asset Solutions, projected 7-year annualized returns for Canadian equities of 5.7%, compared to a 7.5% average the last 20 years [as shown in above chart]; 5.7% for U.S. equities (versus 7.4% historically), 6% for international equities (versus 5.5%), and 7.2 versus 9.4% for Emerging Markets. On the fixed income side, he is projecting 2.3% annualized 7-year returns for Government of Canada bonds (versus 4.7% historically the last 20 years), and 3.2% for investment grade corporate bonds (versus 5.2%).

All this is in an environment of continued desyncronized global growth (of 3%) and moderate inflation expectations. Long term, Yun is particularly optimistic about the long term growth of Emerging Markets equities, which at 5% is two-and-a-half times the 2% growth expectation for developed market equities. This optimism is based on positive population growth and labor productivity in Emerging Markets. Globally, inflation “remains muted” and “we don’t see many excesses in the global economy generally.” There are however, some excesses in the U.S. labor market.

More normalized interest rate environment

William Yun, Franklin Templeton Multi-Asset Solutions

Capital spending growth patterns are supportive and trending upwards since the 2016 US election, with the transition from very low interest rates post the financial crisis to a “more normalized interest rate environment.” The opportunity is to reinvest capital to more productive assets, as opposed to allocating to corporate share buybacks.

With respect to central bank balance sheets, markets are normalizing around the world, transitioning from excessive Quantitative Easing to Quantitative Tightening and shrinking balance sheets. Assets quadrupled at the Fed between US$1 trillion in 2008 to $4 trillion today as the Fed committed to buying bonds, with liquidity tapering off. He has similar expectations for the ECB, which has announced the ending of its QE programs, and it’s the same with Japan and China. “Central bankers are pulling back on Quantitative Easing.” There is a “restart of normalization in interest rate policy.”

Rising volatility 

Even as the Dow Jones Industrial Average was in the process of tanking almost 800 points Tuesday, Yun predicted rising volatility after a period of relative calm. In that environment, “investing passively [in index products] has been the way to go but we anticipate volatility returning.” With higher interest rates and more volatility, it may be a time for active management, Yun said, acknowledging his own firm’s expertise in active security management.

Emerging Markets gross domestic product (GDP) continues to rise relative to the rest of the world, from 40% in 1990 to 60% in 2017, and Yun expects that percentage to move higher still. The trend is driven by rising consumption growth for the middle class, which benefits industries like consumer staples and consumer discretionary stocks, technology and even investment management.

Emerging Markets are showing reduced reliance on developed markets, which are slowing. Whereas in 2007 eight of the top trade markets were with the United States, in 2017-2018 China has supplanted the US, with 8 of the top 14 destinations.

In short, Yun sees  a supportive global market for risk assets but lower returns: positive growth and moderate inflation, with increased volatility.

Ian Riach, Fiduciary Trust Canada

Ian Riach, Chief Investment Officer for Fiduciary Trust Canada and a senior vice president of Franklin Templeton Multi-Asset Solutions,  says it makes sense in this environment to make some “dynamic” (i.e. tactical) shifts to long-term Strategic Asset Allocation. Currently, the firm is underweight Canadian equities and Canadian bonds, because the loonie has been getting weaker and Canada is facing a number of challenges ranging from trade to energy to a shrinking manufacturing base, all of which “affects growth going forward.” In the short term, Riach expects short-term interest rates in the United States will be higher than in Canada, “given that they are growing more quickly than us.”

Flat yield curve

Even after the recent rate back-up, “we think Government of Canada bonds are expensive, Continue Reading…

Is Renting throwing away money?

Most people tackle the rent vs. buy problem incorrectly by framing it as the cost of monthly rent versus the cost of a monthly mortgage payment. The argument goes something like, “if your monthly rent costs as much as a mortgage payment on the same or similar property, then it’s a no-brainer to buy the home and build equity rather than flushing your rent money down the drain.”

Others argue that a better comparison looks at the true cost of home ownership, which not only includes the mortgage payment but also things like property taxes, insurance, and maintenance.

However, as PWL Capital’s Ben Felix pointed out in the latest Rational Reminder podcast, neither argument paints a truly fair comparison of rent vs. buy. What you need to look at, he explains, is the total unrecoverable costsin each scenario.

For example, a monthly rent payment is a total unrecoverable cost: an expense that does nothing to improve the renter’s net worth. A mortgage payment, on the other hand, only has partial unrecoverable costs: the interest paid on the mortgage. The other portion reduces your mortgage amount and therefore increases your net worth.

A winning point for home ownership, right? Not so fast.

We need to add up all of those additional costs that a home owner bears (property taxes, insurance, maintenance), plus any upfront money spent on a down payment, land transfer tax, title insurance, home inspection, etc. to close on the home.

There’s also an opportunity cost on the down payment and other closing costs. That money could have been invested instead of put towards buying a home.

Rent vs. Buy: Let’s Do The Math

Let’s look at an example of a renter in Toronto who’s paying $2,000 a month to rent a 575-square foot condo. The same condo is listed for $449,000.

To purchase the condo our renter would need to put down 5 per cent, or $23,450, plus add another $17,062 to the mortgage due to CMHC insurance (required on all mortgages with down payments of less than 20 percent), for a total mortgage amount of $443,612.

Our upfront costs are not done, however, as we need to add in land transfer taxes of $10,910, lawyers fees of $1,000, title insurance of $449, plus a home inspection for $500.

Total upfront costs = $36,309. The opportunity cost of this amount in 25 years at 6 per cent a year = $155,834.

Now let’s look at the unrecoverable monthly costs. The mortgage is amortized over 25 years and has an interest rate of 3.50 per cent. The monthly mortgage payment is $2,215. Of that payment, $1,200 goes towards interest and $1,015 goes towards paying down the mortgage principal.

Then we have property taxes coming in at $375 per month, and we’ll also add the difference between home insurance and tenant insurance, which is $40 per month. We also need to add expected maintenance costs, which we’ll estimate at 1 per cent of the property value per year, or $375 per month.

Total unrecoverable monthly costs (interest, plus property tax, plus insurance, plus maintenance) = $1,990

The unrecoverable costs for the renter and homeowner are nearly identical. The total monthly payment for the homeowner, including property taxes, insurance, and maintenance, is $3,005. Just $1,015 of that is building equity in the home. So, back to the rent vs. buy argument.

Rent and Invest the Difference

We have to assume our renter has an extra $1,015 available in their cash flow each month to invest. What are the expected returns for a 60/40 balanced investment portfolio over 25 years: maybe 6 per cent? Continue Reading…