Debt & Frugality

As Didi says in the novel (Findependence Day), “There’s no point climbing the Tower of Wealth when you’re still mired in the basement of debt.” If you owe credit-card debt still charging an usurous 20% per annum, forget about building wealth: focus on eliminating that debt. And once done, focus on paying off your mortgage. As Theo says in the novel, “The foundation of financial independence is a paid-for house.”

Financial Planning Tips for First-time Homeowners

Buying your first home? Make sure you understand essential financial planning tips, from budgeting and mortgages to tax benefits, to ensure a secure future


Image by Natthawadee, Adobe Stock

By Dan Coconate

Special to Financial Independence Hub

Buying a first home can bring a sense of pride and stability that renting simply cannot match. However, this transition requires you to navigate complex financial waters to ensure long-term success.

You must approach this major purchase with a clear strategy to maintain your financial health. Here are some financial planning tips all first-time homebuyers should consider.

Budgeting for Homeownership

Homeowners must plan a strategic budget for common expenses that come with buying a home. You must look beyond the monthly mortgage payment to include property taxes and homeowners insurance. These additional costs often fluctuate and can significantly impact your monthly cash flow.

Maintenance costs also require immediate attention in your financial plan. Experts recommend setting aside one to four per cent of your home’s value annually for general upkeep.

You should also account for utility bills that often increase when moving from an apartment to a house. Heating, cooling, and water costs for a larger space quickly add up. analyzing past utility bills for the property can help you estimate these expenses accurately.

Saving for Unexpected Expenses

Unexpected repairs inevitably occur during homeownership. A dedicated emergency fund protects your finances when the water heater fails or the roof develops a leak. You avoid relying on high-interest credit cards by having liquid cash reserves ready for these specific events.

Financial setbacks can also arise from non-housing issues like job loss or medical emergencies. A robust savings account covers your mortgage payments during these difficult times. This security allows you to focus on resolving the crisis rather than worrying about potential foreclosure.

Understanding Mortgage Options

Selecting the right mortgage impacts your finances for decades to come. Fixed-rate loans offer predictable monthly payments that help you plan your long-term budget with certainty. Adjustable-rate mortgages might provide lower initial rates but carry the risk of increasing costs over time. Working with a private real estate lender is another consideration and option for homeowners. Continue Reading…

6 Financial New Year’s Resolutions for 2026

Image courtesy TriDelta Financial

By Matthew J. Ardrey, CFP, R.F.P. FMA, CIM®

Special to Financial Independence Hub

As I sit here at the beginning of 2026, I would like to take a moment to reflect on 2025. We had increased U.S. protectionism through tariffs, labour market concerns with the advancement of AI, changing interest rates and another strong year of stock market returns.

With all of these macro themes out of our control, I thought of some of the personal conversations I had with clients during the year about things in their control.

1.) Keep a Positive Cashflow

One of the simplest rules in personal finance is to spend less than you earn. One of the most consistent matters I see when drafting financial plans is people know what they earn and know what they save, but do not have a complete grasp on what they are spending.

A simple way to know what you are spending is to subtract savings from after-tax earnings. Whatever remains you are spending. To take control of that spending though, you need to know where the funds are being spent. Armed with that knowledge, you can decide to continue spending on something, reduce it or cut it out altogether.

Once you are in control of your budget, use it to your advantage to save. Savings are key to wealth creation.

2.) Stay Invested

We have now had several strong years of market performance since COVID in 2020. There is no way we can predict what will happen in 2026. We may have another great year or maybe we won’t. Either way, studies show over and over again that staying invested is one of the most important factors in financial success.

There is a famous phrase in investing, “time in the market beats trying to time the market.“ Aside from how impossibly difficult it is to time them market, this also shows the power of compounding returns over time.

3.) Getting Wealthy vs. Staying Wealthy

Many financial plans I did for new clients this year were for people planning to retire in the next five years and almost every one of them had a portfolio that was at least 80-90% in stocks.

A large allocation to stocks is a great way to get wealthy but may not be the best way to preserve your wealth, especially when decumulating that wealth as part of your retirement plan.

Though we have not seen much of it in recent years, stocks can be a very volatile asset class. In the 2008 Global Financial Crisis, the S&P500 fell more than 50% and took close to six years to fully recover. A similar situation would be devastating to a retirement plan, as not only would the portfolio value fall, but there would also be crystallization of losses, as stocks are sold at losses to fund the retirement.

A well diversified portfolio among asset classes and geographic regions can help mitigate the impact of market declines. Once you have made your wealth, you don’t need homeruns to win the game. You can get around the bases on singles and doubles.

4.) Risk Mitigation: Part 1

In every plan I prepare, I want to create safety margin for my client. It could be using a Monte Carlo volatility analysis in retirement projections or an emergency fund against loss of income or large, unexpected expenses.

The benefits of these safety margins include the ability to survive a negative event, stress reduction and with that the ability to think more clearly to make better decisions. Stress clouds decision making and in a time of crisis, it is clear thinking that is most needed.

Life is never a straight line from A to B. Preparing for inevitable risks that life will bring you is sound financial planning.

5.) Keeping up with the Joneses

There is an immense amount of social pressure to fit in. To make sure you are of a similar status of those around you. But have you ever thought, how do others achieve or maintain that status? Your neighbour with the fancy house, pool and great car make look wonderful on the outside but may be swimming in debt up to their neck to “afford” all of their luxuries.

This is where the real value of a comprehensive, personal financial plan is visible. It will quantify if you can afford the reality you want. It also removes all of the rules of thumb and what works for the average person and focuses on what you need to do to achieve your personal financial goals.

6.) Risk Mitigation: Part 2

Much of financial planning is focused on the happy ending. Sailing off into the retirement sunset and enjoying the life you have worked so hard to earn. Unfortunately, life throws us curveballs and ensuring the risk management side of financial planning is covered is just as important. Continue Reading…

How to turn a Little Money into a Lot of Money

Alain Guillot in Cascais, Portugal, a rich neighborhood.

By Alain Guillot

Special to Financial Independence Hub

Learning how you can turn a little bit of money into a lot of money is a great way to get your finances on the right track. After all, this can help with everything from paying off debt and credit card bills to growing your savings.

With that in mind, here are some top tips that you can use to do exactly that!


Add money to your savings immediately after getting paid

Don’t wait until the end of the month (i.e., when you have spent all your money) to think about transferring cash into your savings account. Instead, transfer a pre-designated amount of money into your savings account each payday. This way, you are reducing the chances of spending money you’d originally wanted to save!

By regularly adding to your savings account, you put yourself in the best possible position to improve your finances in the long term. When setting up a savings account, make sure you choose one with a great interest rate!

Start investing

Whether you’re going to buy and sell Cyrpto currency or going down a more traditional investment pathway, investing money is a great way to turn a little cash into a lot of cash. This can also be a great way to earn passive income, as a lot of the work is out of your hands once you’ve made the initial investment.

Of course, you should make sure to do plenty of research ahead of time so that you are protecting your best interests as much as possible. Remember, while no investments are risk-free, some are more stable than others, and you should not invest money you cannot afford to lose.

Turn your hobby into a side-hustle

Turning your hobby into a side hustle can also help you to turn your finances around, and could even become a real money-maker over time. While it may not seem that way to begin with, you can monetise just about every hobby. Whether you’re a painter or a writer, you simply need to be willing to put the work in to refine your craft and get your name out there. Continue Reading…

Early Retirement Q&A with Dividend Daddy

By Bob Lai, Tawcan

Special to Financial Independence Hub

The Financial Independence Retire Early (FIRE) community is a very supportive and tight-knit one. Because the community is made up of folks who have different backgrounds and different ages, it’s very diverse (not just Caucasian bros from high tech).

Earlier this year, after having been financially independent for a while, Dividend Daddy decided to step away from work to pursue other passions! Since stepping away from work, Dividend Daddy has been travelling around the globe and enjoying life.

I’m happy to have Dividend Daddy joining me today on the latest Early Retirement Q&A.

Q1: Welcome back Dividend Daddy. Congratulations on reaching FIRE and stepping away from full-time employment. Can you tell us a little bit about yourself? 
 

I’m in my late 40s and Canadian. I worked in high pressure roles for my working career and this January, I pulled the plug on full-time work. With return to office mandates clashing with my desire for work location freedom, work was no longer tenable for me so I stepped away. As of July 2025, I’ve been retired for 7 months and travelling a ton.

Tawcan: Amazing stuff!

Q2: You and I utilize hybrid investing, a combination of individual dividend stocks and low-cost ETFs. What made you decide on utilizing hybrid investing in the first place? 

Replicating the Canadian stock market is super easy so I buy individual Canadian dividend stocks and get the dividend tax credit for doing so.

Internationally, in the U.S. and world, it’s very hard to do that yourself so buying an index fund like $VTI and an ETF like $XAW just makes sense.

Q3:What made you decide to finally pull the plug and step away from full-time employment? Walk me through your decision process.

It was a mix of mental burnout and circumstances at my job that led to my early retirement. Of course, I had done the “math” several times and early retirement was possible financially for me.

Being financially independent meant that I had the control to decide my future. If work arrangements no longer suited my needs, I could walk away from them. So, that’s what I did.

At this stage, I wanted time freedom more than I did the next pay cheque.

Tawcan: that makes a lot of sense. In some level I’m probably there too.

Q4: Tell me more about your plans for this new chapter of your life.

Right now, it’s all about travel. I’m doing a ton of it and I have to say, it’s great without having the stress of work or a job on your mind.

I’m not travelling with a laptop for the first time in a very long time. Just my smartphone. Being untethered from your job while travelling is so very freeing, mentally and physically. It’s wonderful.

Q5: Prior to stepping away from full-time employment, did you do a lot of soul-searching to determine what you plan to do in early retirement? Why is this an important process for early retirement? 

I did do some soul-searching and planning. Nothing rigorous, trusting myself to figure it out. Some planning is important because you suddenly have many more hours in a day and week to fill.

For me, I increased the amount of pickleball I play (when I’m at home), I cycled way more at home and abroad, increased the amount of time I spend at my second home in Mexico (to avoid those nasty Canadian winters), and have been travelling a ton more.

Q6: I know you were considering doing part-time work with your previous employer. Did that ever happen? Why or why not? 

I did not end up doing part-time work with my employer. Circumstances changed at my employer and that flexibility was no longer available.

I may end up doing some very limited consulting in the future but that’s not on the table for 2025 or 2026. I do miss aspects of my work.

Q7: Tell me a bit more about your portfolio withdrawal strategy. I believe you plan on withdrawing from non-registered (N) and registered (R), and leaving TFSA (T) untouched for as long as possible? Are you planning to collapse your RRSP early? Or do you envision converting RRSPs to RRIFs at some point?

Not sure completely yet on strategy but I’ve only been early retired for 7 months as of July 2025. I’m definitely spending dividends from my non-registered account with a cash reserve/bucket of $75,000.

I will reinvest most dividends from my RRSP and all of them from my TFSA. I will need to seek professional advice for what to do with my RRSP going forward and whether spending it down is advisable give tax planning purposes.

Q8: Why is it important to “learn” how to spend money and enjoy life a bit more in retirement rather than a “save-save-and-save-some-more” mentality so many FIRE seekers tend to have? 

Life is short. This hits you as you approach 50 years old. My parents’ generation is starting to pass on and I know I’m next in line (hopefully a long way off still). Continue Reading…


The Critical Element of Bonds  

Image from Shutterstock, courtesy Outcome

Pleased to meet you
Hope you guess my name
But what’s puzzlin’ you
Is the nature of my game

  • Sympathy for the Devil, by The Rolling Stones


By Noah Solomon

Special to Financial Independence Hub

Historically, bonds have offered investors two main benefits. Firstly, their yields provided a reasonable, if unspectacular return. Secondly, they offered diversification value, muting overall portfolio losses during bear markets.

In my view, it is the second attribute that is the most important. In relative terms, bonds are not particularly useful for providing investors with strong long-term returns (that’s equities’ job!). So, by process of elimination it follows that the primary function of bonds is their diversification value.

When comparing equity strategies, one should compare their relative returns, volatilities, Sharpe ratios, drawdown characteristics, etc. However, given bonds’ primary purpose of providing diversification, an extra layer of diligence is required when evaluating bond strategies. Specifically, you should analyze their differing correlations to equities, and by extension their varying abilities to offset stock price declines during challenging environments.

There is no Free Lunch Part I

Economist and Nobel Prize recipient Milton Friedman famously stated, “There is no such thing as a free lunch,” which means that every choice has a cost, even if it’s not immediately obvious.

Traditional bond mandates each have their individual advantages and pitfalls with respect to returns, risks, and diversification properties. In terms of the tradeoff between risk and return, history strongly suggests that there is no clear free lunch to be had.

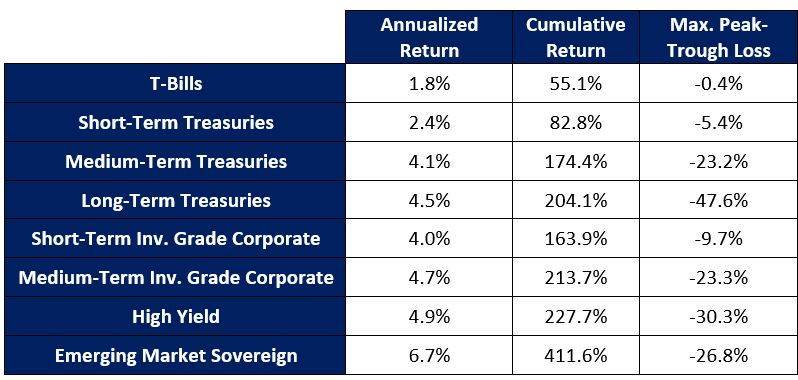
Risk vs. Return by Bond Type: 2000 – 2024


As the above table illustrates, there is a clear relationship between the returns of the various segments of the bond market and the maximum losses that they have sustained over the past 25 years. If you want extra return, you can reasonably expect to suffer larger losses in bad times. That being said, large losses in bond holdings are generally not what investors want or expect.

There is no Free Lunch Part II

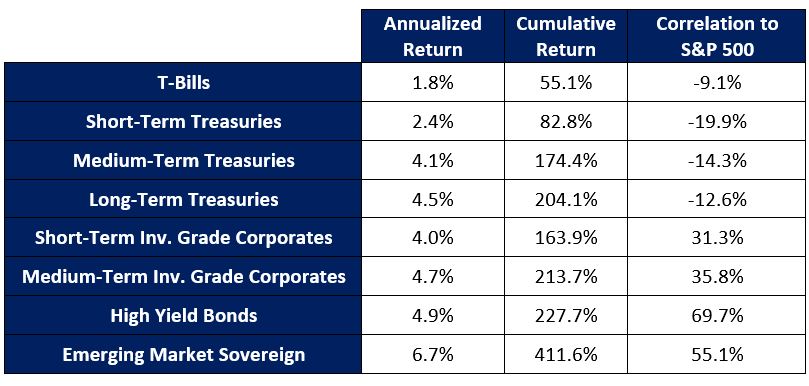
Not only is there no free lunch with respect to the tradeoff between risk and return, but there is also none when it comes to diversification value. Higher returns are not only associated with larger losses but are also associated with higher correlations to equities.

Return vs. Correlation to Stocks by Bond Type: 2000 – 2024

Bonds that offer higher returns have a greater tendency to move in tandem with stocks, thereby providing less ability to mitigate stock losses during bear markets. In contrast, lower-return bonds possess greater diversification properties and thus are better equipped to offset stock-price declines during times of equity market turmoil.

None of the above: Sometimes there’s Nowhere to Hide

Notwithstanding the fact that higher-return bonds have on average suffered more severe losses and offered less diversification value than their lower return counterparts, these relationships have exhibited significant variations across different bear markets. Continue Reading…