For young couples starting families, buying their first home and/or other real estate. Covers mortgages, credit cards, interest rates, children’s education savings plans, joint accounts for couples and the like.
Even when parents try to shield their children from financial worries, a new study suggests kids are hearing more than parents realize.
As the cost of living continues to squeeze Canadian households, a new survey from Vanguard Canada suggests the strain isn’t confined to parents’ bank accounts; it’s also shaping how their children think and feel about money too.
The survey of just over 1,000 Canadian parents of children under 18 found that households that talk openly about money raise more financially literate kids, while households that avoid the subject may be doing more harm than good.
The Instinct to Protect backfires
Many parents try to keep financial stress away from their kids. Among parents who describe themselves as financially stressed, more than two thirds said they feel pressure to hide their worries from their children, and roughly a third said they avoid discussing money at home altogether.
But the survey suggests that instinct doesn’t work the way parents hope. Seven in ten financially stressed parents said their children overhear money conversations anyway. In fact, those children were found to be nearly five times more likely to feel anxious about money than their peers.
Sal D’Angelo, Head of Vanguard Investments Canada, said children pick up on far more than parents assume, even when adults try to keep financial matters private. He framed early financial education as key to helping the next generation build healthy money habits.
A Literacy Gap that starts early and closes late
The survey also points to a timing problem. Households where money is discussed regularly produce children with markedly stronger grasp of core concepts like banking, debit and credit, which is nearly three times higher comprehension according to the findings.
Yet the majority of parents said substantive money conversations don’t begin until their child is between 15 and 18 years old, well after attitudes toward money have already started to form. Continue Reading…
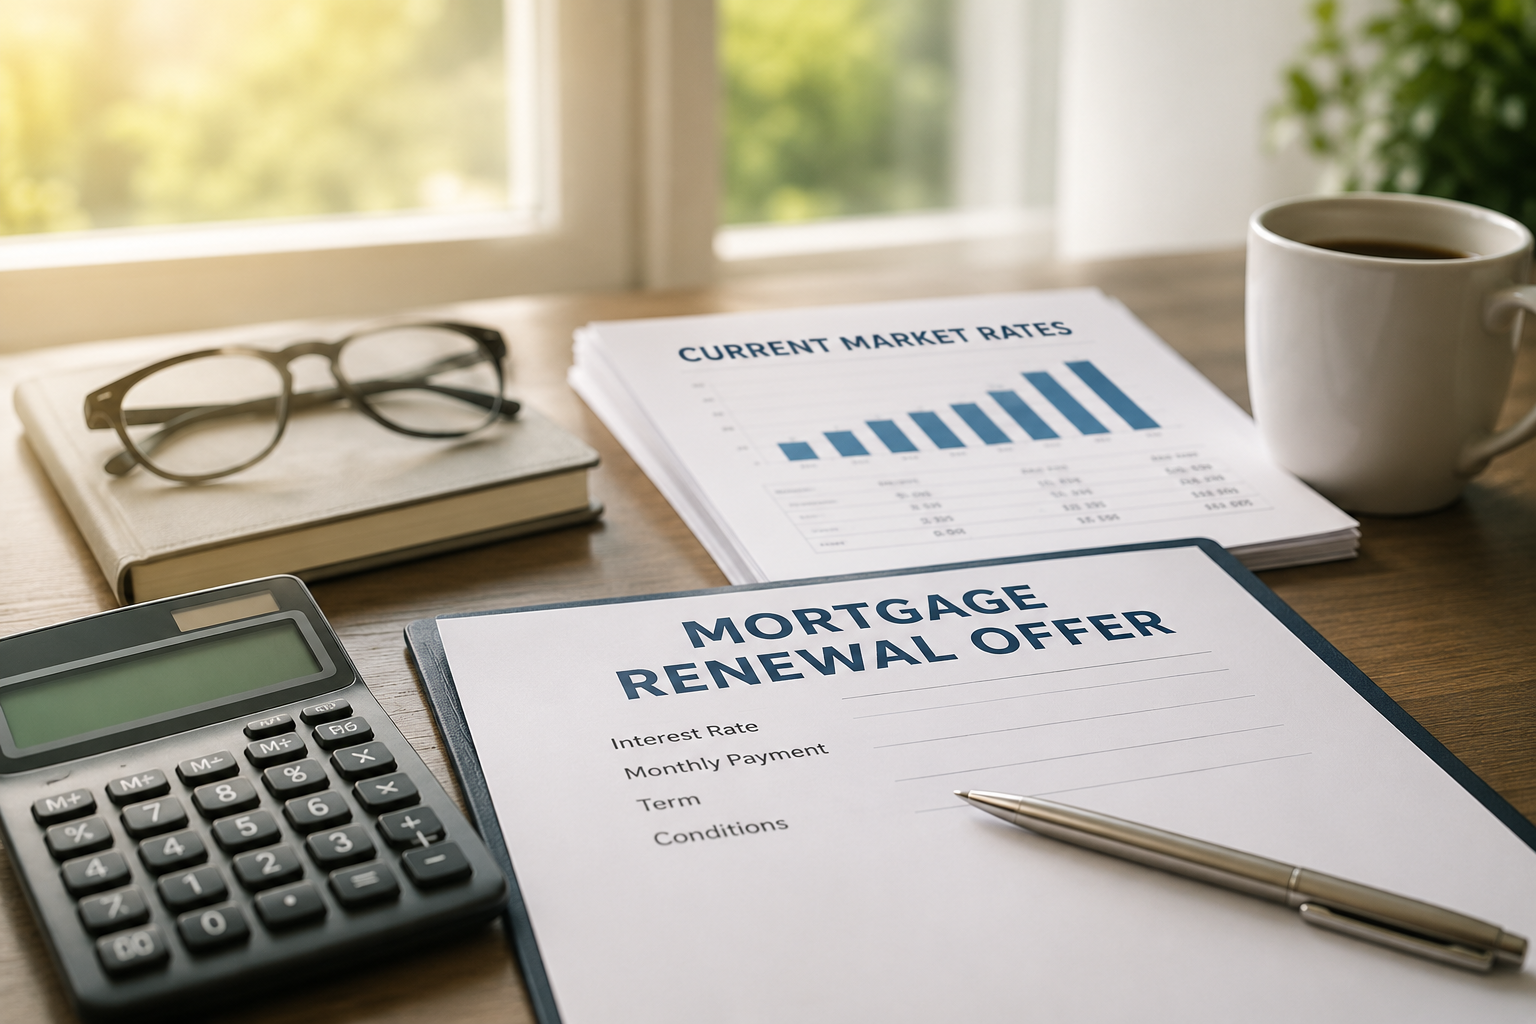
Getting a mortgage renewal letter seems pretty straightforward. Your lender gives you a new rate and payment, you sign it, and you’re done.
At least that’s how it looks.
What I started wondering was: how does the average homeowner actually know if the offer they’re getting is any good?
I’m not a mortgage broker or financial adviser. I’m just someone who started digging into this and realized it’s surprisingly difficult to get a simple answer. You can search mortgage rates online in about 30 seconds. The problem is that the rate you find isn’t necessarily comparable to the renewal offer sitting in front of you.
There can be different conditions, different mortgage types, different equity requirements and all sorts of other details attached to an advertised rate. So if your bank offers you 4.89% and you find 4.24% online, that doesn’t automatically mean your bank is ripping you off.
But I’d certainly want to know why there’s a difference.
The rate is a starting point
Obviously the interest rate matters.
A difference that looks fairly small on paper can make a noticeable difference to your payment, especially with a large mortgage balance.
But there are other things worth looking at too.
What are the prepayment privileges? What happens if you need to break the mortgage early? Is it portable? Are there fees or restrictions? And if another lender has a lower rate, what would it actually cost and involve to move the mortgage?
Those details aren’t nearly as exciting as finding a lower rate, but they can matter.
There’s nothing wrong with staying with your bank
I think this part sometimes gets lost.
Switching lenders isn’t automatically the smart move. Continue Reading…
Buying your first home is one of the biggest financial decisions you’ll ever make. For first-time home buyers, the process can feel overwhelming, but with the right preparation, it can also be one of the most rewarding investments you’ll ever make. Think about the benefits of choosing the right property and the satisfaction you will feel of having a place of your own while building wealth.
The right home doesn’t just provide shelter: it supports your lifestyle, builds long-term wealth, and gives you a place to create lasting memories. Here are seven essential tips to help you navigate today’s real estate market with confidence.
Many first-time buyers focus only on the purchase price or monthly mortgage payment. Unfortunately, that’s only part of the picture.
Your monthly housing costs typically include:
Mortgage principal
Interest
Property taxes
Homeowners insurance
Utilities
Maintenance and repairs
HOA or condominium fees (if applicable)
A useful rule of thumb is to budget 1–3% of your home’s value each year for maintenance, although actual costs vary depending on the property’s age and condition.
Remember the acronym PITI:
Principal
Interest
Taxes
Insurance
Calculating each component individually will give you a much more accurate budget than relying on a simple percentage estimate.
2.) Research the Neighborhood as carefully as the House
A beautiful house in the wrong neighborhood can quickly become a disappointment.
Before making an offer, consider:
Commute times during rush hour
Crime rates
School quality (even if you don’t have children)
Access to parks, shopping, and healthcare
Noise levels
Future development plans
Visit the neighborhood during weekdays, evenings, and weekends. You’ll often notice differences that aren’t obvious during a scheduled showing.
I once bought what seemed like the perfect condo. It was within my budget, and the property itself was beautiful. The problem wasn’t the condo: it was the neighborhood. Although it was clean, safe, and well maintained, it was incredibly boring. It felt like the kind of place people moved to simply to wait out retirement. By 5:00 p.m., everything was closed, the streets were empty, and there was little sense of life or energy. Needless to say, I sold the condo in less than a year.
3.) Interview multiple Real Estate Agents
Not all real estate agents offer the same level of service.
A great buyer’s agent acts as:
Your advisor
Your negotiator
Your advocate
Your local market expert
Interview at least two or three agents before choosing one. Ask about:
Experience with first-time buyers
Knowledge of your preferred neighborhoods
Negotiation strategy
Recent sales history
The right agent can save you thousands of dollars while helping you avoid costly mistakes.
Don’t hire the first agent you see. Meet them at an open house. Instead, do your homework and think about who’s going to generate the best outcome for you. It’s a good idea to interview two or three agents before picking one. Good agents will always submit to this process because they’ll have confidence in their ability to serve you.
The first real estate agent I hired was a good friend from college. Everything went smoothly. I was one of his first clients, and I was happy with his service. At the same time, because we were friends, I would have felt uncomfortable hiring someone else.
A few years later, when I purchased another property, I hired a different friend as my agent. Unfortunately, that experience was very different. She failed to disclose some important defects in the property, and when I realized she wasn’t being completely honest with me, I walked away from the deal. Sadly, our friendship didn’t survive the experience.
The lesson I learned is simple: even if your real estate agent is a friend, you should still do your own due diligence. Ask questions, verify the information you receive, and never assume that friendship is a substitute for careful judgment.
4.) Never skip the Home Inspection
A professional home inspection is one of the smartest investments you can make.
An inspector examines major systems such as:
Roofing
Foundation
Plumbing
Electrical
Heating and cooling
Structural issues
The inspection may uncover problems that allow you to renegotiate the purchase price: or walk away from a costly mistake.
Remember that a home inspection is different from an appraisal.
A home inspection evaluates the property’s condition, while an appraisal estimates its market value for the lender. Continue Reading…
The modern worker faces rapid inflation in housing and consumer prices. This results in reduced savings and financial insecurity. As a result, the Financial Independence/Retire Early (FIRE) movement has garnered many loyal followers. Individuals are saving aggressively and investing wisely to retire early and have enough money to cover living expenses.
Understanding Financial Independence
Financial Independence is achieved when an individual can cover daily expenses without having to work. One of the biggest ones is renting or owning a home. In 2023, more than 21 million renters spent over 30% of their income on housing.
Since housing consumes a large share of income, people are looking to move to areas with lower rents. This salary-to-housing ratio is even more skewed in high-cost urban areas, where rent prices are sky-high, such as in New York, Los Angeles and Chicago. There are plenty of other cities that provide the same energy while having a more affordable cost of living.
Moving to a Lower Cost-of-Living Area
There are plenty of things to consider before moving to cities with a lower cost of living:
Benefits
Geographic locations also directly impact living costs such as rent, food, utilities, transportation and healthcare. With lower expenses, individuals can afford more luxuries like dining out compared to when residing in high-cost cities. Individuals can lead more relaxed lives due to less financial stress. Other factors to improve one’s quality of life include access to nature, community amenities and smaller populations.
Reduced expenses due to a lower cost of living can accelerate savings over time, especially when directed to diverse investment accounts, retirement accounts and income-generating assets, helping individuals gain Financial Independence earlier.
Moving Tasks
Before deciding on new locations, people can create structured plans regarding moving expenses, new living costs and potential earnings. Employment rates, average salaries and cultural opportunities need to be researched and compared with their current lifestyles.
Housing and job searches should also be handled before the move. After moving, local communities, online forums and professional networks can help ease the transition into the new city. Financial goals should also be reassessed to reflect changes in income and expenses to maintain progress toward FIRE.
Sacrifices and Trade-offs
Since 2017, home purchases rose by 81%, while rent prices rose by 54% compared to a 43% increase in earnings. To further increase savings, people can downsize their living spaces or sacrifice proximity to major urban areas.
They might experience an initial discomfort with the change in lifestyle, but that will be outweighed by the potential long-term financial benefits. By assessing what to give up, professionals can gain more control over their finances and way of life. They can be more prepared for emergencies or other future situations.
5 Affordable U.S. Cities to Accelerate the Financial Independence Journey
1. Grand Rapids, Michigan
Grand Rapids, Michigan, can help individuals significantly reduce expenses due to the city’s growing economy and consistent job opportunities. They also don’t have to sacrifice lifestyle quality, as the Grand Rapids area is known for its wide range of outdoor activities, emerging art scene and friendly communities.
2. Austin, Texas
Austin, Texas, is a burgeoning tech hub with more affordable rents than in Silicon Valley and Seattle. Tech presence in Austin includes Apple, Tesla, Dell, AMD, Amazon, Google, IBM, Meta, Microsoft and Samsung, among others. Besides its tech scene, Austin has a vibrant music community and plenty of outdoor activities at Lady Bird Lake, Mount Bonnell and Barton Creek Greenbelt. The city also offers a distinct food scene, especially Texas barbecue and tacos.
3. Boise, Idaho
Boise is an ideal city to relocate to for individuals looking to save on living costs. The city offers stunning landscapes without breaking the bank on rent, making it perfect for families and young professionals alike. Residents have plenty of activities to explore in the city, including hiking, biking and skiing. It has a solid job market, a stable economy and plenty of amenities for different lifestyles. Boise also has top-rated schools with relatively lower utility and transportation costs.
4. Charlotte, North Carolina
Charlotte is growing as a major financial, healthcare and tech center, making it a great option for many young professionals. The city also has plenty of welcoming communities with diverse interests and backgrounds. The cost of living here is lower than in other ultra-urban cities, which makes day-to-day living and saving significantly more hassle-free. Residents can drive to the Blue Ridge Parkway for a relaxing weekend trip in the Great Smoky Mountains.
5. Richmond, Virginia
Richmond, Virginia, is great for those who are inspired by a place’s historical significance. It also offers significant modern growth, cost-of-living affordability and culture. The city has plenty of galleries, theaters and music venues for any art-loving individual. Community events and volunteer opportunities are plentiful.
Embracing a Strategic Move for Financial Freedom
The Financial Independence Retire Early movement is widely known. It encourages individuals to save more, invest in income-generating assets and retirement accounts to be able to retire earlier than the rest of the workforce.
Relocating to lower-cost cities is one of the most viable paths toward increased savings. There are plenty of cities with a vibrant energy, welcoming communities and plenty of activities. In the right locations, individuals can increase savings without sacrificing quality of life, but proper planning before moving is essential to achieving a fulfilling lifestyle.
Dan Parks is a senior writer at Modded.com. Based in Washington, D.C., Dan has a proven track record of distilling complex subjects into accessible narratives across various fields. His expertise in clear communication and meticulous research makes him a valuable contributor to discussions on personal finance and investment strategy, helping readers navigate intricate topics with ease. Dan is dedicated to providing readers with well-researched insights to foster financial literacy and independence.
An organization called Generation Squeeze is calling for big cuts to Old Age Security (OAS). For some reason, these cuts are aimed exclusively at senior couples. Digging into the numbers, the proposal makes no sense.
The stated goal of the proposed OAS changes is to free up government money for other priorities. Whether or not OAS is the right target for reducing government spending is a different discussion. The puzzling part of this proposal is having all the cuts apply to senior couples.
Currently, OAS will get clawed back from any senior whose 2025 net income (Line 23400 of the tax return) is over $93,454. For each dollar over this income threshold, OAS payments are reduced by 15 cents. The current rules make no distinction between singles and couples. The calculation is based on each person’s own income without regard to whether they have a spouse.
It’s more expensive for two people to live than just one
Generation Squeeze wants to change the threshold to $100,000 for total household income. So, single seniors would lose nothing, and senior couples would eat all of the cuts. The problem here is that it is more expensive for two people to live than just one. The figure actuaries use is that it costs about 40% more for two people in the same home to live than it costs for one person. Continue Reading…
 Posted By
 As the cost of living continues to squeeze Canadian households, a new survey from Vanguard Canada suggests the strain isn’t confined to parents’ bank accounts; it’s also shaping how their children think and feel about money too.