General

Your first resolution: add $6,000 to your TFSA

Welcome to 2019! Now that it’s January you can contribute $6,000 to your Tax-free Savings Account (TFSA), a program that’s now been around a full decade. That means couples can between them contribute $12,000.

The previous annual maximum was $5,500, but because of Ottawa’s promised inflation “bump” it has now officially been adjusted to $6,000. Recall that it was originally $5,000 when the program was introduced back in January 2009. Hard to believe it’s been ten full years now!

As the chart below illustrates, the cumulative limit (shown on the far right column) is now $63,500, which means a couple can between them invest $127,000. The first inflation adjustment was in 2014, when the limit reached $5,500. Under the Harper Tories it actually was almost doubled to $10,000 for calendar 2015 but one of the first things the Trudeau Liberal administration did was to reverse it back to $5,500 in 2016. It’s been $5,500 for three years until the new $6,000 limit that’s now in place.

2009$5,000$5,000
2010$5,000$10,000
2011$5,000$15,000
2012$5,000$20,000
2013$5,500$25,500
2014$5,500$31,000
2015$10,000$41,000
2016$5,500$46,500
2017$5,500$52,000
2018$5,500$57,500
2019$6,000$63,500

In the early years of the program, it might have been tempting to dismiss the original $5,000 as being an “insignificant” amount but obviously $63,500 is a hefty amount and anyone who has been contributing the maximum from the get-go should with tax-free growth have considerably more than that by now: I often hear from readers who have more than $100,000 in them, although December’s brutal stock market action is likely to have set them back a bit.

Maximize the time value of money

Why contribute the new $6,000 right now? I view this as a “time value of money” exercise and you may as well maximize the compounding effect of tax-free growth, assuming you are focusing on equities. Except for profoundly conservative investors, I’d recommend that Millennials and Generation X members use the TFSA primarily for Growth (equities or stocks, or equity ETFs). Baby boomers at or near Retirement could use Balanced Funds or ETFs (like VBAL from Vanguard, which is 60% stocks to 40% bonds, spread around thousands of securities around the world.) That’s likely the one we’ll use ourselves this week: we put the money into our discount brokerages on January 1st, but will actually invest it before the week is out, once markets are open.

Keep in mind that you can keep adding to your TFSA well into old age: I know a lady who is more than 100 years old who continues to do just that! That’s a lot of potential growth, which is why a balanced product may make sense. Of course, those who value interest income and wish to eschew stock-market risk can also use bond ETFs or GICs in their TFSAs: these days even 2-year GICs can be found that pay 3% or more.

Happy new year!

Here’s what home buyers can expect in 2019

By Penelope Graham, Zoocasa

Special to the Financial Independence Hub

2018 has certainly been a tumultuous year for Canadian real estate: tougher mortgage rules, rising interest rates, and sky-high rent prices have squeezed buyers and tenants in markets across the country. Will next year be one of stabilization sales and prices, or will 2019 usher in more uncertainty for those aspiring to be homeowners?

Let’s take a look at four scenarios that are likely to materialize in the new year.

1.) Count on slower sales

New build and resale activity for condos and houses for salehave slowed across Canada this year, and have impacted various markets for a variety of reasons; in Ontario, buyers continue to grapple with the effects of the Fair Housing Plan, a package of policies introduced last March, while Vancouver is dealing with price fatigue and new taxes that target investor and foreign buyers. Smaller western markets, such as Calgary, are slogging through a supply imbalance, which puts downward pressure on prices.

However, all housing markets have been reeling from the effects of the federal mortgage stress test, which was put into effect on January 1 (a year ago). Combined with rising interest rates, it has taken the steam out of real estate activity and reduced buyers’ purchasing power as they must prove they can qualify for a mortgage roughly 2% higher than the rate they’ll actually get from their bank.

According to recent analysis from the Canadian Real Estate Association, it won’t be a cheerier picture in 2019: sales are actually expected to hit a nine-year low, softening 0.5% from 2018, which has already absorbed an 11.2% decline at 548,200 homes sold.

“In 2019, home sales activity and prices are expected to be held in check by recent policy changes from different levels of government, in addition to additional interest rate increases,” CREA states in its November release.

2.) A temporary hold on rate hikes

Good news for borrowers, but not so much for the economy – despite strong expectation that there would be multiple Bank of Canada (BoC) rate hikes this year and next, recent economic events have effectively derailed the central bank’s upward tear, meaning variable-rate mortgage holders and new applicants will get a temporary reprieve on their cost of borrowing.

The BoC, which controls inflation and the cost of lender borrowing by increasing or decreasing its trend-setting Overnight Lending Rate, opted to leave it untouched in its December announcement, despite hiking in October to 1.75%, as a new U.S. – China trade skirmish and domestic oil price plunge have raised doubts on economic stability. 

It has been said throughout the year, in response to early strong inflation growth, that the BoC intended to eventually raise rates to a “neutral” range, between 2.5 – 3.5% by 2019. It is unclear at this time if it still plans to do so over the coming year.

3.) Rents to keep on rising

Sorry, tenants – there isn’t any sign of relief in store for you. 

The price of rent, especially in Canada’s largest urban centres, has been a central theme in 2018; rental MLS listings in Torontofor one-bedroom units rose 9.5% this year to an average of $2,163, according to the Toronto Real Estate Board. A CMHC rental report also reveals that, across the nation, rents have increased 3.5%, with the largest hikes in Vancouver (+55%), and Toronto (+5.2%). Rental vacancies also shrunk in most major markets; Toronto and Vancouver both have roughly 1% of rental stock available, while the Quebec market saw its rate plunge from 3.4% to 2.3% in the span of a year.

And they’re expected to keep on rising by an average of 6% next year, according to the National Rent Report released by Bullpen Research and Consulting, partnered with Rentals.ca, as employment, migration, and desirability factors continue to fuel demand for units.

4.) How can buyers prepare for 2019?

For those sitting on the fence regarding their home purchase, the time to act is now; connect with a mortgage professional to lock in a pre-approved rate before the BoC resumes its hiking mandate. Be prepared to encounter fewer listings in the new year, as many sellers may not feel the climate is the right one to list their home. However, with the pace of price growth expected to soften in many markets, it could be an advantageous time to get onto the property ladder at a lower price point than before. It’s a great idea to work closely with an agent when the market is slightly down, to determine if it’s the best time for you to make a move.

Penelope Graham is the Managing Editor of Zoocasa.com, a leading real estate resource that uses full brokerage service and online tools to empower Canadians to buy or sell their home faster, easier, and more successfully.

The Benefits of Travel

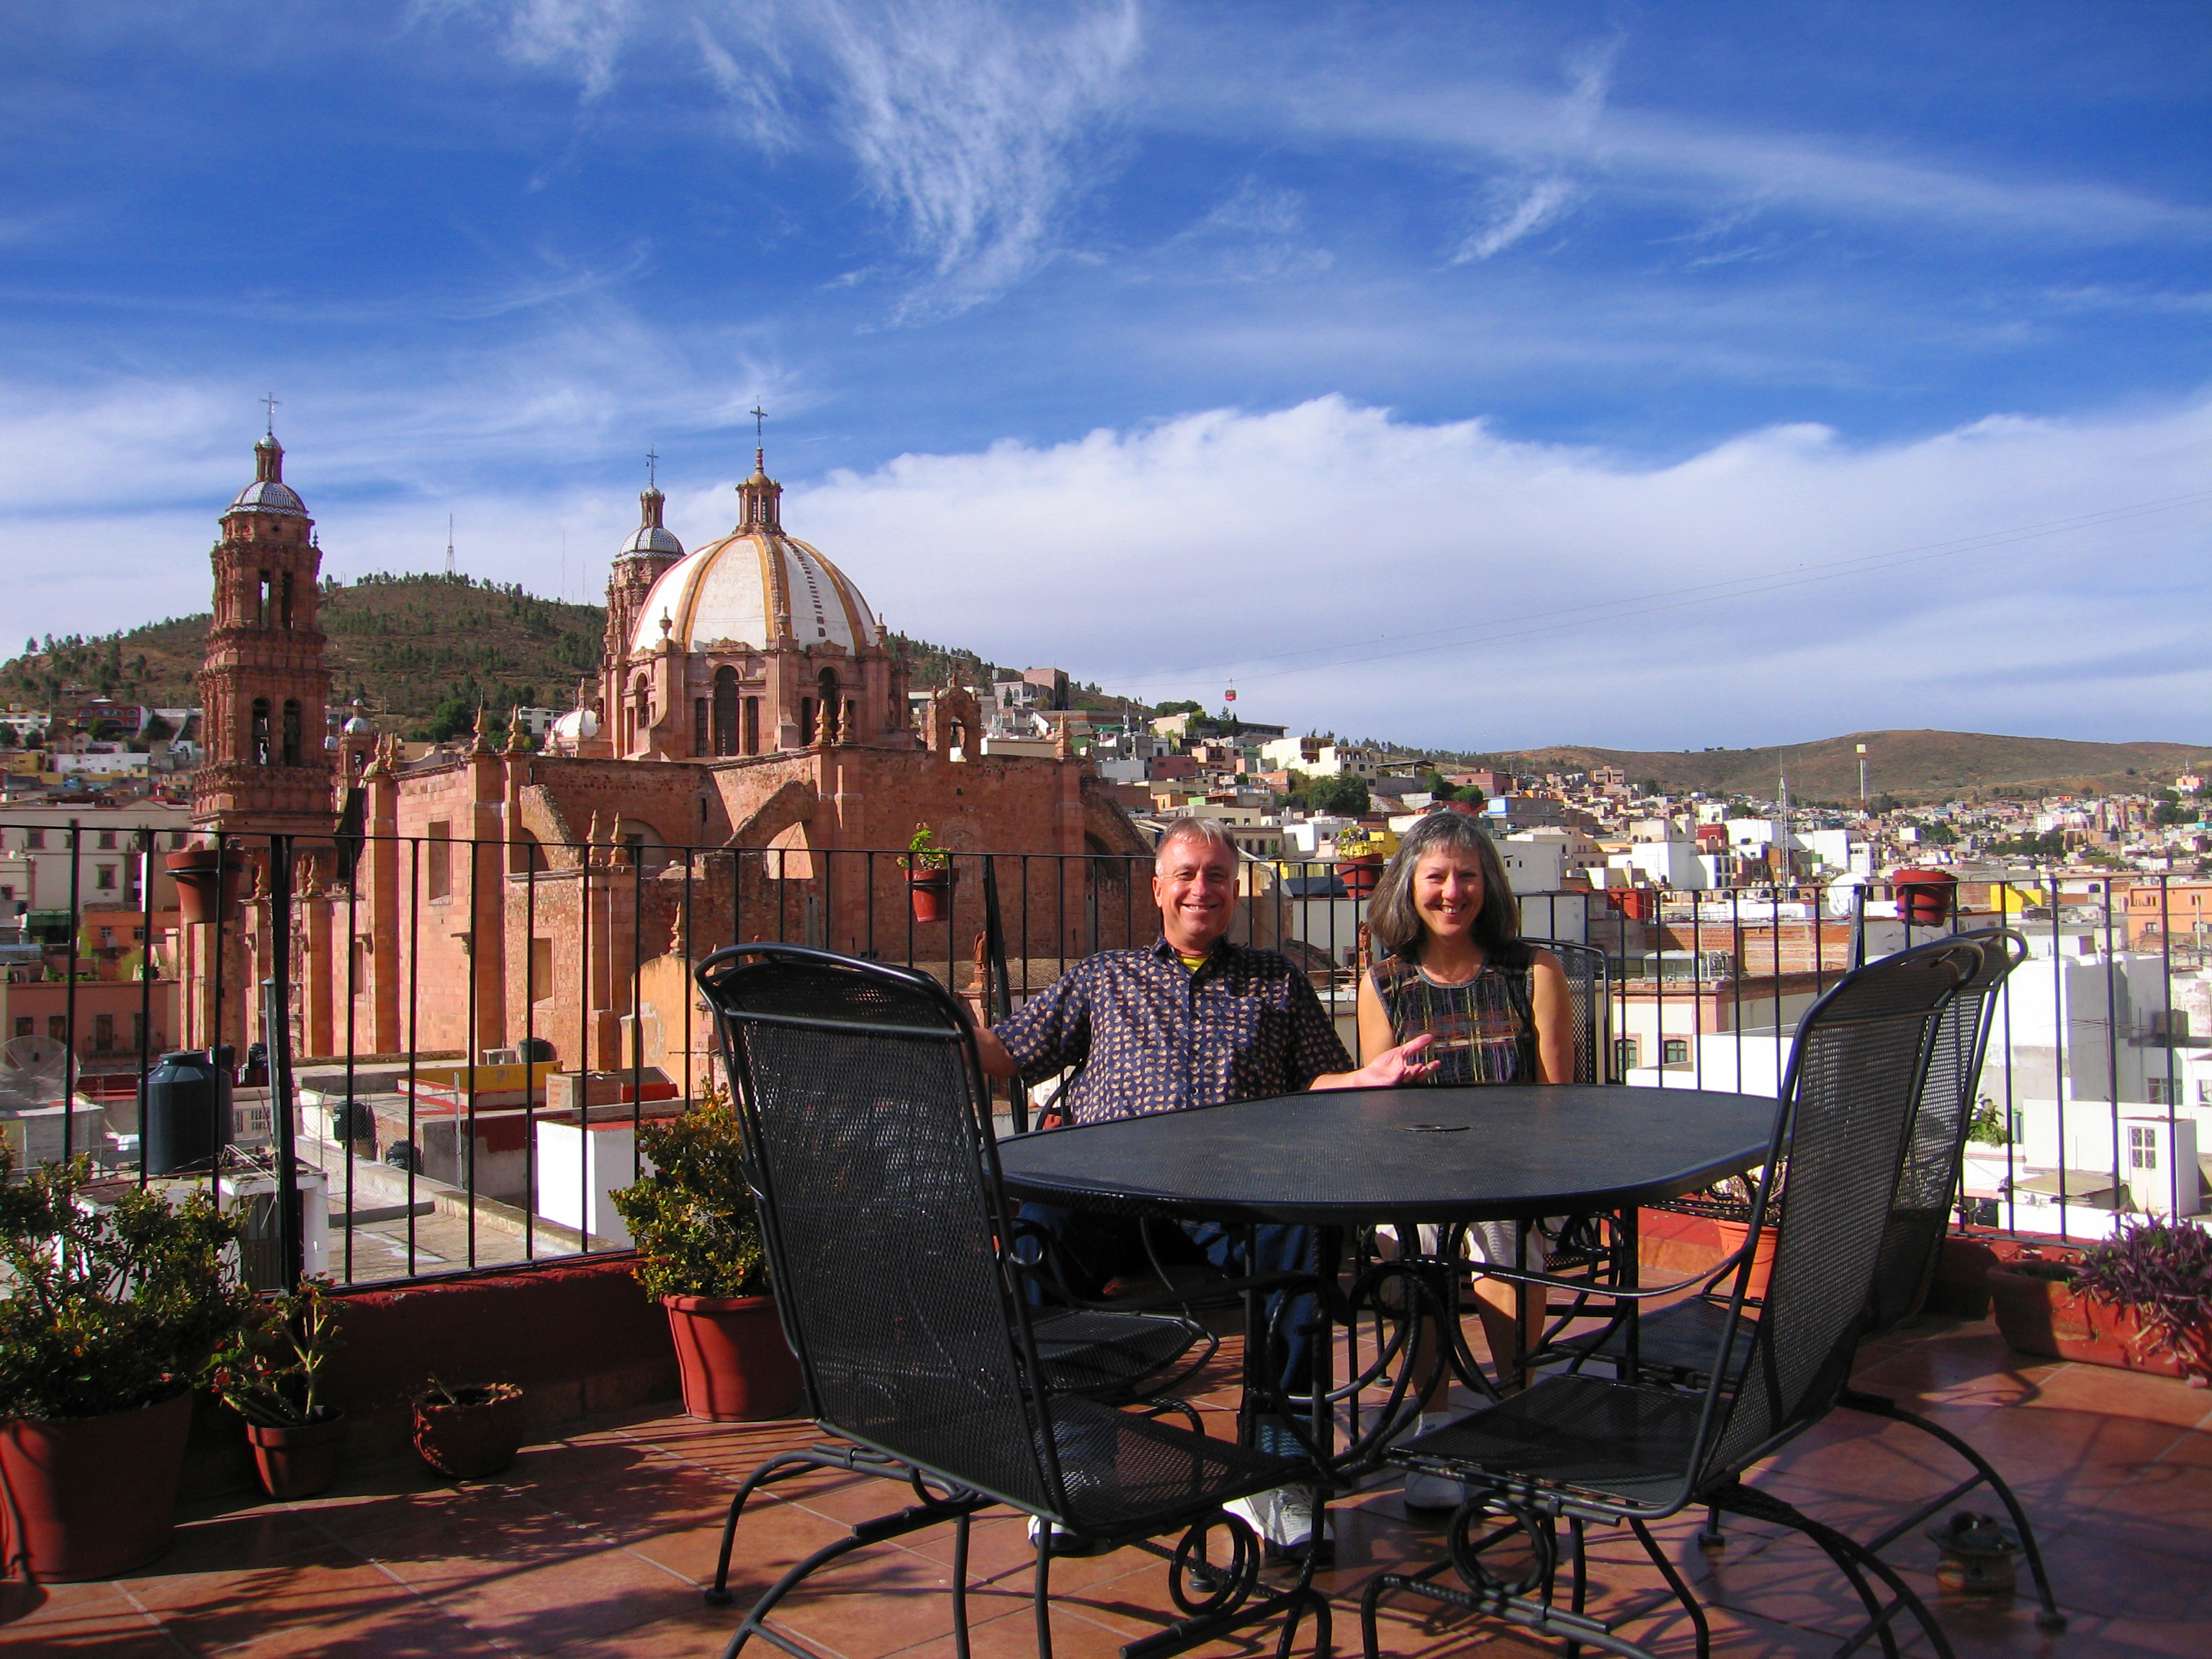
Billy and Akaisha take in the view from their hostel in Zacatecas, Mexico

By Akaisha Kaderli

Special to the Financial Independence Hub

We understand that not everyone likes to travel. No doubt it can be challenging, but there are significant benefits if you choose to enliven your routine with a little excursion.

Traveling makes you smarter

From the beginning of choosing a location, packing your suitcases and figuring out the logistics of who will water your plants or sit with your pet, traveling takes you out of your routine. Anything new and different like this that engages your brain causes new neurological pathways to grow.

Learning a new language, taking a cooking or painting class while on your trip and meeting new people all place you in unique situations, and your brain strengthens.

Traveling is healthy for you!

Traveling makes you strong

For some people, all these new patterns outside the everyday routine can be perceived as a hassle. Yes, and that’s good! We learn flexibility, creativity and self-reliance. Those are great attributes to have and they are useful to daily living.

Flexibility of mind, finding new solutions to new challenges and our sense of who we are and how we cope all get stronger.

Traveling helps you become an interesting story teller

When things don’t go according to plan, those seemingly challenging circumstances make for the best stories!

If everything goes perfectly on your trip or vacation, and people ask “How did you enjoy yourselves? How was your trip?” then all you can say is “Great!” Continue Reading…

U.S. Growth stocks: You’d better be Seabiscuit

This is Part 2 of a two-part blog series on the prospects for Growth and Value Stocks.

Read Part 1 Growth Stocks: Where’s the Beef?

By Jeff Weniger, CFA, WisdomTree Investments

Special to the Financial Independence Hub

When your starting point is a 1.4% dividend yield,1as is the case with the S&P 500 Growth Index, the group of stocks that make up the basket need to have long-term dividend growth that performs like Seabiscuit, the super horse. No tripping out of the gate or getting bumped in the stretch.

Latching on to the concepts in my white paper, Dividend Growth’s Drivers: Picking Apart Quality, we present figure 1, which shows the interrelationship between the percentage of earnings that are retained (as opposed to paid out as dividends) and the return on equity (ROE), which is net income as a percentage of shareholders’ equity.

This relationship is thedriver of dividend growth, and as the years go on, concepts like figure 1 have become core tenets of second-decade WisdomTree.

Figure 1: The Critical Equation

The Critical Equation

Figure 2 uses the critical equation to calculate long-term dividend growth at prevailing profitability levels.

As it stands, the S&P 500 Growth Index’s 23.2% ROE implies long-term dividend growth of 16.8%. That could happen, yes. Anything canhappen. But here’s a better idea: expect downward revisions instead.

Figure 2: Implied Dividend Growth Estimate 

Implied Dividend Growth Estimate

After all, look at the historic record in figure 3. There isn’t a single five-year period that had growth stocks’ earnings running forward at a 16.8% clip, not even in the roaring 1990s. In contrast, value stocks’ implied dividend growth is on planet Earth. 

Figure 3: Dividend Growth Rate, 5-Year Periods, 1995–Present 

Dividend Growth Rate 5Year Periods 1995Present

Does anything jump out in figure 3? Look at the dividend growth experience of growth and value from 2010 to 2015 and from 2015 to the present.

Those growth stocks start to look less like Seabiscuit and more like also-rans if recent years are any indication. Granted, value indexes are dominated by banks, and the period from 2010 to 2018 was characterized by the benefit of their reinstated dividends. Nevertheless, if growth stocks were only able to increase their dividends at a high single-digit rate during this period of irrepressible economic expansion, what happens if recession hits? Let someone else pay 22 times earnings to find out. 

Slow and Boring? Better than Growing Out of 1%

The S&P 500 Value Index has a dividend yield that is about double that of the S&P 500 Growth Index (2.7% vs. 1.4%). This kind of gap makes it nearly impossible for the latter index to ever grow out of its valuation.

If U.S. growth could not differentiate its … ahem … dividend growth relative to value from 2010 to 2018, what makes anyone think the next several years will be different? For growth stock skeptics, the WisdomTree Fund that hits value is the WisdomTree U.S. High Dividend Index ETF (HID/HID.B). 

It retains 38% of its earnings, pays out the other 62% as dividends and has an ROE of 13.5%. That ROE is satisfactory enough. Using the “critical equation,” it has long-term implied dividend growth of 5.1%, which is less than the levels of the S&P 500 Growth Index. But when the starting point is a 1.4% forward dividend yield, companies that populate indexes like the S&P 500 Growth Index would have to run up their dividends at a 15% or 20% annual pace for a long time before the math even thinks about shifting in their favour.2

For investors who do not want to commit to value because they keep getting burned, a fund like the WisdomTree U.S. Quality Dividend Growth Index ETF (DGR/DGR.B), which tracks the WisdomTree U.S. Quality Dividend Growth Index CAD, seeks to target companies that rank well on our ROE x earnings retention framework. 

Critically, its dividend weighting methodology also checks valuations at the door. That gives it a starting dividend yield of 2.7%, about 130 bps more than the S&P 500 Growth Index. It also has an explicit screen for ROE and return on assets (ROA). Its 15.8x forward earnings multiple is 3.3 multiple points below the S&P 500 Growth Index.

Over the next 5 or 10 years, we’ll take DGR.B or HID.B over S&P 500 Growth Index. This is where the rubber meets the road, when the cap-weighted U.S. large-cap growth indexes start to be priced like they’re Seabiscuit, when in reality they’re an underlay.

1Sources: WisdomTree, Bloomberg, as of 11/15/18.

2Sources: WisdomTree, Bloomberg. Unless otherwise stated, all data in this blog as of 11/15/18.    


Jeff Weniger, CFA serves as Asset Allocation Strategist at WisdomTree. Jeff has a background in fundamental, economic and behavioral analysis for strategic and tactical asset allocation. Prior to joining WisdomTree, he was Director, Senior Strategist with BMO from 2006 to 2017, serving on the Asset Allocation Committee and co-managing the firm’s ETF model portfolios. Jeff has a B.S. in Finance from the University of Florida and an MBA from Notre Dame. He is a CFA charter holder and an active member of the CFA Society of Chicago and the CFA Institute since 2006. He has appeared in various financial publications such as Barron’s and the Wall Street Journal and makes regular appearances on Canada’s Business News Network (BNN) and Wharton Business Radio.

U.S. Growth stocks: where’s the beef?

This is Part 1 of a two-part blog post series on the market’s current expectations for U.S. growth and value stocks.

Figure 1: S&P 500 Growth Total Return Index Relative to S&P 500 Value Index

S&P 500 Growth Total Return Index Relative to S&P 500 Value Index

By Jeff Weniger, CFA WisdomTree Investments

Special to the Financial Independence Hub

At the risk of making a 34-year-old pop culture reference, growth stock fundamentals beg the question first posed by Wendy’s: “Where’s the beef?”

As was the case in 1984, when war was declared on McDonald’s and Burger King, there appears to be a lot of “bun” in U.S. growth stocks but not a lot of “meat.”

Face it:  the magnitude and duration of the multi-year clobbering of value strategies by growth stocks in the current cycle is second only to the legendary 1994–2000 “New Economy” years. That epic mania for growth as an investing style began about a year before the 1995 Netscape IPO,1 at which point the tech boom began to rage. That furious less-than-six-year rally in the second half of the 1990s took the S&P 500 Growth Index 400.7% higher (31.2% annualized), trouncing the S&P 500 Value Index’s gain of only 198% (20.2% per year).2 When the rug was ripped out in the 2000–2002 crash, value stocks picked up thousands of basis points of outperformance.

Today, the cumulative gap between the two indexes, which has been stretching out since 2006, is once again in triple digits. From July 31, 2006 to October 31, 2018 — more than 12 years — the S&P 500 Growth Index returned 296% (or 11.9% annually), about doubling the 152% appreciation of the S&P 500 Value Index (7.8% annually).

That’s 144 percentage points.

Before we begin searching for The Beef, consider the striking picture painted by figure 1 (at the top of this blog). As a reminder, the NASDAQ, about as “growthy” an index as can be constructed, started its crash in March 2000. The S&P 500 Index topped out later that summer. When they did, the rotation to value stocks was a flood.

Piggybacking on WisdomTree’s Prior Dividend Growth Work

We received positive feedback on our white paper, Dividend Growth’s Drivers: Picking Apart Quality, and this analysis builds on many of those concepts for the growth/value debate. In that piece, we looked at our Quality Dividend Growth suite, diving into the interaction of return on equity (ROE) with earnings retention and dividend payout ratios to determine the long-term drivers of shareholder wealth. The interrelationship between profitability and dividend policy is critical, and the more research we do on it, the more these concepts are becoming core parts of second-decade WisdomTree.

Figure 2 shows profitability and growth metrics for the S&P 500 Growth, S&P 500 and S&P 500 Value Indexes.

Figure 2: S&P 500 Growth, Core and Value Metrics

S&P 500 Growth Core and Value Metrics

The Critical Equation

Dividend Growth’s Drivers: Picking Apart Quality identified profitability (ROE) as the driver of dividend growth, presenting the critical equation recreated in figure 3.

Figure 3: The Critical Equation

The Critical Equation

Figure 4 uses the critical equation to calculate “long-term” dividend growth for the three indexes. We added quotation marks to “long-term” because, frankly, looking into the future involves a lot more art than science.

Figure 4: Implied Dividend Growth Estimate

Implied Dividend Growth Estimate

Can the S&P 500 Growth Index achieve long-term dividend growth of 16.8%? And how long is long-term? No one knows, including us.  But we can engage the numbers to get a feel for whether we want to pay nearly 22x forward earnings for growth stocks when value stocks are on offer for 15x earnings.

In Part 2 of the blog post, we consider the possibility of multi-year 17% growth in dividends, and whether it even makes sense. Spoiler alert: it doesn’t.

Stay tuned for our suggestions for growth investing: namely ideas like the WisdomTree U.S. Quality Dividend Growth Index ETF (DGR.B), which tracks the WisdomTree U.S. Quality Dividend Growth Index CAD, and the WisdomTree U.S. Quality Dividend Growth Variably Hedged Index ETF™ (DQD), which tracks the WisdomTree U.S. Quality Dividend Growth Index Variably CAD-Hedged. For investors that want more of a switch in the direction of value stocks, one of our better yielders in broad U.S. equities is the WisdomTree U.S. High Dividend Index CAD, tracked by the WisdomTree U.S. High Dividend Index ETF (HID.B). The quality dividend growth indexes yield 2.7%, while the high dividend index has a yield north of 4%, putting them handily above the dividend yield on offer for the S&P 500 Growth Index.3 

1The famed 1995 Netscape IPO is widely regarded as one of the first newsworthy events of the dot.com boom.
2Sources: Bloomberg, WisdomTree, 04/29/1994–03/31/2000. Unless otherwise stated, all returns in this blog in CAD.
3Sources: WisdomTree, Bloomberg, as of 11/15/18.

Jeff Weniger, CFA serves as Asset Allocation Strategist at WisdomTree. Jeff has a background in fundamental, economic and behavioral analysis for strategic and tactical asset allocation. Prior to joining WisdomTree, he was Director, Senior Strategist with BMO from 2006 to 2017, serving on the Asset Allocation Committee and co-managing the firm’s ETF model portfolios. Jeff has a B.S. in Finance from the University of Florida and an MBA from Notre Dame. He is a CFA charter holder and an active member of the CFA Society of Chicago and the CFA Institute since 2006. He has appeared in various financial publications such as Barron’s and the Wall Street Journal and makes regular appearances on Canada’s Business News Network (BNN) and Wharton Business Radio.