General

How to be wealthy & healthy, starting this Holiday Season

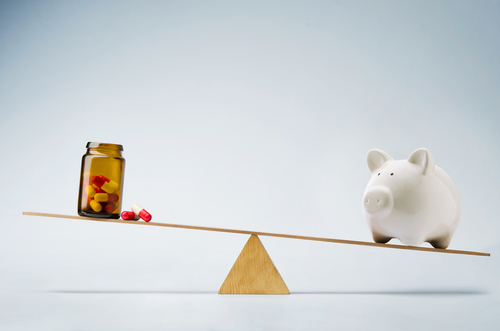
Piggy bank balancing on seesaw over a bottle of pills
You can balance Health & Wealth with advisors on both

By Sandy Cardy

Special the Financial Independence Hub

The Holiday season is a very personal balancing act.  Every year we experience the same thing – multiple events featuring gut-bloating menus and Boxing Day blow outs followed by crash dieting for both your waist-line and your bottom line. How do you find that sweet spot between making the season joyful and memorable while avoiding the perils of two to three weeks of over-eating and spending followed by a blizzard of credit card debt?

It’s no secret that Canadians, particularly Baby Boomers in their sixties, are doing a poor job of managing their retirement savings, falling well short of amassing enough retirement funds. Canadians still find it difficult to apply one of the simplest financial planning principles: pay yourself before you pay for anything else.

If, like many boomers, your retirement plan is increasingly looking like harnessing yourself to a full-time job as long as possible, what happens if you fall sick? And when you gaze with furrowed brow at your bloated credit card balances in January, not only are you even further from any savings goals, the sheer shock of the amount owing can add an unwelcome dollop of stress to already overtaxed minds and bodies.  Never knowing when enough is enough, there aren’t any checks and balances on our impulse to over-consume.

Here are some tips to get re-balanced for 2017:

Every money decision you make, even the little ones, will have an impact on your retirement. Perhaps what you need now is a qualified advisor to help you achieve your goals: someone you trust wholeheartedly. A good advisor will ensure you are realizing all cost savings, and applying tax minimization strategies to build your net worth. Put it this way: it’s much more difficult to neglect simple investment principles when a financial planner is looking over your shoulder.

Healthcare advisors as important as financial advisors

Similarly, having one or more health care advisors available is essential. Whether you encounter a health crisis or want to pursue preventative health,  it’s key to find  nurturing and optimistic healers, either conventional or alternative, ones that involve you in your health care discussion.
Continue Reading…

Commission-based advice & suitability: a dangerous combination

Smiling confident businessman giving an handshake, agreement and recruitment conceptThe average Canadian investor has little clue how their financial advisor gets paid, or that their advisor is only obligated to provide advice and product recommendations that are suitable, but not necessarily in the best interests of their clients.

Commission-based advice

Why does this matter? Commission-based advice leads to conflicts of interest. Namely, advisors who sell mutual funds are motivated by trailer fees (aka trailer commissions), which is a commission paid by the mutual fund company to the advisor.

According to a recent study by York professor Douglas Cumming, there are three ways that trailer fees cause harm to investors:

1.) More money is steered towards mutual funds that have higher trailer fees;

2.) Money is less likely to be taken out of mutual funds with poorer performance among funds that pay higher trailer fees, and;

3.) Mutual funds that raised their trailer fees experienced a drop in performance, while funds that lowered their trailer fees experienced a rise in performance.

Canadian securities regulators have been mulling a ban of trailer fees or embedded commissions for over two decades. The mutual fund industry, as you can imagine, is vehemently opposed to such a ban.

Why, you may ask? Canadian investors hold more than $1 trillion in mutual fund investments and pay over $5 billion in trailer fees every single year.

Suitability vs. Best Interest


What about suitability versus a best interest standard? Most advisors in Canada are held to a suitability standard, which means before recommending an investment he or she must demonstrate that it’s appropriate based on their client’s risk tolerance, goals, and experience.

Continue Reading…

What happens to your TFSA upon death?

\

Human mortality seems to be the Hub’s theme today. This morning we posted Lorne Marr’s 20 tips on getting life insurance without having to take a medical exam first.

Subsequent to that, my latest MoneySense Retired Money blog looks at the topic of estate planning as it related to Tax-free Savings Accounts (TFSAs). To access the full blog, click on the highlighted text here: Why your TFSA needs a Successor Holder.

We had mentioned in an earlier blog that TFSAs were excellent vehicles for estate planning and minimizing tax of families as a whole. See How TFSAs can aid your Victory Lap.

We also said that it’s by far preferable for couples to name each other Successor Holders on their respective TFSAs. Otherwise, things get pretty complex, which is what the MoneySense blog goes into in some depth.

TFSA succession planning often not well understood 

Sandy Cardy

The blog is based largely on input from Mackenzie Investments and a brochure it published entitled What happens to your TFSA at the time of death?, which you can access in full by clicking on the link. It also quotes regular Hub contributor Sandy Cardy, who was the head of tax and estate planning at Mackenzie when that brochure was published. In that role, she was responsible for educating the financial advisors who sell mutual funds on estate planning, including its role in TFSAs. As she notes in the MoneySense blog, this topic of TFSAs at death is not well understood even by some financial professionals.

These days, following her own brush with cancer in 2012 (she’s fine now) Cardy blogs as much on health as she does on Wealth. See for example, a recent Hub blog titled The Mind-Body Connection: How Stress Affects Your Health. Her website can be found here, and you can find her estate planning “novel” by clicking on this  highlighted title: The Cottage The Spider Brooch and The Second Wife. 

20 tips for getting Life Insurance without a medical

lm-head-shot-2mg
Lorne Marr

By Lorne Marr, LSM Insurance

Special to the Financial Independence Hub

The No-Medical Life Insurance market in Canada is exploding. More and more people are opting for the convenience of obtaining life insurance without a medical.

No-Medical Life Insurance policies fall into two categories: Guaranteed Issue (no health questions) and Simplified Issue (anywhere from a 2 to 25 + health questions).  No-Med policies are available as Term policies — where the cost starts off low and increases as you get older or Permanent policies — the premiums start off higher but never increase.

There’s a plan for everyone, bu these plans can be an especially good deal for customers that may otherwise be considered hard-to-insure.

Here are 20 points to consider:

1.) Understand the difference between different types of life Insurance.

Simplified issue life insurance: Doesn’t require a medical exam but there are still a number of health-related questions. Typically, the more questions, the lower the premiums. The maximum limit on this type of policy is usually $150,000. You might not qualify for this policy if you have been denied life insurance in the past two years.

Guaranteed issue life insurance: Doesn’t require a medical exam and there are no health-related questions. It is available to everyone, even if you have been declined life insurance within the last 2 years. The coverage limit is typically $25,000 and some payout restrictions may apply during the first two years of coverage. Continue Reading…

Three myths about trading Fixed Income ETFs

michael-barrer-crop
Michael Barrer

By Michael Barrer, WisdomTree Capital Markets

Special to the Financial Independence Hub

Fixed income exchange-traded funds (ETFs) provide the investing world with transparency in an otherwise opaque asset class. Although launched in 2002, fixed income ETFs did not become mainstream until 2008, and today these funds are often considered the growth engine for the ETF industry. However, because of the over-the-counter nature of the fixed income market and the fact that ETFs with fixed income underlying securities were adopted later than their equity-based relatives, there are still myths around the trading and liquidity profiles of these funds. I want to address these myths and explain the realities of the fixed income ETF structure.

Myth 1: Fixed income ETFs are not liquid, and on-screen volume equals ETF liquidity

Reality: ETFs are just an exchange-traded wrapper around a basket of securities. The minimum liquidity available of the ETF is defined by the liquidity of the underlying securities. With equity ETFs, the volume of the underlying securities can be measured and tracked. Implied liquidity is an industry standard metric that quantifies basket liquidity in equity-based ETFs.

In the fixed income market, the over-the-counter trading nature and lack of centralized trade reporting make quantifying fixed income ETF liquidity more challenging. That being said, there is a basic industry practice that assumes 5% of an outstanding issue will turn over daily and a conservative estimate to avoid market impact is to not be more than 25% of that daily turnover.

We recently discussed this subject in a separate blog post, where we quantified the potential daily liquidity in our new “Smart Beta” fixed income strategies. The bottom line remains that fixed income ETFs are designed with liquidity in mind, so they can scale, and the minimum liquidity available will always be based on the liquidity of the underlying asset class. On-screen volume only acts as an additional layer to the overall liquidity profile of the ETF.

Myth 2: Fixed income ETFs have wide spreads

blog-see-more-fixed-incomeReality: The spread of an ETF is a representation of the spread in the underlying asset class, plus the costs and risks associated to the market maker. The exchange-traded and transparent nature of ETFs allows investors to see these spreads in real time. Whereas in a mutual fund, the portfolio spread would mirror that of an ETF with similar characteristics, however, the mutual fund structure does not allow for this level of intraday transparency.

Continue Reading…