Inflation

Inflation

Retirement Spending: Why Spending your Savings is the Hardest Part of Retirement

AlainGuillot.com, via ChatGPT

By Alain Guillot

Special to Financial Independence Hub

I have an unusual retirement problem. I have more money than I’ll probably ever spend.

For most of my adult life, retirement spending was never something I worried about. Saving was.

Like millions of people, I spent decades training myself to save every extra dollar. I invested consistently, avoided unnecessary purchases, resisted lifestyle inflation, and watched my retirement accounts grow year after year.

Today, at 59 years old, I am financially independent.

Ironically, I’ve discovered that spending money is far more difficult than earning or saving it.

I don’t need to work another day in my life, yet I continue working because I genuinely enjoy what I do and I don’t know what to do with myself if I don’t have this daily activity called work. Meanwhile my investments continue to grow faster than I can realistically spend them.

The problem isn’t that I don’t have enough money.

The problem is that I no longer know how to spend it.

And it turns out I’m far from alone.

Retirement Spending is Harder than Saving

A recent Corebridge Financial survey found something surprising.

  • Fewer than one third of retirees feel comfortable withdrawing money from their retirement savings.
  • Seven out of ten retirees say it’s very important that their nest egg never shrinks.
  • Thirty-eight per cent admit they deliberately avoid spending money simply to preserve their savings.

Think about that.

People spent forty years saving for retirement…

… and once retirement finally arrives, many refuse to spend the money they worked so hard to accumulate.

That seems irrational.

Until you realize we’ve spent our entire lives being rewarded for saving.

We train ourselves to Accumulate, not Decumulate

Every paycheque teaches us the same lesson.

Save more.
Invest more.
Increase your net worth.
Watch the graph go up.

Personal finance books celebrate growing investment balances.

Financial news celebrates higher account values.

Net worth becomes the scoreboard.

Then retirement arrives and suddenly we’re expected to reverse decades of conditioning.

Instead of accumulating wealth, we’re supposed to slowly spend it.

Psychologically, that’s an enormous shift.

For many retirees, watching their investment account decline — even if it’s exactly according to plan — feels like failure.

My Retirement Spending Problem

When I imagined retirement in my Twenties, I assumed I would eventually spend money on expensive things:

A luxury car.

A larger house.

Designer clothes.

Fine dining every night.

None of that happened.

I live in Montreal, where owning a car would mostly be an inconvenience.

I have a comfortable apartment that suits me perfectly.

My wardrobe is simple. A good polo shirt lasts for years.

My favorite hobby is salsa dancing, and the best dance floor in the city is … free.

I eat out regularly, but because my cholesterol is high, my doctor has encouraged me to follow a mostly plant-based diet. Ironically, eating more healthily often costs less than dining out. And when I go out to eat, I go to small neighborhood restaurants to encourage the local owners. The waiters know me, the owners know me, and I feel at home.

I already take two international vacations every year.

Beyond that, I honestly don’t know what else I need.

The result?

My portfolio keeps growing because my spending simply hasn’t caught up with my savings.

Retirement Spending doesn’t mean Spending Carelessly

Many people hear this discussion and think the solution is simple:

“Just buy more stuff.”

I disagree completely.

Financial freedom isn’t permission to become a reckless consumer.

It’s permission to make choices based on happiness rather than necessity.

The goal isn’t to maximize spending.

The goal is to maximize fulfillment.

Sometimes that means spending more.

Sometimes it means spending exactly the same while feeling less guilty about it.

Better ways to Practice Retirement Spending

If you’ve accumulated more than you’ll likely spend, consider investing in experiences rather than possessions.

Some ideas include: Continue Reading…

What Successful Investing and The Great Gretzky have In common

Image courtesy Outcome/Shutterstock

By Noah Solomon,

Special to Financial Independence Hub

It’s been a long

A long time comin’, but I know

A change gon’ come

Oh yes, it will  

  • A Change Is Gonna Come, by Sam Cooke

Skate where the Puck is Going, not where it’s Been

Nicknamed “the Great One,” Wayne Gretzky has been called the best hockey player ever. Despite Gretzky’s unimpressive size and strength, his intelligence, stamina, and reading of the game were unrivaled. Gretzky himself credited much of his success to advice he received from his father as a young boy, which was to “skate where the puck’s going, not where it’s been.”

As is the case with the Great One, superior investment results stem in large part from anticipating future developments rather than simply positioning portfolios based on the past or current environment. To be clear, I am not referring to market timing, nor am I referring to predicting earnings, economic growth, inflation, or interest rates over the next quarter or year. As stated in past newsletters, such endeavours are highly unlikely to result in outperformance.

Rather, I am referring to significant changes in the investment landscape that (1) will likely persist for the next several years and (2) present both the risk of significant underperformance and the opportunity for material outperformance, depending on how one’s portfolio is positioned.

The most Powerful Force in Markets

Reversion to the mean is perhaps the most powerful force in markets: periods of higher-than-normal returns have been followed by periods of subpar returns, and vice versa. The postwar expansion and steady market gains of the late 1940s and 1950s were followed by stagflation and choppy, flat returns in the 1960s and 1970s. In similar fashion, the great bull run of the 1980s and 1990s ushered in the lost decade of the 2000s, when stocks delivered negative-to-flat returns.

This pattern is not coincidental but rather is firmly rooted in behavioural economics. For as long as modern markets have existed, people have overreacted, both in good times and bad. Following several years of strong economic and earnings growth, investors have repeatedly become overconfident that the proverbial party will continue indefinitely, causing stock prices to rise at a faster pace than earnings and multiples to reach unsustainable levels. At the other end of the spectrum, during periods of recession when earnings either decelerate or contract, widespread despondency morphs into predictions of eternal darkness with no possibility of improvement, resulting in lower than reasonable earnings expectations, multiple contraction, and fire sale asset prices.

The longer and stronger the expansion, the more irrationally exuberant people become, and the longer and darker the recession, the more illogically pessimism gets entrenched. Ironically, the most optimistic extrapolations reach a crescendo when they are least likely to be realized, and the most pessimistic ones become most widespread when they should be least so. The exact anatomy and causes of different booms and busts change from cycle to cycle, but the overall picture has remained tragically consistent. Plus ça change, plus c’est la même chose.

Markets have NOT been Normal

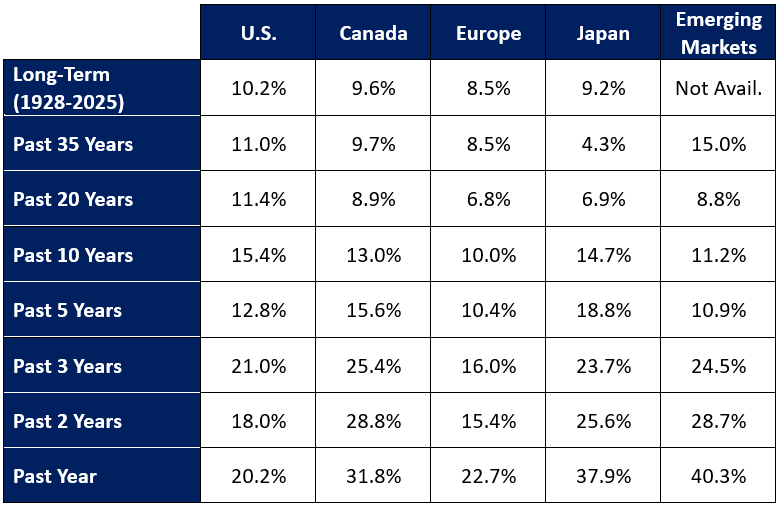
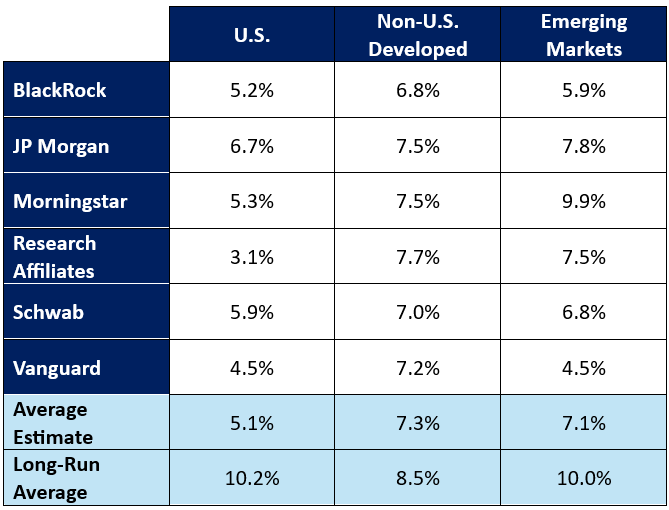
Investors today have grown accustomed to well-above-average returns. However, as the following table demonstrates, the past ten years have been highly anomalous from a historical standpoint.

Equity Market Returns: A Longer-term Perspective


Notwithstanding the daunting historical pattern of mean reversion, the post-global-financial-crisis environment has been highly supportive of equities. Increased globalization, moderate inflation, and low interest rates supported strong earnings growth and expanding valuation multiples, which in turn spurred above-average returns.

In contrast, today’s landscape is marred by trade frictions, stubborn inflation, ballooning sovereign debt levels, and rising interest rates. Importantly, these structural headwinds for earnings growth stand in sharp contrast to today’s elevated valuations, with U.S., Canadian, and European indexes all standing in the top fifth of their historical valuation ranges.

I have no idea whether markets will rise or fall over the near-to-medium term, let alone exactly when or by how much. However, given the historically inverse relationship between starting valuations and forward, ten-year returns, I am confident that average returns over the next ten years will likely be lower than long-term averages, and perhaps meaningfully so. History seems primed to repeat itself, if not rhyme.

Estimating returns requires sophisticated assumptions, and methodologies used to do so vary across asset managers. Yet, despite these differences, a common theme emerges: most asset managers forecast low future equity returns.

Annualized Equity Return Forecasts: Next 10 Years


What REALLY drives the Bus

It goes without saying that a portfolio’s individual stock holdings and sector weights are important determinants of its return. However, there is more than meets the eye with respect to performance attribution. Continue Reading…

The alternative to the 4% Rule isn’t a different number. It’s a different mechanism.

By Stefano Starkel

Special to Financial Independence Hub

Ask for an alternative to the 4% Rule and most people offer you 3.5%, or 5%, or a dynamic band. Those answer the wrong question. The rule’s most important feature isn’t the number: it’s the assumption buried in its first sentence.

William Bengen’s 1994 study said this: Withdraw about 4% in year one, adjust that dollar amount for inflation, and across the worst U.S. sequences he tested no portfolio was exhausted before 33 years. He has revised it upward since: to roughly 4.7% in his 2025 book. The number was never the fragile part.

Notice how you get the cash. You sell. The 4% Rule is a selling rule, and most Retirement calculators inherit that frame: the portfolio is the only lever, drawing it down the only way to reach it. So “what’s the alternative” is really two questions: a smarter way to size withdrawals, or not drawing the pile down at all?

Why the number isn’t the weak point

The fragile part of a fixed-withdrawal plan is Sequence-of-Returns risk. I run a leveraged, income-oriented book myself, and I’ve watched how brutally the order matters.

Round numbers: A $1,900,000 portfolio. $76,000 withdrawn at the start of each year, held flat, then that year’s return applied. (The real rule inflates the withdrawal; flat isolates the sequence effect, and understates the damage.) Two retirees, same three returns, opposite order.

Same returns, same withdrawals, and B finishes about $80,000 behind: a gap that compounds with every subsequent return. The reason sits in year two: B took that $76,000 from a portfolio already down to $1.28M, a 6.0% bite against A’s 3.5%. Selling a fixed amount into weakness turns a paper dip into spent-and-gone principal. Over a full retirement, that early-sequence damage is what empties portfolios: not the headline rate.

Changing the mechanism, and what it costs

One family keeps selling, but flexibly: guardrails soften Sequence Risk at the cost of variable income. Still decumulation.

The other changes the mechanism: borrow against the portfolio rather than sell it, so the assets stay invested and nothing is forced to be realised in a downturn. This is what people mean when they say the wealthy never sell. It is not a free lunch : and for a Canadian reader, considerably less free than the American version.

The loan is callable. FINRA’s mandated margin disclosure is blunt: the firm can sell your securities without contacting you, you don’t choose which ones, and you aren’t entitled to extra time. Canada is no gentler: TD Direct Investing tells clients it may sell holdings “potentially without any prior notice,” and decide which. That is the bottom-of-the-market sale the strategy exists to avoid, arriving on the broker’s schedule. Continue Reading…

Gold or Silver? How to prepare for what comes next

By Andrew Sleigh, Sprott Money

Special to Financial Independence Hub

When people ask me whether they should start with gold or silver, my answer depends largely on where they are financially. If you’re dealing with tens or hundreds of millions of dollars, you’re generally going to come in heavily with gold, although I still think you need silver.

For the average Canadian or American with less than one or two million dollars in assets, I would establish a position in silver coins first and then supplement that with gold. There’s no perfect percentage. You can fine-tune your gold and silver allocation as you become more educated and understand what each metal is supposed to accomplish. The important thing is building the position before everybody suddenly decides they want physical precious metals at the same time.
⠀⠀
Why I would Start with Silver Coins

People ask why I recommend silver coins instead of 100-ounce silver bars, especially when bars can have lower premiums. My answer is transactability. If all you own are large bars, how are you going to handle smaller transactions if silver ever needs to function as money? I made this mistake myself. When I started buying physical silver, I bought seven 100-ounce bars. I knew I wanted physical metal, but I didn’t yet understand which products made the most sense. After listening to people who had been stacking for decades, I exchanged those bars for coins.

My basic approach for somebody starting today would be:

  • Establish a position in recognizable silver coins first.
  • Add physical gold as the overall position becomes larger.
  • Move into 10-ounce or 100-ounce silver bars after you’ve accumulated enough coins.
  • Don’t concentrate everything into denominations that could be difficult to transact with. The objective isn’t simply getting the most ounces for the lowest premium. It’s owning precious metals in forms that could actually be useful when you need them.

Not every Ounce of Silver is Equal in the Real World

I used to believe an ounce was an ounce and bought whichever silver product was cheapest. Then I realized it’s not only about what I understand about silver. It’s about what the person on the other side of the transaction understands. I’ve encountered people who were only comfortable with Canadian Silver Maple Leafs because they recognized and trusted them. An experienced precious metals owner may happily accept a generic one-ounce round, while somebody less familiar with silver may want a Maple or, in the United States, a Silver Eagle.

That’s why I want a mixture that gives me options:

• Recognizable sovereign silver coins for people who want something familiar.
• Generic rounds for people who understand silver and simply care about weight and purity.
• Larger bars only after I’ve established enough smaller denominations. If precious metals ever become more commonly used for barter, recognizability could become almost as important as the silver itself.
⠀⠀
Why I’m concerned about the Financial System

I see substantial risk in the conventional financial system, particularly in currencies and long-duration bonds. As interest rates rise, older bonds paying much lower yields become less attractive and can lose significant market value if they need to be sold. At the same time, governments across the West continue running enormous fiscal deficits. Canada has this problem, the United States has it, and Europe has it. To me, we’re watching currencies compete in a race to the bottom.

When gold and silver rise in dollar terms, I don’t necessarily look at that as the metals suddenly becoming more valuable. I also look at what is happening to the currency they’re measured in. You can see declining purchasing power every time you go grocery shopping. If governments continue expanding deficits and pursuing inflationary policies, I believe protecting purchasing power becomes increasingly important. That’s a major reason I want physical gold and silver rather than relying entirely on paper assets and currency.
⠀⠀
Why Silver Demand could become Enormous

Silver is particularly interesting because it has both monetary and industrial demand. There are already numerous industries competing for physical silver, including

• Electrification and renewable energy.
• Electronics and advanced technology.
• Automation and robotics.
• Global manufacturing.
• Defense and military applications.

Then you add investors who want physical metal because they’re increasingly concerned about the financial system. It doesn’t take the entire population buying silver to create shortages. If even a relatively small additional percentage of people suddenly wants physical bullion, retail inventories can tighten very quickly. We’ve already experienced periods when dealers struggled to source products such as Silver Maples and 100-ounce bars. The public tends to assume they’ll always be able to buy physical metal whenever they decide they need it. I don’t make that assumption. I’d rather accumulate gradually while it’s readily available.
⠀⠀
Physical Metal isn’t a Short-term Trade for me

If your objective is trading gold and silver price movements, physical bullion probably isn’t the most efficient vehicle. Premiums and spreads can eat into short-term trades. That’s not why I own physical metal. For me, physical gold and silver are first and foremost about wealth preservation.

I think people need to separate two completely different objectives:

• Trading precious metals: Trying to profit from short-term movements in gold and silver prices.
• Owning physical precious metals: Protecting purchasing power and keeping tangible wealth under your control.
If silver substantially outperforms and you sell everything to lock your gains back into dollars, you’ve put yourself back into the currency you were trying to protect yourself from. Physical metal gives me wealth already in my possession or under my control. I don’t have to sell a financial product, receive currency, and then hope I can convert that currency into something tangible during a crisis.
⠀⠀
Gold and Silver still have Monetary Value

I’ve talked to people who have already used precious metals for barter in private transactions. I once asked a gentleman shining my shoes at the Toronto airport whether he would accept silver as payment. He immediately said yes. One silver coin represented too much value for the shoe shine, but the point was that he recognized the value and was willing to accept it.

You’re probably not walking into a major grocery chain today and paying for groceries with Silver Maples. But that doesn’t mean precious metals have lost their monetary characteristics. If confidence in conventional currencies or payment systems deteriorates significantly, I think recognizable gold and silver could play a much larger role in private transactions. That’s another reason I want smaller-denomination silver rather than having everything concentrated in large bars.
⠀⠀
How I would prepare with Gold and Silver today

Physical precious metals aren’t completely risk-free. Prices fluctuate, premiums matter, and bullion needs to be stored securely. That’s why I believe in nibbling away rather than trying to perfectly time one enormous purchase.
If I were building a position today, my priorities would be:

• Build a foundation of recognizable physical silver coins.
• Gradually add gold as the amount of wealth being protected increases.
• Add larger silver bars once enough smaller denominations are already owned.
• Keep some physical cash available for immediate expenses.
• Think carefully about secure storage.
• Don’t advertise what you own or where you keep it.

I’m not trying to perfectly trade every move in gold and silver. I’m trying to preserve purchasing power and maintain tangible wealth under my control. Financial problems can develop inch by inch and then seemingly happen all at once. I’d rather prepare incrementally while gold and silver are available than wait until everybody else reaches the same conclusion at the same time.
Andrew Sleigh is a Sales Representative at Sprott Money with over 32 years of financial industry experience. After beginning his career as an insurance broker in 1991, he became an independent financial broker, providing financial planning, investment, insurance, and benefit solutions. In 2017, Andrew shifted his focus to bullion and precious metals, helping individuals and businesses understand how hard assets can play a role in wealth preservation.
Time for Core (Plus) Bond Portfolios Again?

By Christy Tan and Lukasz Labedzki, Franklin Templeton Institute

(Sponsor Blog) 

Investment Implications

We see growing evidence suggesting that investors should consider moving from a short-duration bias toward core (plus) bond portfolios. This is largely predicated on the fact that valuations have become more attractive across fixed-income sectors, with all-in yields approaching compelling levels. Our guidepost remains 10-year Treasury yields near the upper end of their recent range. We continue to believe that this is a market for an active, selective approach.

Please see our sector views below.

Central banks: We have a new Federal Reserve (Fed) chair, and if we take him at his word, it feels
like a new environment has begun. The rhetoric is hawkish, reinforcing that the 2% inflation target is
by no means soft. Importantly, there’s also a strong push for no forward guidance, with the market
invited to react to incoming data as it sees fit. That likely means a higher-volatility environment and,
all else equal, a higher risk premium demanded by bond investors. As a result, all eyes are now on
the data. If the data fails to confirm moderating inflation, the market will demand Fed action. If the
data does confirm it, the market can justify a pause. In both cases, longer duration can perform
well. The risk is the Fed policymakers talking but not acting when needed: that would make the
bond market angry. We see the risk-reward of extending duration as improving and are happy to do
so at certain yield levels.

US Treasuries: Our view is that 10-year Treasury yields will remain broadly range-bound, which
means the closer they get to 4.75%, the more attractive it becomes to move into intermediate
duration. We believe it is reasonable to begin extending duration around those yield levels.

Developed markets credit: Historically elevated investment-grade bond issuance that the market
needed to absorb widened spreads from their tights to levels closer to fair value, while the broader
fundamental backdrop remains healthy. Supply should also slow in the second half of the year. In
the high-yield space, spreads have also widened somewhat. We remain biased toward higher-rated
issuers in high yield. All-in yields are attractive and provide resilience across a range of scenarios.

Emerging market (EM) debt: While it has been the best-performing fixed-income sector
year-to- date, we think it’s time to be more selective. In local-currency EM debt, Latin America
has been the top performer (as we highlighted), and we expect this to continue. As a stronger US
dollar remains a risk, in our view allocations should be balanced with US dollar-denominated EM
debt, which is less sensitive to currency moves.

Euro bonds: As mentioned previously, we believe German Bund yields (Europe’s benchmark
government bond yields) will remain broadly range-bound. They closely track expected mone-
tary policy, which has recently been driven largely by gas prices. With Bund yields above 3.1%, we
find them attractive for medium-term investors. Hedged yields for US dollar-based investors are
on par with US Treasuries, meaning there is little opportunity cost to global diversification.

Performance Snapshot

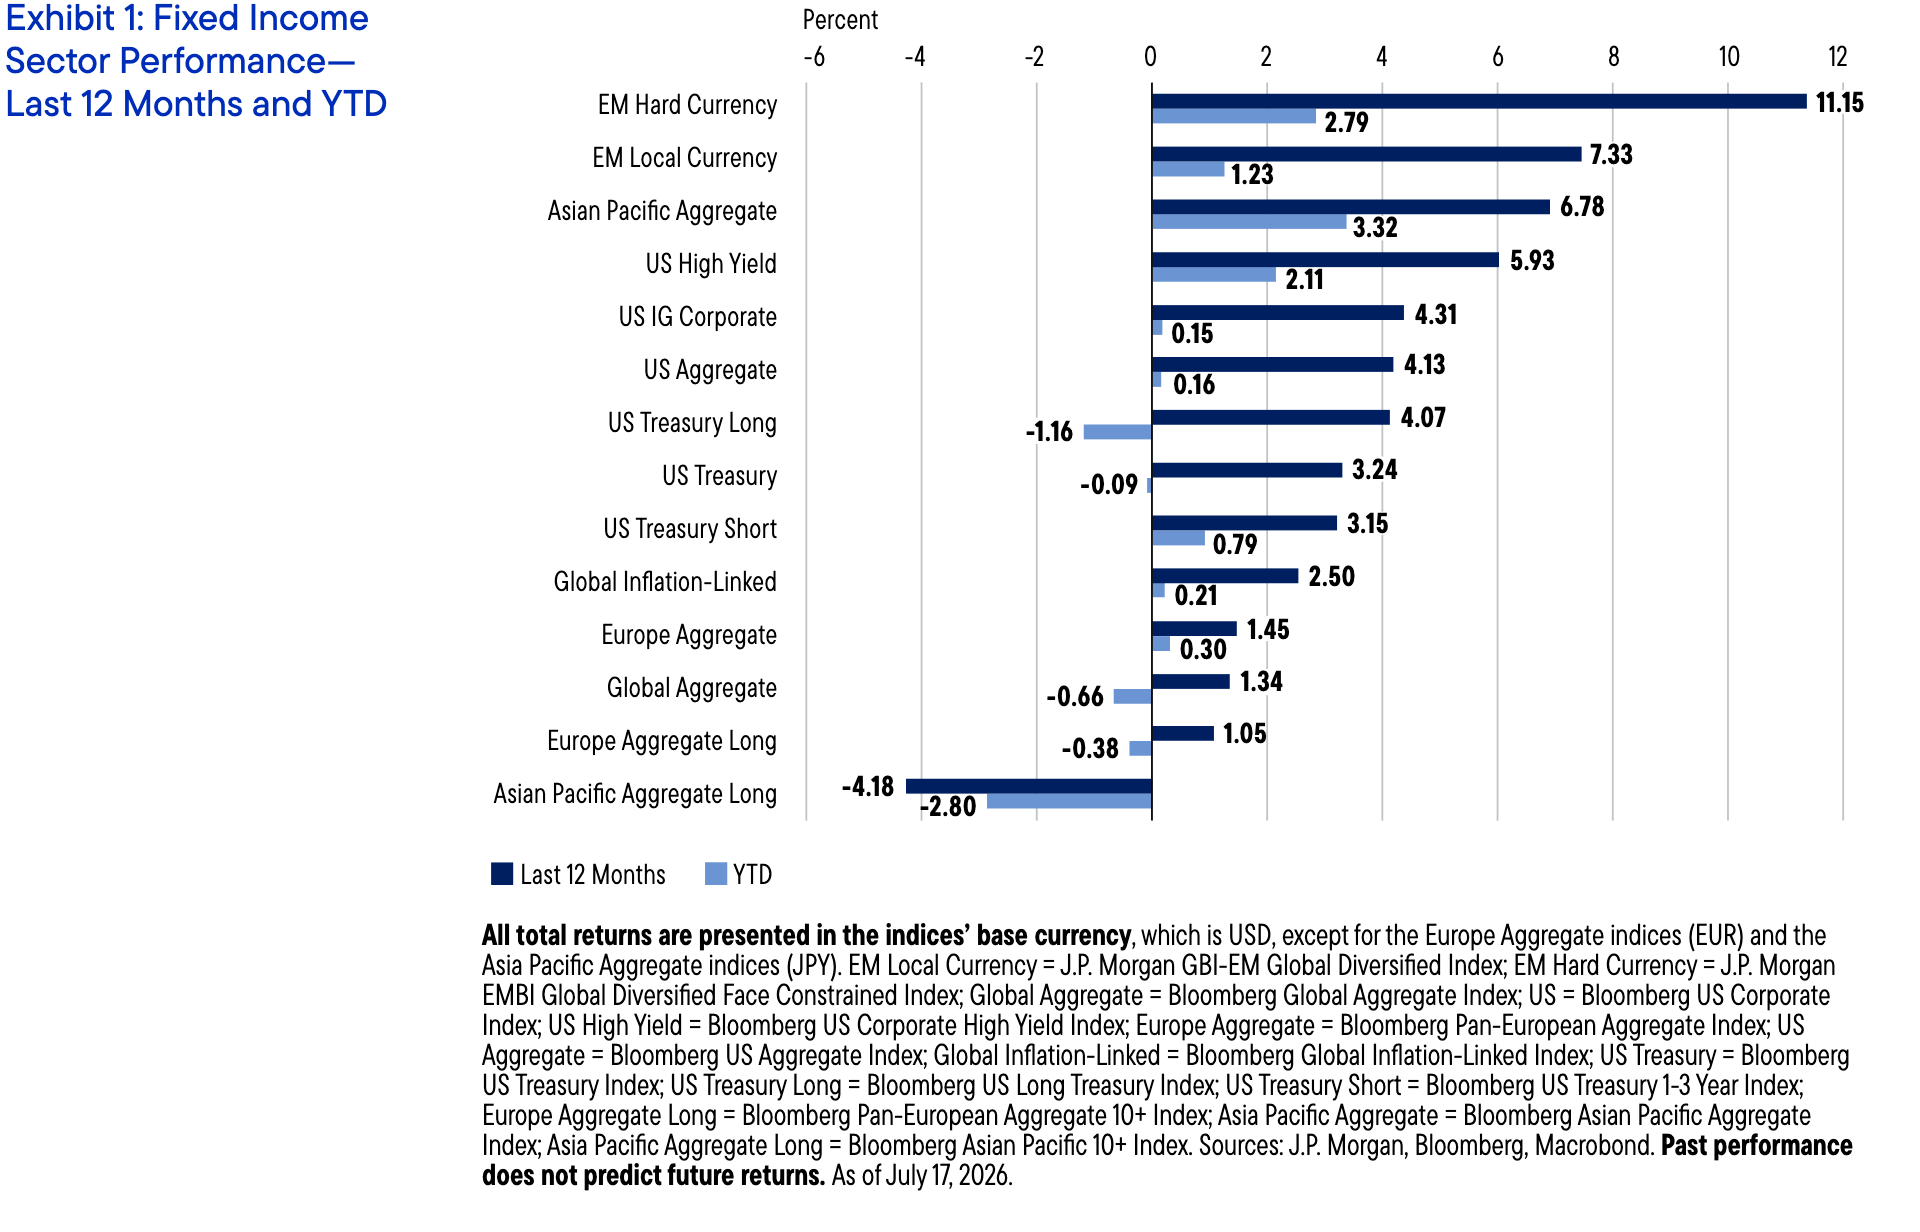
Global fixed-income performance has remained largely uninspiring this year, with the Bloomberg
Global Aggregate Index still slightly underwater. Relative performance has been stronger in
emerging market debt, particularly US dollar-denominated debt. The picture is more nuanced in
local-currency EM debt, which we discuss later. US high yield has also outperformed. Within
higher-quality fixed income, US short-duration strategies have also held up relatively well. These
are essentially the sectors we have been highlighting throughout the year.


US Treasuries

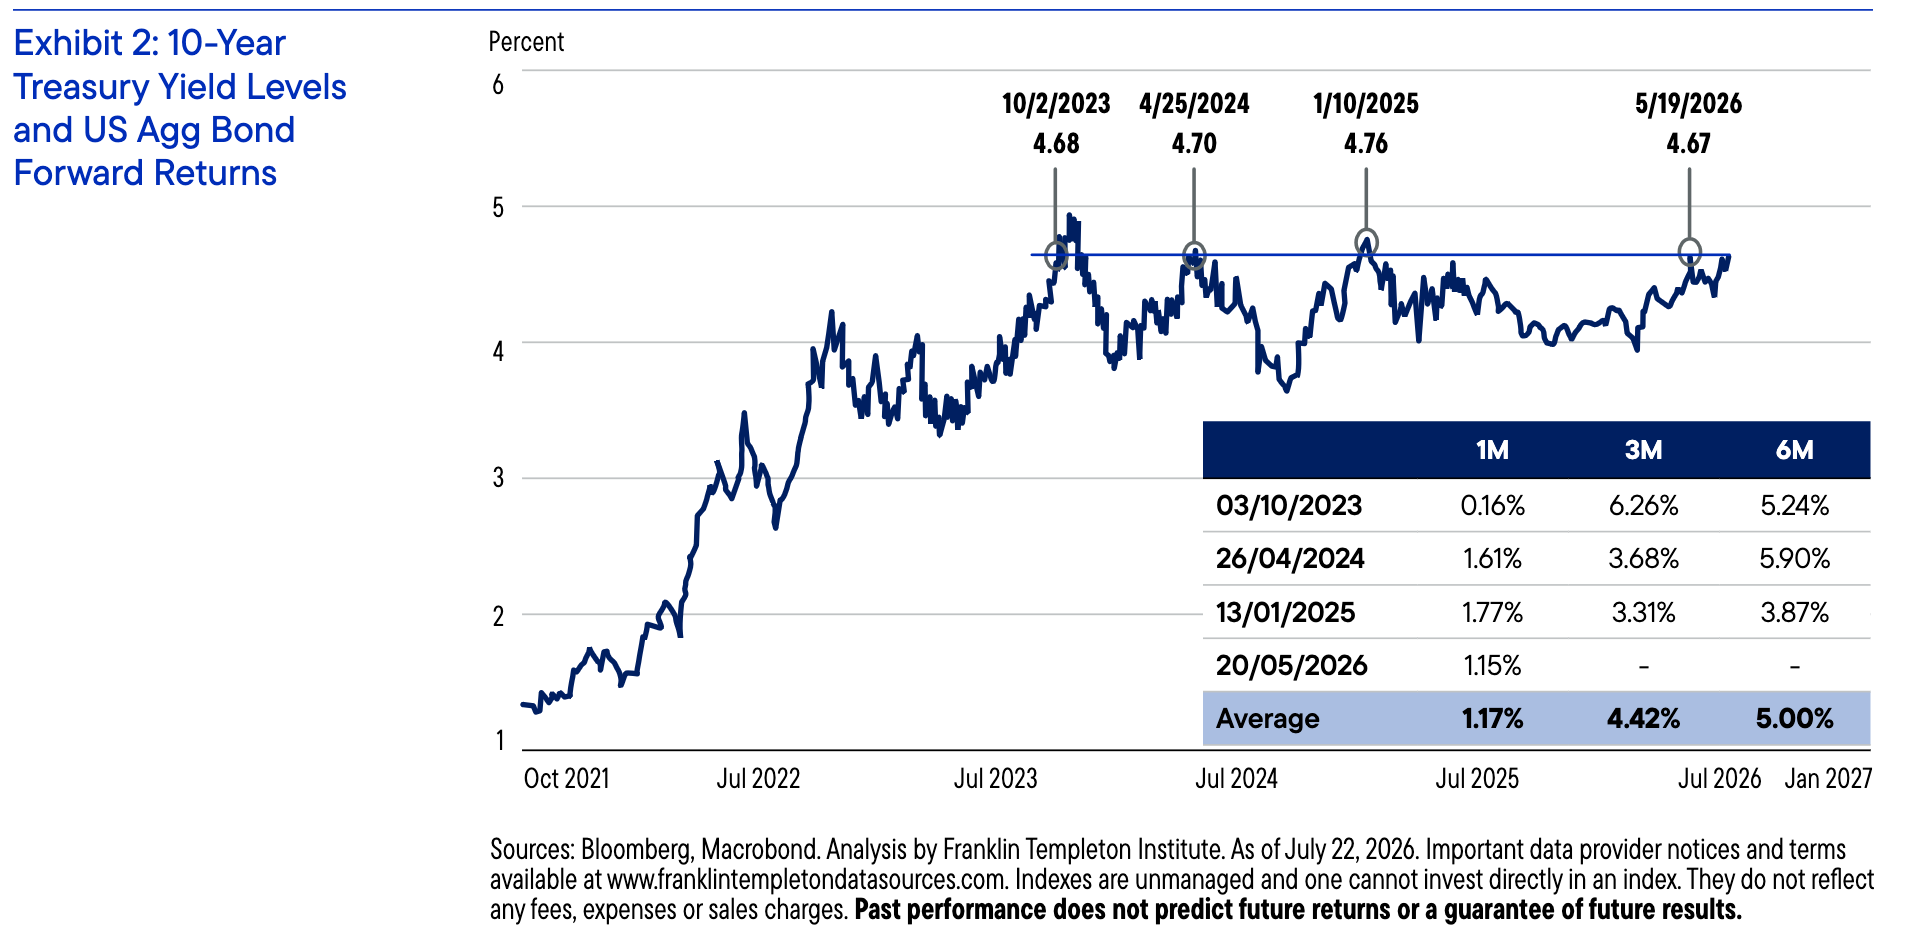
We believe benchmark 10-year Treasury yields will remain broadly range-bound, and investors should take advantage when yields are close to the upper end of that range (~4.75%). Recent history (Exhibit 2) suggests this strategy has worked well and remains our playbook for the second half of 2026.


Of course, yields could move higher, but at these levels we view the risk-reward as favorable and do not see a high risk of yields moving significantly above the recent range over the coming months. The main reason is that a lot is already priced in: the market expects more than two Fed hikes over the next 12 months,1 while the current term premium (the risk premium in bond jargon) is close to 70 basis points (bps),2 versus a recent high of around 90 bps. A meaningful move above 5% in 10-year Treasury yields would likely require a further significant repricing of both monetary policy expectations and the term premium.

The major risk is that the Fed turns more hawkish than in our base case. We acknowledge this risk, but we also think that realized hikes could, in fact, cause longer-duration bonds to catch a bid, as they would demonstrate a strong commitment to fighting inflation and could lead to a repricing of growth expectations.

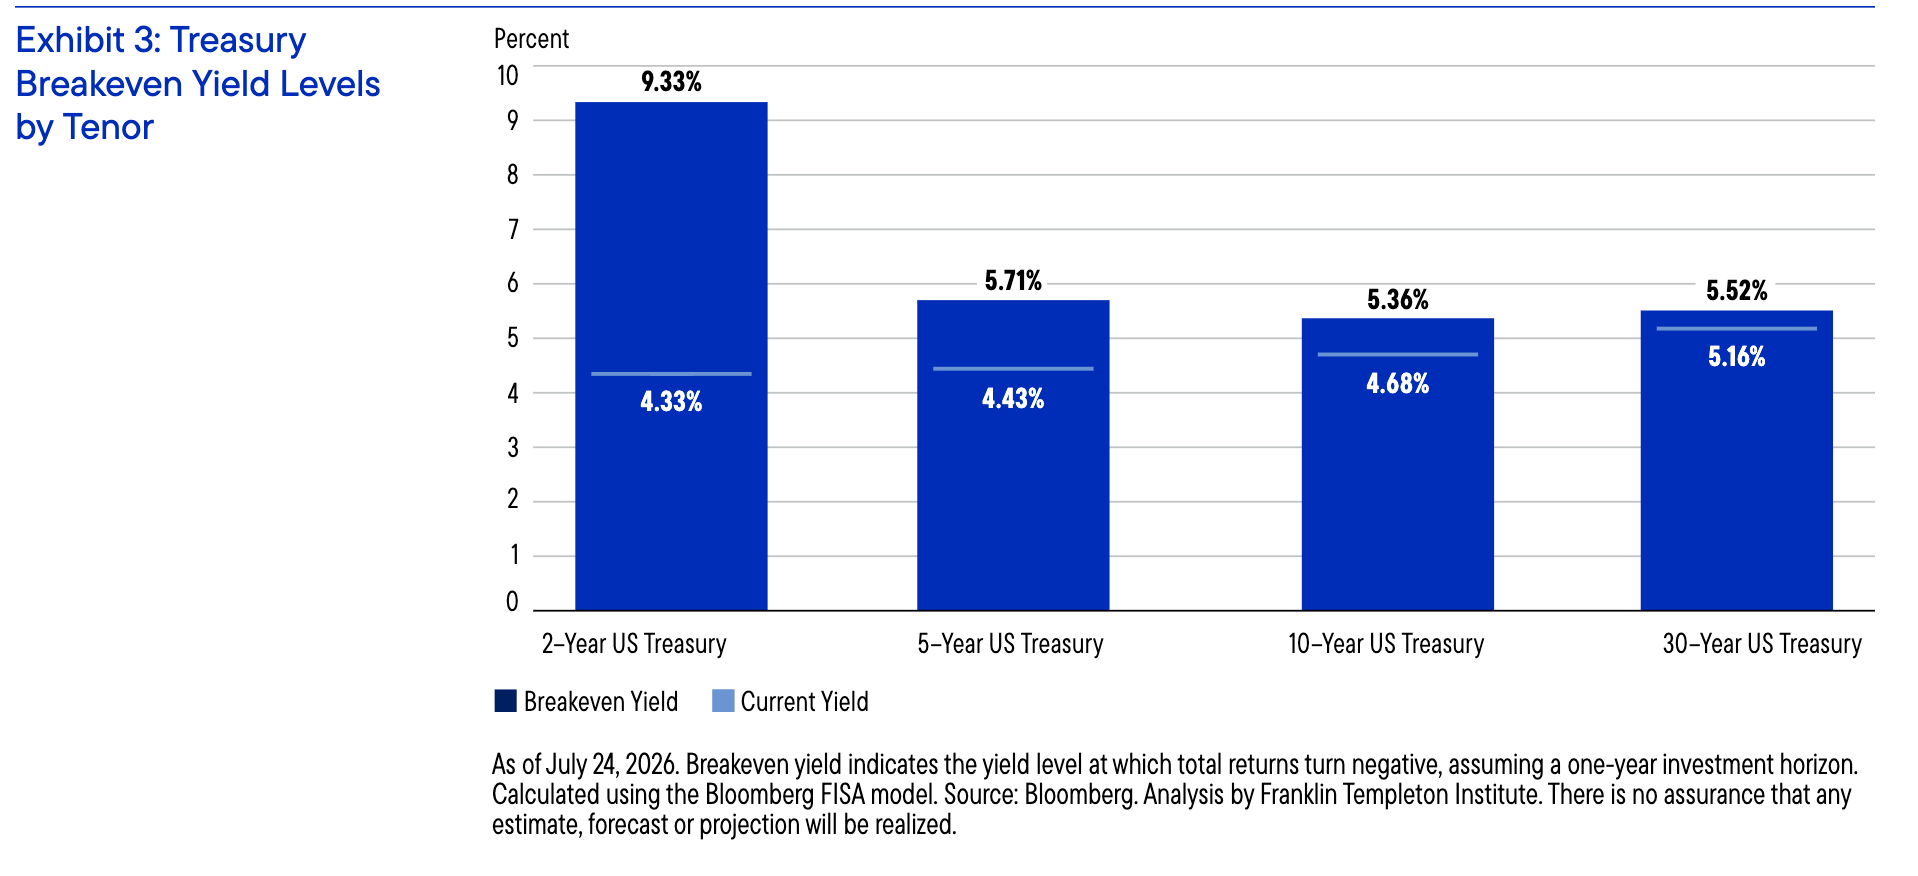
For conservative mandates, we continue to view short-duration bonds as a portfolio pillar. They are highly resilient across scenarios: two-year Treasury yields would need to rise above 9% before investors started losing money, assuming a one-year investment horizon (Exhibit 3).

Developed Markets Credit

The major story in credit markets lately has been investment-grade (IG) bond supply, driven in part by hyperscaler borrowing. More than US$1.2 trillion3 of IG issuance came to market through the first six months of the year: well above historical norms (Exhibit 4). Continue Reading…