Inflation

Inflation

Is it time to time the market?

By Steve Lowrie

Special to the Findependence Hub

Has market news got you thinking it might be time to rethink your market positions?  It’s certainly understandable if the economic uncertainty unfolding in the daily news has left you wondering – or worrying – about what lies ahead.  No matter how you feel about the U.S. entering into a trade war with China, it’s hard to deny that the prospect is currently causing considerable market turmoil.  It is also hard to avoid the recent financial media obsession with an “inverted yield curve” (a rare situation when short-term bond maturities are yielding more than longer-term maturities).

You might have heard that each U.S. recession since the 1970s has been preceded by an inverted yield curve.  However, perhaps for the sake of sensationalism, not all articles correctly report that this relationship does not always hold true.  In reality every yield curve inversion does not lead to an imminent recession and/or lower equity prices.  Recent analysis by professors Eugene Fama and Ken French tested this very hypothesis.  Using data from the U.S. and 11 other developed markets, they found “no evidence that inverted yield curves predict stocks will underperform bills (bonds).”

Regardless of how the coming weeks and months unfold, are you okay with gritting your teeth, and keeping your carefully structured portfolio on track as planned?  This probably doesn’t surprise you, but that’s exactly what we would suggest.  Unless, of course, new or different personal circumstances warrant revisiting your asset allocation for reasons that have nothing to do with all the tea in China.

That said, the recent news is admittedly unsettling. If you’ve got your doubts, you may be wondering whether you should somehow shift your portfolio to higher ground, until the coast seems clear.  In other words, might these stressful times justify a measure of market-timing?

Here are four important reminders on the perils of trying to time the market – at any time. It may offer brief relief, but market-timing ultimately runs counter to your best strategies for building durable, long-term wealth.

1) Market-Timing is Undependable 

Granted, it’s almost certainly only a matter of time before we experience another recession.  As such, it may periodically feel “obvious” that the next one is nearly here.  But is it?  It’s possible, but market history has shown us time and again that seemingly sure bets often end up being losing ones instead.  Even as recently as year-end 2018, when markets dropped precipitously almost overnight, many investors wondered whether to expect nothing but trouble in 2019.   Continue Reading…
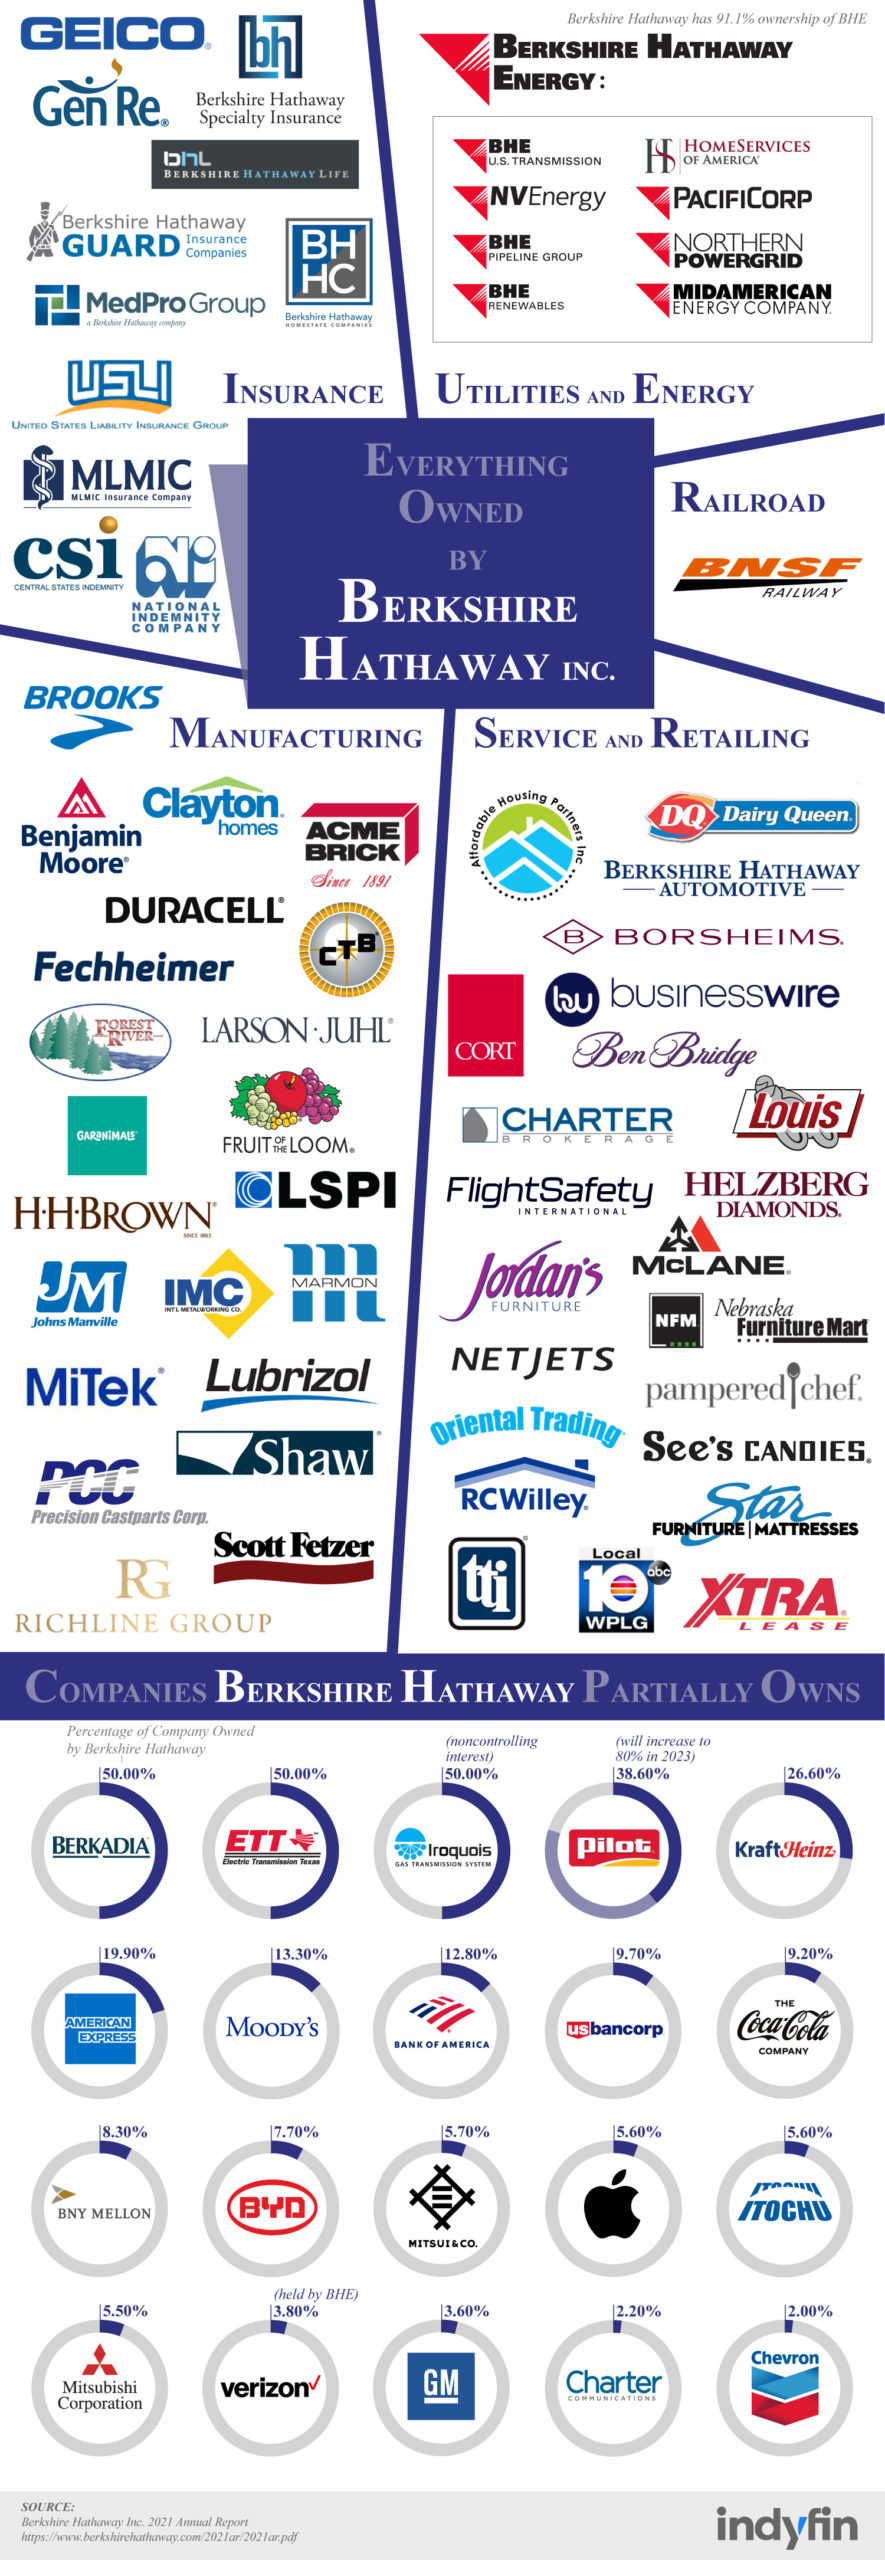
Everything owned by Warren Buffett’s Berkshire Hathaway

Warren Buffett of Berkshire Hathaway, which just held its first live annual meeting since Covid hit.

By Akshay Singh

Special to the Financial Independence Hub

You’ve probably heard of the multi-billion dollar company Berkshire Hathaway, owned by mega-billionaire and philanthropist Warren Buffett, but what does Berkshire Hathaway do exactly?

Berkshire Hathaway Inc. is a conglomerate holding company, meaning it does not produce goods or services and instead has a controlling interest in and owns shares of other companies to form a single corporate group.

That leads us to our next question: What companies does Berkshire Hathaway own to make it one of the most valuable companies on the planet? The team at Indyfin turned to the 2021 Berkshire Hathaway annual report to create this compendium of all of the Berkshire Hathaway companies. The holding company has a controlling interest in more than 60 companies and partially owns another 20 on top of that. You’ll recognize a lot of brand names from a wide variety of industries that make up the impressive Berkshire Hathaway portfolio.

Does Berkshire Hathaway own one of your favorite or most-used brands? Check out this roundup of Berkshire Hathaway companies from Indyfin to find out.

What Is Berkshire Hathaway?

Berkshire Hathaway is an American conglomerate holding company with a market cap of US$774.24 billion, making it the seventh most valuable company in the world. What is a conglomerate? A conglomerate is a combination of businesses from a variety of different industries that operate as a single economic entity under one corporate group. Conglomerates are usually large and multinational and generally include a parent company and many subsidiaries. The “conglomerate fad” was big in the 1960s due to low interest rates, rising prices, and a decline in the stock market, which led to large corporate conglomerates like Berkshire Hathaway forming. The parent company in this scenario is also referred to as the holding company, as it holds a controlling interest in the securities of all of the other companies. Holding companies do not produce goods or services; instead, they own shares of other companies to form a single corporate group. Holding companies are beneficial because they reduce risk for shareholders and can hold and protect assets like trade secrets or intellectual property.

What Does Berkshire Hathaway own? Continue Reading…

Why it might be time to rebalance the 60/40 Rule


Investors follow the 60/40 rule because they are told bonds will protect capital while equities grow it. Why recent drops in bond prices should make us reconsider that rule. 


By Paul MacDonald, CIO, Harvest ETFs

(Sponsor Content)

From the moment they start putting money in the market, investors are told to follow the 60/40 rule. It is the broadly accepted wisdom that, for an average retail investor, a 60% allocation to equities and a 40% allocation to bonds will result in a robust portfolio. Equities should deliver growth prospects in the long term while bonds will offset downsides in equities by delivering uncorrelated returns. Bonds preserve capital, and equities grow capital. That’s the accepted wisdom. 

Countless investment fund issuers have packaged this logic into their balanced funds. These funds offer a specific allocation to equities and bonds, usually in line with the 60/40 rule, forming the core of a retail investor’s portfolio.

The problem with accepted wisdom is sometimes circumstances turn it upside down. In the past months we have seen volatility in equity markets and a significant drop in bond prices. That is because the investment landscape has changed. 

Why are bond prices dropping? 

After over a decade of historically low interest rates, followed by massive rate cuts by central banks at the onset of the COVID-19 pandemic, inflation has begun to set in. With rising inflation comes pressure on central banks to raise rates and market expectation that rates will rise, which is itself pushing interest rates higher.  Continue Reading…

Death of Bonds or time to buy short-term GICs?

My latest MoneySense Retired Money column looks at a recent spate of media articles proclaiming the “Death of Bonds.” You can find the full column by clicking on the highlighted headline: Do bonds still make sense for retirement savings?

One of these articles was written by the veteran journalist and author, Gordon Pape, writing to the national audience of the Globe & Mail newspaper. So you have to figure a lot of retirees took note of the article when Pape — who is in his 80s — said he was personally “getting out of bonds.”

One of the other pieces, via a YouTube video, was by financial planner Ed Rempel, who similarly pronounced the death of bonds going forward the next 30 years or so and made the case for raising risk tolerance and embracing stocks. The column also passes on the views of respected financial advisors like TriDelta Financial’s Matthew Ardrey and PWL Capital’s Benjamin Felix.

However, there’s no need for those with risk tolerance, whether retired or not, to dump all their fixed-income holdings. While it’s true aggregate bond funds have been in a  de facto bear market, short-term bond ETFs have only negligible losses. And as Pape says, and I agree, new cash can be deployed into 1-year GICs, which are generally paying just a tad under 3% a year;  or at most 2-year GICs, which pay a bit more, often more than 3%.

One could also “park” in treasury bills or ultra short term money market ETFs (one suggested by MoneySense ETF panelist Yves Rebetez is HFR: the Horizons Ultra-Short Term Investment Grade Bond ETF.) It’s expected that the Fed and the Bank of Canada will again raise interest rates this summer, and possibly repeat this a few more times through the balance of 2022. If you stagger short-term funds every three months or so, you can gradually start deploying money into 1-year GICs. Then a year later, assuming most of the interest rate hikes have occurred, you can consider extending term to 3-year or even 5-year GICs, or returning to short-term bond ETFs or possibly aggregate bond ETFs. Watch for the next instalment of the MoneySense ETF All-stars, which addresses some of these issues.

Some 1-year GICs pay close to 3% now

Here’s some GIC ideas from the column: Continue Reading…

Inflation in Retirement

By Billy Kaderli, RetireEarlyLifestyle.com

Special to the Findependence Hub

First things first, what is inflation? Inflation is when too much money is competing for a finite number of goods. This causes a general increase in prices and a fall in the purchasing value of money.

The US Real-Estate market is a prime example, and we have all witnessed the rising home values. Translate this to food and energy, and this is the effect we are feeling today.

Current inflation numbers

Recent inflation numbers came in at 8.5% year-over-year. The producer price index (PPI) came in higher at 11.2% which means it is costing more for the producers to manufacture products.

These increases get passed on to you and me, the consumers, and we are going to be feeling these increases now and on into the future.

How can you protect yourselves in retirement?

Perhaps you are living on a fixed income such as Social Security. [or in Canada: CPP and Old Age Security.]  Your annual Social Security adjustment doesn’t keep up with grocery and fuel costs; thus, you are slipping backwards.

This is not a good position to be in.

One answer is to own equities. Continue Reading…