Building Wealth

For the first 30 or so years of working, saving and investing, you’ll be first in the mode of getting out of the hole (paying down debt), and then building your net worth (that’s wealth accumulation.). But don’t forget, wealth accumulation isn’t the ultimate goal. Decumulation is! (a separate category here at the Hub).

Retired Money: Work Optional and the FIRE movement

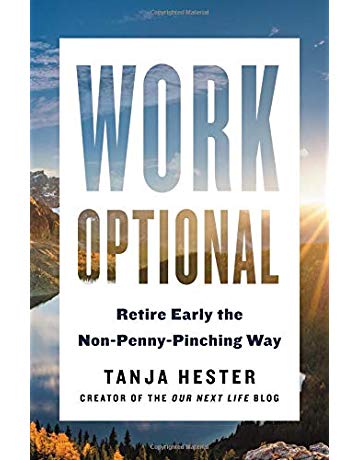
My latest MoneySense Retired Money column looks at the so-called FIRE movement: (an acronym for Financial Independence/Retire Early), as well as a new book by a FIRE blogger titled Work Optional. You can find the full column by clicking on the highlighted headline here: How “Work Optional” can fit into your Retirement Plan.

You’ll see that regular Hub blogger Doug Dahmer — founder of the Retirement Navigator planning software — has been using the phrase Work Optional for at least five years, even though the new book of that name was just published in January 2019. It’s a useful phrase that describes the kind of thing Mike Dark and I refer to as Victory Lap Retirement in our jointly authored book of the same name.

There are many ways to describe this phase, but generally it refers to a period after full-time employment. FIRE proponents often declare that they “retired” in their 30s or 40s but of course most of them do not spend the next half century doing absolutely nothing. They really create encore careers based on self-employment, and often build businesses based on book-publishing, blogging and public speaking, wherein they reveal “how they did it.”

Victory Lap and Findependence

To some extent this very website does a similar thing, focused as it is on Financial Independence, or my contraction of it, Findependence. Continue Reading…

10 keys to picking the best Canadian income trusts and REITs

Canadian income trusts have always involved far more risk than most investors realize. This is why we’ve recommended so few of them in the past.

Income trusts are a type of investment trust that holds income-producing assets. Their units trade on stock exchanges, but they flow much of their income through to unit holders as “distributions.”

On January 1, 2011, Ottawa imposed a tax on distributions of income trusts. The new tax put income trusts on an equal tax footing with regular corporations.

Virtually all Canadian income trusts then converted into conventional corporations. But some are still out there: mostly real estate investment trusts (REITs).

Investing in trusts — and in particular oil and gas trusts — was risky, as the businesses that underpinned them needed steady cash flow. But that could stagnate during economic downturns. At the same time, we believed that investors should have looked for trusts with low capital expenditures and mature businesses.

More about Canadian Income Trust taxes

Canada offers special tax treatment for Canadian income trusts. When they flow their income through to their unitholders, they don’t pay much if any corporate tax. Investors pay tax on most of the distributions as ordinary income (although some distributions qualify as a tax-free return of capital).

Ottawa feels the income-trust business structure is appropriate for real estate investment trusts, or REITs, so it has exempted REITs from the income-trust tax.

Real estate investment trusts resemble Canadian income trusts, but with a key difference: REITs invest in income-producing real estate, such as office buildings, shopping centres and hotels. (We cover a number of carefully selected income trusts and real estate investment trusts in our Canadian Wealth Advisor newsletter.)

Regardless of whether or not they have converted, the basic tests we use to ferret out good investments and reject bad ones still apply, not only to Canadian income trusts, but to other types of investments, as well.

Keep “Investment Inputs” in mind when judging income trusts, or any investment

In evaluating investments, many investors focus on what we’d call “investment outputs,” such as earnings, dividends, cash flow, return on equity, sales growth and so on. These are all important, of course, but you shouldn’t focus on them to the exclusion of what you might call “investment inputs.”

Investment inputs are harder to work with than investment outputs, since it takes a judgment call to determine their risk or value. To give you a better idea of what we mean, here are 10 keys to picking the best Canadian income trusts and real estate investment trusts. We look each before recommending any income trust: Continue Reading…

Should you invest in pot stocks? How do you invest in the cannabis sector?

The importance of diversification

By Noah Solomon

Special to the Financial Independence Hub

Harry Markowitz, recipient of both the 1990 Nobel Memorial Prize in Economic Sciences and the 1989 John von Neumann Theory Prize, referred to diversification as “the only free lunch in finance.”

As most investors are aware, diversification is an essential element of any well-constructed portfolio. Diversification across different markets and individual securities can lower volatility, mitigate losses in declining markets and produce higher risk-adjusted returns over the long-term.

Easier said than done: the temptation to chase returns

Of course, during times when one asset class or country outperforms for an extended period, this can lead to feelings of regret. Looking in their rear-view mirrors, investors often wish that they had been less diversified and had an overweight position in the outperforming asset class. This regret can result in FOMO (fear of missing out), whereby investors pour capital into those areas of the markets which have been outperforming.

The U.S. stands alone

Since the post-financial crisis market bottom of March 2009, the U.S. stock market has dwarfed those of other markets in terms of performance. U.S. stocks have produced almost double the return of emerging markets stocks, which have been the second-best performer.

Country Annualized Return Cumulative Return
U.S. 15.1% 381%
Emerging Markets 7.5% 199%
Europe 6.9% 189%
U.K. 6.1% 176%
Japan 5.7% 170%
Canada 4.9% 157%


Sources: MSCI, Factset Research Systems

Unsurprisingly, the outperformance of U.S. stocks, reflected in the table below, indicates that the U.S. market currently stands as the most richly valued market as measured by its cyclically-adjusted Price/Earnings Ratio (CAPE).

Country Cyclically Adjusted P/E (CAPE)
U.S. 32.1
Japan 27.2
Canada 22.0
Europe 19.4
U.K. 16.9
Emerging Markets 16.4


Source: www.starcapital.de

Punished for doing the right thing

The spectacular outperformance of the U.S. stock market means that portfolios that have been heavily concentrated in U.S. stocks have generated considerably higher returns than their more diversified counterparts. In other words, investors who have sacrificed diversification in favour of being overweight U.S. stocks have been handsomely rewarded. Continue Reading…

Using arithmetic to crush closet indexers and fee scalpers


by Jeff Weniger, CFA, WisdomTree Investments

Special to the Financial Independence Hub

What is the profile of a fund that has the odds stacked against it?

For starters, “beta” index trackers that cover market capitalization-weighted indexes such as the S&P 500 may often lag their underlying index because of their fees, even though most of their expense ratios are tiny. Nevertheless, such funds may offer a better prospect than many active managers, who can’t get out of the way of their operating costs.

Another fund manager who is against the wall is the “closet indexer”: the career risk manager. These strategists claim to be coming up with great investments, but when you look under the hood, their holdings look just like their competitors’ funds. Then there is the manager who actually has a lot of unique holdings but high fees.

There is a fourth kind of manager who is not a market capitalization-weighted index strategist, a closet indexer or an expensive active manager. They have truly different holdings at digestible fees and higher active share.

To put this in context, a cap-weighted strategy would target an active share figure of 0% because it is trying to be exactly like the S&P 500, MSCI EAFE or some other major index. A closet indexing strategy may clock in at 30% or 40%. One that is totally different, with no holdings in common with its asset class, would have 100% active share.

Now, put active share in the context of fees: Using simple arithmetic, we can calculate the “hurdle rate” — popularized by Martijn Cremers at Notre Dame — which quantifies how well the active selections need to perform to cover their expense ratios. This really matters in picking a fund or ETF.

Path 1 is the worst. Sadly, trillions still sit in closet index funds that have low active share and high fees. Avoid these: Their existence is only justified if they somehow get past High hurdle rates.

Path 2 isn’t much better. These money managers at least have high active share, so they have the courage of their convictions, but they trip over their high fees. Their hurdle rates are Average.

Path 3 is a different breed, but just as bad as Path 2. These managers have low fees because they got the memo that the jig is up on huge expense ratios. But they are still closet indexing, hoping investors won’t notice their low active share. Their hurdle rates are Average.

Path 4 is hard to find. These are strategies that have both high active share and low fees. Their hurdle rates are Low: the sweet spot. Chances are good that a Path 4 fund is an ETF.

I put this in visual form in figure 1.

Figure 1: Visualizing the Four Paths

Find the Low Hurdle
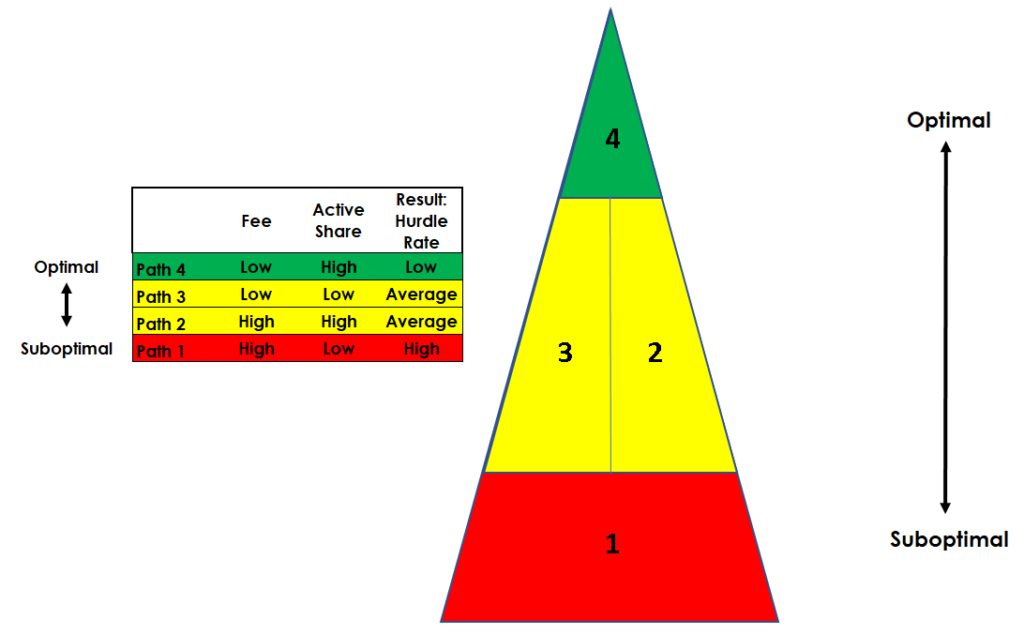
 

Figure 2 puts numbers to this concept, with hypothetical Path 1, 2 and 3 managers.

Start with the Path 1 closet indexer. It has 35% active share, meaning the other 65% of its holdings are found in the cap-weighted benchmark. It charges 0.80%, so the unique holdings need to outperform by 229 basis points (bps) to match the market’s performance. That figure is found by dividing the expense ratio by the active share. It’s a big hurdle rate. Continue Reading…