Building Wealth

For the first 30 or so years of working, saving and investing, you’ll be first in the mode of getting out of the hole (paying down debt), and then building your net worth (that’s wealth accumulation.). But don’t forget, wealth accumulation isn’t the ultimate goal. Decumulation is! (a separate category here at the Hub).

Women, Wealth and Retirement

One of my very first financial planning clients was a single woman in her late 40s named Rachel who lived in Toronto and worked as a self-employed consultant to the not-for-profit sector. She made good money but lacked the confidence to manage her day-to-day finances and save for the long term.

Moreover, Rachel provided care for her aging parents and was under a tremendous amount of stress: enough for her to worry about her own health and whether she could maintain her current workload.

We worked together to establish a budget and cash flow projections for the next 12 months. During that time, we checked in monthly to ensure her income and expenses were on track and updated her plan accordingly.

Having always come from a place of fear about her financial future, Rachel quickly realized the path was not as bad as she once made it out to be. Most importantly, I never made her feel bad for things she didn’t understand: I just offered support and encouragement, along with tools that were easy to understand and implement.

After just one year she felt empowered about her finances and confident about her financial future. This new-found confidence also shone through her consulting business as she managed three straight years of record revenue growth to help further strengthen her financial position.

Meanwhile, her parents’ health continued to decline, so Rachel decided to scale back her workload and spend more time with her mom and dad. Now she only works on enough projects throughout the year to reach a specific annual income target that meets her monthly spending and savings goals. She has enough confidence in her financial plan to turn away other business opportunities to focus on her well-being and spend more time with her parents.

Rachel now joins a growing list of financially well-prepared Canadian women. Earlier this year, RBC Insurance conducted a survey of Canadian women over the age of 45 with household income of $60K+. The survey found that women are relatively well-prepared financially, but still express varying degrees of confidence when it comes to their financial future.

Highlights include:

  • The majority of women over 45 have a very clear idea of what they would do with a sudden lump sum of money, with only a quarter worry about being able to manage the money properly.
  • Canadian women have also mastered the household money matters. More than nine in 10 (92 per cent) agree they have a strong understanding of their finances.
  • Yet despite this, 24 per cent say they won’t be able to maintain their household’s financial situation if their spouse or partner were to pass away and one-third are not confident that they will be able to afford the lifestyle they want to live through retirement.
  • Interestingly, single women were only slightly more likely than married women (36 vs. 34 per cent) to cite a lack of confidence in their ability to afford their lifestyle in retirement.

Retirement planning is a challenge in any household, let alone one in which a spouse dies early. If that spouse happens to be the household’s chief financial officer, what’s the surviving partner to do?

Even though I manage our day-to-day finances and retirement savings I do want my wife to have an understanding of our financial position:  both current and future. I want to set up our finances in a way that’s easy for her to manage in the event of my untimely demise. I also want to ensure that she can maintain a comfortable lifestyle in retirement.

I’ve made sure to include my wife as the beneficiary on my RRSP. That way, if I died, she could have my RRSP assets transferred to her RRSP through a tax-deferred rollover.

I have a term life insurance policy in place that will be enough to pay off our existing mortgage and provide another $300,000 or so to live on.

I also have a defined benefit pension through my current employer. If I died, she would receive 2/3 of the pension I was receiving for the rest of her life.

Annuities: A Missing Piece of the Retirement Puzzle?

The idea of guaranteed income for life is appealing to me as a way to simplify our finances in retirement. Continue Reading…

Why I don’t invest in Canadian Dividend ETFs

By Mark Seed

Special to the Financial Independence Hub

Fans of the My Own Advisor site, including many long-time readers and investors who enjoy this site, continue to tout the benefits of low-cost investing to others.

And you know what? They are right and they should!

That’s because when it comes to investing you often get what you don’t pay for: better returns usually come from a lower-fee fund structure.

That means when it comes to money management fees matter.

One way to reduce your investment fees is to own lower-cost dividend ETFs.

Here are some of the great benefits that come from investing in dividend ETFs beyond just distribution income:

Transparency: Within a few clicks of a mouse or few swipes on my tablet, I can see what every single holding is in these funds. I can also read up on the fund’s prospectus to learn how fund turnover is managed and how often.  Portfolio turnover within the fund costs money: someone needs to get paid!  That brings me to my next point below.

Modest fees: You might recall active fund management costs more because money managers are paid to perform. A pay-for-performance mandate encourages the mutual fund money manager to buy and sell stocks frequently in an attempt to beat the market or the index they are tracking.  Buying and selling frequently incurs costs, and those portfolio costs are passed on to you. Instead of all this trading, I think investors should strive to invest in a low-cost ETF that follows a reputable, established, broad market index such as the S&P/TSX Composite Total Return Index or for dividend investors in Canada, an established dividend-oriented index such as:

• S&P/TSX 60 Index, or

• S&P/TSX Composite High Dividend Index, or

• FTSE Canada High Dividend Yield Index

Lower effort: If you’re going to invest in some individual stocks, you need to spend some time understanding these companies and understanding what you own, why you own it. I read annual reports every year and follow metrics like yield, payout ratio, earnings per share, cash flow to name a few.  Dividend ETFs don’t have this complexity: they bundle all these companies together for you.

There are certainly many benefits to owning Canadian dividend ETFs … but I still don’t invest in any of these Canadian funds.  Here are my reasons why:

1.) I thought about building my own Canadian Dividend ETF: and so I did, and I’ll continue to do so!

Many years ago, I learned there is merit to owning the same Canadian stocks the big funds own: so I started that process.  I’ve never looked back.

I went so far as to say Canadian dividend stock selection could still be made easy.

Here is one quick example: Look at this RBC Canadian Dividend Fund in 2011:

RBC Fund 2011

And now the same fund’s top fund holdings as of April 2017:

RBC Fund 2017

Lots of differences eh?  (Images courtesy of RBC’s site.)

Let’s look at another example and pick on BlackRock – XIU.

Now, again, if you don’t want to buy and hold certain stocks, nor try and create your own Canadian Dividend ETF like I have, then no problem.  This fund is arguably one of the best ETFs to own in Canada!!  (I recall iShares XIU was one of the world’s first ETFs.) Continue Reading…

How a Small Business can maximize Invoice Approval and Accounts Payable

By Darren Wilson

(Sponsored Content)

Accounts payable. Don’t run away yet! Most people don’t like accounts payable or handling invoices. However, they are a necessary evil of any business no matter the industry.

Bills have to be paid after all.

One of the biggest issues companies face with accounts payable is their invoicing process. A slow invoice approval rate can lead to late payments, duplicate invoices, and lost or missing invoices.

Taking time to evaluate and maximize your invoice processing and approval workflow can save not only time but money as well.

Automate wherever possible

One of the best things that a business can do for the accounts payable department is to automate. The benefits of an automated invoicing process seemingly grow by the day.

An automated system reduces the risk of duplicate, lost or missing invoices, as well as providing fraud detection. Where invoices can become misplaced due to trading so many hands, or mistakes could be made during comparisons of shipment orders and invoices because of human error, automation mitigates all of that.

If it’s possible to look to outsource entirely, however, as that may not always be the case, it helps to find similar benefits to automation elsewhere.

Evaluate

Evaluate the current invoice approval and processing workflow for any problem areas. The more transaction and invoice history available the better chance there is of noticing things like invoices that are always late, or get duplicated.

Once the more common and prominent trouble areas have been identified a root cause analysis can be done to determine the cause of the problem. And a solution can begin to develop from there. Continue Reading…

Canadians embracing low-cost ETFs: Is a tipping point on the horizon?

By Dale Roberts, CutTheCrap Investing

Special to the Financial Independence Hub

Data shows that Canadians continue to embrace low-cost ETFs. That said, more monies continue to flow into high-fee mutual funds. As you likely know, Canadians pay the highest mutual fund fees in the developed world. Of course, those high fees are wealth destroyers and can eat up 50% of your investment returns over the decades.

But here’s the good news: more Canadians are moving more monies to low-cost ETF portfolios by the way of self-directing or through Canadian Robo Advisors or by way of those One Ticket Asset Allocation Portfolios.

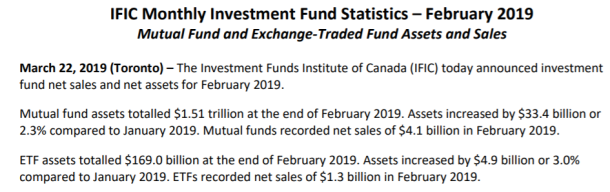
Here’s a look at the flow comparisons for Mutual Funds and ETFs courtesy of the IFIC site:

Here’s the sales figures for mutual funds in what we would typically call the usually robust RRSP season, January and February:

Mutual Fund Sales 2019 Jan FebAnd here’s the sales figures for the ETF industry for RRSP season:ETF Assets 2019 Jan Feb

If we want to be optimists, that is more than promising. While 2019 was a soft RRSP season for money flows into mutual funds and ETFs (compared to 2018 figures) there was an acceleration of flows to ETFs compared to mutual funds, year over year.

  • In 2019 35% of new monies went to ETFs.
  • In 2018 27% of new monies went to ETFs

That is certainly something to celebrate. While the total mutual fund industry is almost 10 times the size of the ETF industry, they did not even double the size of inflows for January and February of 2019. That aligns with the findings of Nest Wealth, which conducted a poll in RRSP season. Respondents suggested one third of all new account openings would be by way of one of the Canadian Robo Advisors: also known as digital wealth managers. For more on that please have a read of There will be a tipping point for ‘Robo Advisors’ suggests Randy Cass of Nest Wealth. Keep in mind the poll was reading account openings, not the move of assets or amounts of assets.

Here’s another way to frame that more than ‘good news’. Continue Reading…

Paying taxes on capital gains could be the best decision you make this year

When it comes to capital gains taxes, sometimes it pays investors to give Ottawa its due (Shutterstock)

Marc Bellefeuille, Manulife Wealth

Special to the Financial Independence Hub

In times of market volatility, anything can happen from one quarter to the next. Market participants witnessed a wipeout in the financial markets in Q4 of 2018. The S&P 500 saw its fortunes accumulated throughout the year evaporate from September to November and American stocks suffered the worst declines ever recorded on a December 24thtrading day. Other markets around the world followed suit.

Fast forwarding to Q1 of 2019, the bounce-back for equity markets has been nothing short of impressive. So what can investors take away from the last six months? Certainly, many investors may have questioned those who advise them at the end of 2018, only to be rewarded for having stayed the course in recent months. But what lessons can we learn from recent events, and how should we adjust to protect our precious nest eggs in the years to come?

In the famous paper by Brison, Hood and Beebower, “Determinants of Portfolio Performance,” the authors suggest that a whopping 93.6% of portfolio return volatility is explained by the asset allocation of the investment portfolio1. Nobel prize-winning economist Harry Markowitz called diversification “the only free lunch in finance.”

Yet, more often than not, I see portfolios of bright and capable people concentrated in a few specific positions. The culprit? Capital gains tax. Investors feel at ease by the value they see on their quarterly statements and often feel like they are playing with house money so they can justify letting their portfolios drift into a state of concentration of their winners. The idea of paying the taxman keeps them from rationally re-balancing their portfolios which, ironically, can expose them to large shocks during market corrections.

The average market drop in a recessionary bear market is 30.4%.2These kinds of drops often take place without warning – and certainly without mercy – and can drag every sector down with them. These declines can often be more severe to high net-worth investors due to under-diversification of their investments.3

Most high net-worth investors know they should follow a diversified portfolio strategy. However, knowing is only half the battle. Many, when asked, could not explain their strategy for selling positions within their investment portfolios. When pressed, many investors believe that, for any position that declined by more than 10%, they would advocate to hit the sell button and stop the loss. But when a position was up 10% or more the button was harder to push: the greater the gain the harder it gets to take the profits. Investors tend to be loss averse but when they are, in their minds, playing with house money the rules go out the window and many sit on large gains without re-balancing back to their strategic asset allocation.4

Better off taking profits and rebalancing

One of the impediments to profit taking is the tax bill. Let’s do the math. Assume a successful investor put half a million into the shares of one of the big five Canadian banks in the fall of 2008 and the stock doubled. Were they to sell those shares, as a resident of Ontario, the tax bill would be approximately $133,800: assuming the top marginal tax bracket. Continue Reading…