Building Wealth

For the first 30 or so years of working, saving and investing, you’ll be first in the mode of getting out of the hole (paying down debt), and then building your net worth (that’s wealth accumulation.). But don’t forget, wealth accumulation isn’t the ultimate goal. Decumulation is! (a separate category here at the Hub).

Is typical retirement advice good? – Testing popular Retirement rules of thumb

Special to the Financial Independence Hub 

You want to retire soon. How should you set up your retirement income?

You talk with some friends, read about it on the internet, and talk with a financial advisor. Are you actually getting good advice?

When it comes to retirement income, most financial advisors rely on a few rules of thumb handed down from one generation of advisors to the next. The rules appear to be common sense and are usually accepted without question.

Do these rules of thumb actually work?

Before giving clients this advice, I tested them with 150 years’ history of stocks, bonds and inflation. I wanted to see if these rules were reliable for a typical 30-year retirement. (The average retirement age is 62. In 50% of couples that reach their 60s, one of them makes it to age 92.) 

These five rules are the “conventional wisdom” – the advice typically given to seniors:

  1. “4% Rule”: You can safely withdraw 4% of your investments and increase it by inflation for the rest of your life. For example, $40,000 per year from a $1 million portfolio.
  2. “Age Rule”: Your age is the percentage of bonds you should have. For example, at age 70, you should have 70% in bonds and 30% in stocks.
  3. “Sequence of returns”: Invest conservatively because you can’t afford to take a loss. You can run out of money because of the “sequence of returns.” You can’t recover from investment losses early in your retirement.
  4. Don’t touch your principal. Try to live off the interest.
  5. Cash buffer: Keep cash equal to 2 years’ income to draw on when your investments are down.

The results: NONE of these rules of thumb are reliable, based on history.

Let’s look at each to understand this.

1.) “4% Rule”: Can you safely withdraw 4% of your investments plus inflation for the rest of your life?

Based on history, the “4% Rule” was safe for equity-focused investors, but not for most seniors.

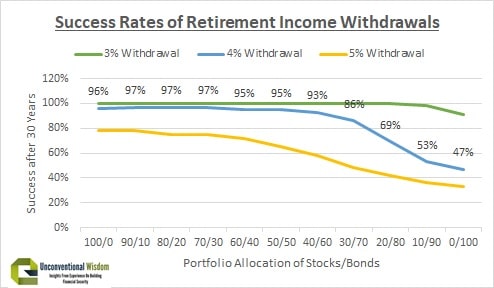
In the results shown in the graphic at the top of this blog, the blue line is the “4% Rule,” showing how often in the last 150 years a 4% withdrawal plus inflation provided a reliable income for 30 years.

The “4% Rule” only works with at least 50% in stocks.

The “4% Rule” worked only if you invest with a minimum of 50% in stocks. Even safer is 70-100% in stocks. It is best to avoid a success rate below 95% or 97%. They mean a 1 in 20 or 1 in 30 chance of running out of money during your retirement.

Most seniors invest more conservatively than this and the 4% Rule failed miserably for them.

A “3% Rule” has been reliable in history, but means you only get $30,000 per year plus inflation from a $1 million portfolio, instead of $40,000 per year.

These results are counter-intuitive. The more you invest in stocks, the safer your retirement income would have been in history.

To understand this, it is important to understand that stocks are risky short-term, but reliable long-term. Bonds are reliable short-term, but risky long-term. Why? Bonds get killed by inflation or rising interest rates. If either happens during your retirement, you can easily run out of money with bonds.

The chart below illustrates this clearly. It shows the standard deviation (measure of risk) of stocks, bonds and cash over various time periods in the last 200 years. Note that stocks are much riskier short-term, but actually lower risk for periods of time longer than 20 years.

Stocks are more reliable after inflation than bonds after 20 years.

Ed’s advice: Replace the “4% Rule” with “2.5% +.2% for every 10% in stocks Rule.”  For example, with 10% in stocks, use a “2.7% Rule.” If you invest 70% or more in stocks, then the “4% Rule is safe.

2.) “Age Rule”: Your age is the percentage of bonds you should have. For example, at age 70, you should have 70% in bonds and 30% in stocks.

Continue Reading…

Is it too late to invest in Canadian marijuana stocks?

Canadian marijuana stocks may move higher on momentum as the Oct. 17, 2018 date for legalization approaches, but they need significant revenue growth to justify their huge market caps.

Share prices for many Canadian marijuana stocks have soared since mid-2016. The speculative appeal of marijuana stocks continues to attract investors looking for a “ground-floor opportunity.” However, the pioneers in an industry are not always the ones who survive.

Canadian marijuana stocks need more revenue growth

The barriers to entry are low for new competitors in Canadian marijuana stocks. If demand rises rapidly, tobacco companies and other big producers will likely enter the market.

Canadian marijuana stocks may move higher on momentum — but they need significant revenue growth to justify their huge market caps (the value of all shares outstanding).

A new crop of penny stocks are sprouting

Now that marijuana stocks have proven popular with investors and have given them big returns, investors looking to add to the aggressive portion of their portfolios may turn to the higher-risk strategy of buying speculative marijuana penny stocks.

However, there are several potential risks when investors venture into penny stocks in general.

Buying low-quality Canadian penny stocks is one of those things that can appear to be successful before it goes wrong. Some get hooked on it, since low-quality stocks can be highly profitable over short periods. That’s because they are generally more volatile than high-quality stocks.

Avoid ‘pot-of-gold’ stocks if you invest in Canadian marijuana

Penny stocks can attract investors with their low prices and promises of high returns when they pay off. Yet the odds against success are very high with these speculative stocks. And they can provide fertile ground for stock promotions and investing scams. Penny stocks can be more easily manipulated than most stocks because of thin trading and price volatility. Continue Reading…

The Case for Financial Assets over real estate

Billy kicking back on Mexico’s Pacific Coast

By Billy Kaderli

Special to the Financial Independence Hub

When I was a stock broker in California — one of the hottest housing markets in the US — real-estate was my competition. “Everyone” was making money in real-estate, so why would they invest in the stock market?

I needed an angle

I went to the Board of Realtors and got prices for 2-, 3- and 4-bedroom homes in the area, both at the current price and for 10 years prior. I did the math to calculate what annual return these houses were creating for that ten-year span, then compared that to the S&P 500 Index for the same time period.

The index clearly beat all three home styles without the hassles of ownership. Now I had my argument to help people invest in the market.

Ok, that was then and this is now

Using Zillow.com I looked up what the home we used to own was now worth. It was listed at US$862K. Again I did the math and found that over the last 31 years since we bought it, that house has appreciated 6.4% annually. Sounds OK, except that there were property taxes, maintenance and repairs that would need to be deducted lowering that annual return.

Then, I wondered, what if we had put the money to buy our home into the S&P 500? So I calculated that figure also.

Are you ready?

It would be worth 3 million (US) dollars today! Over three times the current value of the home, as the Index produced a 10.46% annual return during those 31 years. Continue Reading…

How dividends are taxed: a close look at the dividend tax credit

Discover what you need to know to answer the question, “How are dividends taxed in Canada?”

Taxpayers who hold Canadian dividend-paying stocks get a tax break. Their dividends can be eligible for the dividend tax credit in Canada. This means that dividend income will be taxed at a lower rate than the same amount of interest income.

Investors in the highest tax bracket pay tax of 29% on dividends, compared to about 50% on interest income. Investors in the highest tax bracket pay tax on capital gains at a rate of roughly 25%.

As mentioned, Canadian taxpayers who hold Canadian dividend stocks get a special bonus. Their dividends can be eligible for the dividend tax credit in Canada. This dividend tax credit — which is available on dividends paid on Canadian stocks held outside of an RRSP, RRIF or TFSA — will cut your effective tax rate.

This means that dividend income will be taxed at a lower rate than the same amount of interest income.

How are dividends taxed in Canada? An example:

If you earn $1,000 in dividend income and are in the top 50% tax bracket, you will pay about $290 in taxes.

That’s a bit more than capital gains, which offer tax-advantaged income as well. On that same $1,000 in income, you will only pay $250 in capital gains taxes.

But it’s a lot better than the roughly $500 in income taxes you’ll pay on the same $1,000 amount of interest income.

The Canadian dividend tax credit is actually split between two tax credits. One is a provincial dividend tax credit and the other is a federal dividend tax credit. The provincial tax credit varies depending on where you live in Canada.

Note that apart from the Canadian dividend tax credit giving you a major tax-deferral opportunity, dividends can supply a big part of your overall long-term portfolio gains.

When you add in the security of stocks with dividends going back many years or decades—plus the potential for tax-advantaged capital gains on top of dividend income: Canadian dividend stocks are an attractive way to increase profit with less risk.

How are dividends taxed in Canada? Savvy investors respect the advantages of dividends

Dividends don’t always get the respect they deserve, especially from beginning investors. Continue Reading…

Why the “T” in TSX should stand for Tokyo

By Jeff Weniger, CFA, WisdomTree Investments

Special to the Financial Independence Hub


Canada’s stock market construction may be more than just a portfolio risk; it is arguably a systemic one.

If, for whatever reason, the Canadian financial system were to encounter serious difficulty, investors would be hit by a one-two punch. The attendant economic weakness would hang over the stock market, and it would be the very companies that dominate the stock market that would be battling demons. Canada’s top-heaviness, where more than $2 of every $5 in the MSCI Canada Index is in financial stocks, is not normal or reassuring for a developed economy.1 We should stop making like it is.

In fact, it would be better for the TSX if the “T” stood for Tokyo, at least on the sector diversification side of things, as we show below.

Stuck in the mud

Everywhere you turn, countries that are top heavy are doing something about it. Saudi Arabia, for example, sees the writing on the wall for fossil fuels; either the price mechanism may cause a phase-down in oil demand in the next quarter century, or environmental action groups will crush demand themselves. Either way, the ruling Crown Prince Mohammad bin Salman is keen to avoid state failure if a bleak future for oil comes to pass. That country will soon float an IPO of Aramco, the state-run oil behemoth that may be equal to several ExxonMobils. Proceeds will be diverted into tech, infrastructure—anything that isn’t oil.

China, too, realized it was turning into a one-trick pony. After building its export machine after Mao’s death, the time for middle-class demand eventually arrived. When it joined the WTO at the turn of the century, the country’s household consumption was 46% of GDP. It fell to 36% of GDP in 2007, but it has been rising ever since; sights are set on 40% this year.2

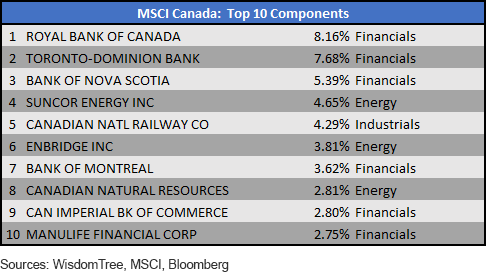
But not Canada. The hat is hung on the same two sectors, as always. Nine of this country’s top 10 corporations by market capitalization fit the bill (figure 1). This, in a country where the average investor has 86% of assets inside these borders.3

That is concentration on top of concentration.

Figure 1: Canada’s Sector Concentrations

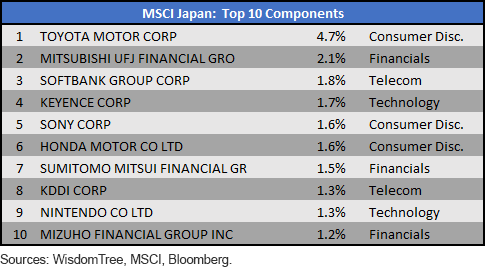
Compare the “T” for Toronto with another T: Tokyo. Figure 2 shows Japan’s national champions. They don’t dominate allocations quite like Canada’s do.

Figure 2: Japan’s Largest Companies

Continue Reading…