Building Wealth

For the first 30 or so years of working, saving and investing, you’ll be first in the mode of getting out of the hole (paying down debt), and then building your net worth (that’s wealth accumulation.). But don’t forget, wealth accumulation isn’t the ultimate goal. Decumulation is! (a separate category here at the Hub).

A Millennial’s Jump Start on Personal Finance

By Trevor McDonald

Special to the Financial Independence Hub

Most millennials aren’t taught personal finance beyond the few who soaked up “lessons” from having an allowance or chores while growing up. Given the increasing use of digital currency, from tapping phones together to send money, depending on Venmo and utilizing bitcoins, ask a millennial how to write a check or balance a bank account and few can give a succinct answer: but does that even matter? Has personal finance changed so much in the past few decades that its definition is due for an overhaul?

Financial literacy and well-being is and always will be vital. How it’s defined and its best practices evolve as we do. Just like any type of “health,” financial health requires setting a strong foundation, teaching and practice. It’s strange that we have an entire generation in full-fledged adult categories without a clue of how to handle their finances.

Consider this the starter kit for millennials:

1.) Credit score management

 The importance of credit scores isn’t going anywhere. In fact, they’re more important than ever with some employers using credit scores to narrow down job candidates. Make sure to monitor your credit score, check your credit report regularly for errors, and make your payments on time. This will help ensure you maintain a healthy score. There are other ways improve your credit score that you might not know, too, such as snagging a tradeline where you’re added onto a person’s credit account who already has a solid score. A tradeline company can manage this, linking paying customers to a tradeline account so any messiness of blending finances with personal relationships is avoided.

2.) Buffering that nest egg

Having at least three months’ worth of living expenses in “liquid cash” that’s easily accessible is a reasonable starting point. Some financial experts recommend one year, but a year’s salary can sound very overwhelming. Start socking away funds in an emergency account by using an app that rounds up purchases and siphons funds to this account so you don’t even notice.

3.) If possible, entrepreneurs and business owners should seek out life in specific states or overseas

Millennials are the generation of entrepreneurs, and this makes personal finance even stickier. Where you live plays a huge role in your ability to build wealth. Obviously some regions have higher costs of living than others, but every state also has a different income tax. There are seven states, including highly desirable ones like Florida, that boast a zero per cent income tax rate. Moving abroad often allows for foreign earned income exemption in which you don’t pay any state income tax (of course) but also no federal taxes except social security and Medicare.

4.) Budget, budget, budget

Continue Reading…

Business owners need to step up Wealth transfer plans for next generation

Here’s my latest High Net Worth blog for the Financial Post, titled Only 40% of new business owners have transition in place, says new report.

The latest in a series of global surveys by RBC Wealth Management and Scorpio Partnership finds that while more than a third of business owners in the United States, Canada and the United Kingdom  have a full formal plan in place to pass their wealth on to their heirs, one in five have not even started to plan.

RBC surveyed 384 high-net-worth and ultra-high-net-worth individuals in the three countries, with average investible wealth of US$6.4 million. While 51% of business owners have a will in place, a startling 22% have not yet started any sort of wealth transfer preparations; which means “the majority of business owners are relatively unprepared to pass on their financial legacy,” the report says.

One of the experts I consulted was business transition and valuation expert Ian R. Campbell, who  recently wrote a Hub blog about Donald Trump’s business transition plans for his high-profile family members. It was also the basis for an earlier Financial Post column by me headlined Donald Trump is upping the ante in the Wealth Transfer game.

Continue Reading…

As “new” China economy stabilizes, markets poised for upside surprise

By Dwarka Lakhan (Sponsored Content)

There is growing optimism that the Chinese markets will surprise on the upside as government reforms begin to take hold.

Since the beginning of the year, the country’s macro-economy has stabilized, fuelled by strengthening industrial output, an expanding service sector, rising retail sales, steady growth in electricity generation, power consumption and rail volume, and robust domestic demand.

Valuations are currently quite attractive, following a significant correction in China’s onshore markets from their 2015 highs. Non-financial blue chip companies are presently trading at an average of 15-20 times price/earnings ratio, below their historical highs.

Upside surprise waiting, Barclays says

Recognizing the potential for investors to make gains in China, Barclays Capital recently noted that there is an upside surprise waiting in the wings for China investors. “We think the latest data from China point to continued robust growth,” says Jian Chang of Barclays in Hong Kong.

The resurgence of optimism over China stems from the “new” China economy picking up steam on the back of reform-oriented government policies that are represented by the deliberate shift in focus from export-led to domestic-generated growth.

Continue Reading…

Weekly Wrap: Census; Estate planning; Trump’s succession plan; Mutual Funds embrace ETFs

Based on the widespread media coverage of the 2016 Canadian census this week, Canada’s baby boomers are going to be just as much of a demographic force as ever once they enter their golden years. For the first time, our seniors now outnumber our kids, the CBC reported.

Not all seniors are baby boomers, of course, but sadly the reverse will soon be true: most if not all baby boomers will be seniors. For this generation retirement (or semi-retirement) is a huge looming event, as a quick browse of this site will establish. Hey, just this week I got a package from Service Canada advising me that I will be able to draw Old Age Security (OAS) when I turn 65 next April. And I intend to take it then too, as I wrote in MoneySense last August: Why I’m taking OAS right at 65.

Boomers need to face up to their own mortality

All of which suggests it’s time for Canadian boomers to start looking more seriously at their own mortality and the admittedly dreary topic of estate planning. I covered this Thursday in my latest MoneySense Retired Money column: Retirees need to start thinking ahead.

In my Financial Post article that ran on Wednesday, I looked at estate planning from a different perspective: how the original “Wealthy Boomer” —  Donald Trump —  is tapping his family members for senior roles in his administration and possibly for his business succession planning. Click on Donald Trump is upping the ante in the Wealth Transfer game.

Ian Campbell

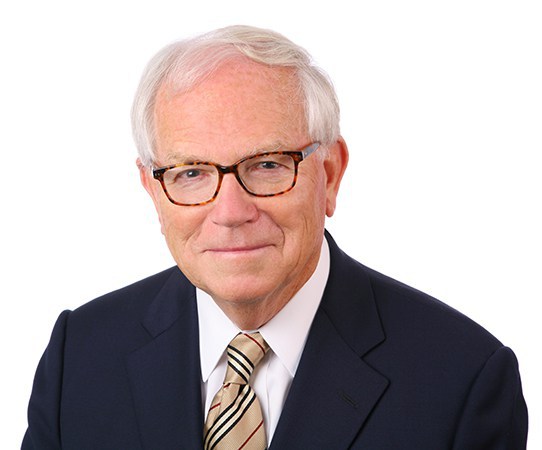
One of the sources for the FP piece was business transition and valuation expert Ian Campbell, pictured. (He himself admits to his strong resemblance to investing legend Warren Buffett!). By coincidence I reached out to Ian about the Trump piece just as he had published a blog on that very topic. It ran on the Hub Wednesday under the headline Generational Business Transaction: The Apprentice. Check the links to his site for his free newsletter.

The Truth about Working in Retirement

Our best-selling (G&M, Amazon among others) book, Victory Lap Retirement, continues to get some positive reviews. Earlier this week Ellen Roseman of Toronto Star fame wrote the following review on Golden Girl Finance: The Truth about Working in Retirement. As Ellen recounts, she herself has retired from her full-time newspaper gig but continues to be fairly busy in the semi-retirement described in our book.

Mutual fund companies Excel Funds, Franklin Templeton enter ETF business

Finally, some big news in the asset management industry, where it was announced that two Canadian mutual fund companies — Excel Funds Management and Franklin Templeton Investments — are entering the ETF business. The Globe & Mail’s Clare O’Hara reported this on May 2nd. Click on Franklin Templeton, Excel Funds to enter Canadian ETF market.

Continue Reading…

How to profit from the Domain Name business

By Katrina Manning

Special to the Financial Independence Hub

We’ve all heard of domain names purchased 10 years ago for $10 dollars and selling for $20 million today — or some other story of similar nature.  As a result, you might be interested in buying and selling domain names either full-or-part-time for profit. It seems so easy and simple: just pick the right domain name, hold on to it for a while then sell for profit.

But is it really that simple? Well, since everyone is online –you can imagine that the ocean is wide. And you don’t want to start with a bit of research. You need a map, and we’ve created one for you here.

Stay focused

There are millions of domains already registered, especially the easiest ones that consist of one word such as apple.com, Facebook.com and so on. On the other hand, there are countless combinations of available domain names to register, especially if you consider the thousands of new domain name extensions such as .ng domain or .eu domain names.

As you can see, it is critical to keep your focus narrow. What subjects are you already familiar with, which can make the process much simpler? Do you have experience with animals or tech? Have you worked in the entertainment or service industry? Think about the industries you are most familiar with first, and start with that. Why is this important? Well, you don’t want to target prospective buyers based on their potential for sales if you don’t have insight into the industry you are aiming at.

In other words, don’t just rush to buy multiple domain names you think would appeal to health care clinics you’ve identified as potential buyers. You might not be aware of any industry-specific rules that govern facets of legal advertising. You won’t make much of a profit, if any, if you buy domain names your target audience can’t use. This is where it pays off to take the time to understand your audience.

Take the time needed to learn

Continue Reading…