Building Wealth

For the first 30 or so years of working, saving and investing, you’ll be first in the mode of getting out of the hole (paying down debt), and then building your net worth (that’s wealth accumulation.). But don’t forget, wealth accumulation isn’t the ultimate goal. Decumulation is! (a separate category here at the Hub).

How to create financial sustainability for yourself

Billy & Akaisha Kaderli, RetireEarlyLifestyle.com

By Billy and Akaisha Kaderli, RetireEarlyLifestyle.com

Special to the Financial Independence Hub

These days, no matter what the topic, the talk is all about sustainability.

In regards to financial sustainability, there are three legs to the stool: income, spending and Investments.

1.) Income

Income is derived from money you make through your job using physical or mental labor or both. Passive income can be created through property rentals, bond interest, dividends and or capital gains from investments.

Increasing income can be done by learning a new skill, getting a promotion, or taking on a better or second job. Maximizing your skills and continued education either formal or on your own is a valuable asset. This could be as easy as teaching yourself about investments in your down time. There are plenty of online tools available to learn this.

Also, don’t rule out that Social Security [or in Canada, CPP and OAS] will be available once you become eligible.

2.) Spending

How much you spend and the debt you carry are two areas that are completely manageable by you. The categories of largest spending in any household are housing, transport, taxes and food/entertainment. Depending where you live, it may make more sense to rent instead of buying a home, or rent out a room in the home you already own, or rent out a subsection of your home in order to help with the mortgage. Putting off that remodel of the bathroom or kitchen, or the re-do of the back yard will also allow you extra money to put into investments.

Regarding transportation, you could walk or bicycle to work, take public transportation instead of owning your own vehicle, car pool or use Uber or a ride sharing service. The cost of car ownership is over $8,000 per year, roughly $650 per month, or $22 per day according to AAA’s 2016 Your Driving Cost Study. How much of your day is spent covering your car expenses, which according to Fortune is parked 95% of the time?

Continue Reading…

Target-date funds hold hidden risks and conflicts of interest

Target-date funds are sold as offering great benefits for investors, but we don’t think you should accept the sales pitch.

Target-date funds go against one of TSI Network’s cardinal rules of successful investing. That is to invest mainly in simple, plain-vanilla investments. This rule limits your choices to two main categories: stocks and bonds (or ETFs that hold those investments). By confining yourself to these two investment categories, you still have all the investment choices you need. You also avoid the hidden risks and conflicts of interest that you’ll find in more complex products.

Target-date funds are mutual funds that take advantage of the widely held view that bonds are inherently safer than stocks, so you should gradually shift your investments out of stocks and into bonds as you near retirement. Target date funds do this for you automatically.

Complexity is not a benefit

The funny thing is that the promoters of complex investments describe the features of these investments as if they were benefits, disregarding the associated negatives. This marketing approach attracts investors who want to make a quick decision. These investors tend to accept the sales pitch at face value.

Continue Reading…

House shopping for Millennials

By Barney Whistance

Special to the Financial Independence Hub

In the wake of a new generation now growing up and planning to settle down, one of the biggest concerns for them is finding a place to live. Finding a house for you and your spouse to live in is one of the most important decisions that you will have to take. Therefore, it should not be taken lightly. There are a lot of factors for you to consider when you set out to purchase or get a house on mortgage.  You have to be certain about your choice as you will be the one living with it for a major part of your life.

Your financial situation is the biggest aspect you have to consider when making a decision like that. Once you know your financial point and how much you can afford, you must decide on where you want to live.  Planning everything step by step always gets the work done more smoothly and also makes your choice easier.

Finances

Talk about your finances with your partner, so in order to set a budget, you already know how much you both have. Once you have done the initial financial scrutiny, you can decide which plan you should be applying for. Continue Reading…

Baby sitting & RRSPs: a 9-year old’s rules for when to TFSA

9-year old Carlie Weinreb lectures financial bloggers on when to use TFSA or RRSP

By Carlie Weinreb

Special to the Financial Independence Hub

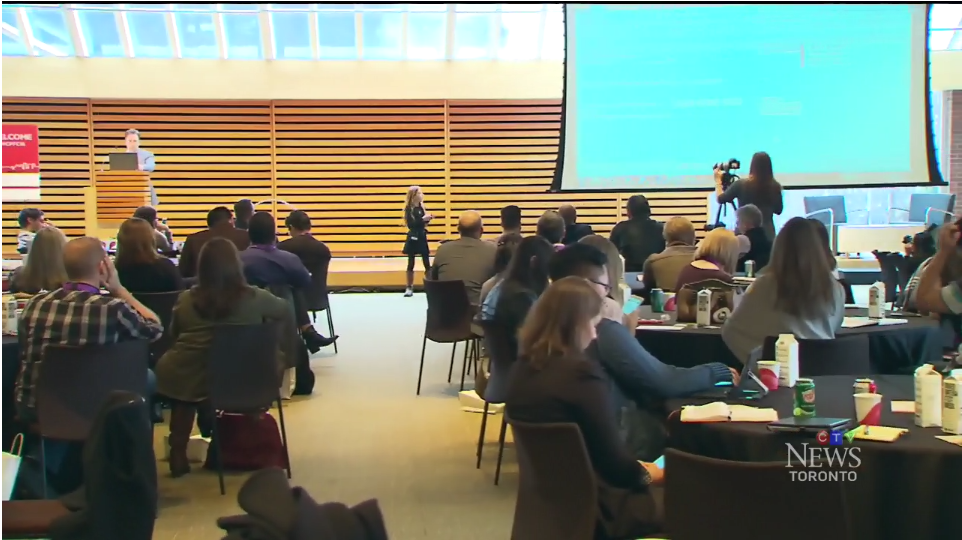
I lectured about RRSPs and TFSAs this November 3rd at the CPA Mastering for Money Conference for 45 minutes. I was a bit nervous because I knew that Former Prime Minister Paul Martin was also speaking. My example was very detailed with lots of Excel spreadsheets.

I then had a sleepover at my friends house the next weekend after dance class. My friend’s parents heard I lectured to over 400 Chartered Professional Accountants about RRSPs and TFSAs. They asked “OK what’s better?” I said “Well, it depends on your income and a couple of other things.” I knew they were not satisfied. I could tell they wanted like a 15 second answer.

The following week I was lecturing at the Canadian Personal Finance Conference presenting on RRSP and TFSAs again but they gave me only 20 minutes. And most recently, I presented on RRSPs versus TFSAs at Microsoft. They only gave me ten minutes.

3 quick rules

Continue Reading…

4 sensible financial literacy books as gift suggestions

Santa Clause putting a shiny Christmas present into a stocking. Isolated on white.Want to give the gift of financial literacy to a loved one this Christmas?

We have a few stocking stuffer ideas,  following the just-completed Financial Literacy Month in Canada. Throughout November,  there were lots of articles out there on the importance of financial literacy and even more opinions about how to improve it.

Some argue for it to be taught in schools:  aren’t our schools stretched enough for resources as it is?  Some say parents should make it a priority to teach their children about money but many parents struggle with money concepts themselves and “do as I say, not as I do” isn’t always convincing.  Many argue very credibly that the financial services industry in Canada generally works to separate people from their money rather than to educate them about how to best grow their money.

We’re not sure what the answer is but agree it’s an important subject.  If you’ve already read David Chilton’s The Wealthy Barber and are ready to move on to the next step, here are a few investment books that are sensible and concise.

*We first published this list in February 2015 and have received positive feedback!

1) The Investment Answer – Daniel Goldie and Gordon S. Murray – 2011
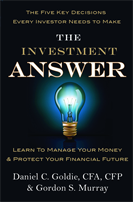
The Investment Answer – Daniel Goldie and Gordon S. Murray – 2011

Publisher summary:

“What if there were a way to cut through all the financial mumbo-jumbo? Wouldn’t it be great if someone could really explain to us–in plain and simple English–the basics we must know about investing in order to insure our financial freedom? At last, here’s good news. Jargon-free and written for all investors–experienced, beginner, and everyone in between–The Investment Answer distills the process into just five decisions–five straightforward choices that can lead to safe and sound ways to manage your money.”

2) The Little Book of Common Sense Investing: The Only Way to Guarantee Your Fair Share of Stock Market Returns – John C. Bogle – 2007
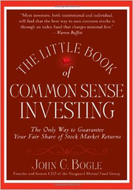
The Little Book of Common Sense Investing- The Only Way to Guarantee Your Fair Share of Stock Market Returns – John C. Bogle – 2007

Publisher summary:

“Investing is all about common sense. Owning a diversified portfolio of stocks and holding it for the long term is a winner’s game. Trying to beat the stock market is theoretically a zero-sum game (for every winner, there must be a loser), but after the substantial costs of investing are deducted, it becomes a loser’s game. Common sense tells us-and history confirms-that the simplest and most efficient investment strategy is to buy and hold all of the nation’s publicly held businesses at very low cost. The classic index fund that owns this market portfolio is the only investment that guarantees you with your fair share of stock market returns. To learn how to make index investing work for you, there’s no better mentor than legendary mutual fund industry veteran John C. Bogle.”

3) The Empowered Investor: A Canadian Guide to Building a Better Investment Experience – Keith Matthews – 2013
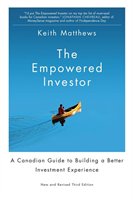
The Empowered Investor- A Canadian Guide to Building a Better Investment Experience – Keith Matthews – 2013

Publisher summary:

“With The Empowered Investor: A Canadian Guide to Building a Better Investment Experience, author and advisor Keith Matthews answers the call for a clear, intelligent guide for Canadians looking to invest wisely. Dispensing with jargon and hype, The Empowered Investor is an easy-to-read finance and portfolio management book that offers a down-to-earth treatment of a complex subject with an accessible style that will appeal to novices and experts alike.”


4) Exchange Traded Funds for Canadians for Dummies – Russell Wild and Bryan Borzykowski – 2013
Exchange Traded Funds for Canadians for Dummies – Russell Wild and Bryan Borzykowski – 2013

Publisher summary:

“The fast and easy way for Canadians to understand and invest in ETFs – Exchange-traded funds (ETFs) are an increasingly popular part of the investing landscape, being less volatile than individual stocks, cheaper than most mutual funds, and subject to minimal taxation. But how do you use this financial product to diversify your investments in today’s ever-changing market?

Exchange-Traded Funds For Canadians For Dummies shows you in plain English how to weigh your options and pick the ETF that’s right for you. It tells Canadian investors everything you need to know about building a lean, mean portfolio and optimizing your profits. Plus, the book covers all of the newest ETF products, providers, and strategies, as well as Commodity ETFs, Style ETFs, Country ETFs, and Inverse ETFs. The only book on the market catering specifically to Canadian investors.”

5 more suggestions

Editor’s Note: For a list of  5 more financial book suggestions, read this article from Saturday’s Financial Post: Here’s a look back at some of the best personal finance and economics books of 2016.

graham-bodelGraham Bodel is the founder and director of a new fee-only financial planning and portfolio management firm based in Vancouver, BC., Chalten Fee-Only Advisors Ltd. This blog is republished with permission: the original ran November 29th here.