For the first 30 or so years of working, saving and investing, you’ll be first in the mode of getting out of the hole (paying down debt), and then building your net worth (that’s wealth accumulation.). But don’t forget, wealth accumulation isn’t the ultimate goal. Decumulation is! (a separate category here at the Hub).
Our current concept of retirement is relatively new. Past generations had no idea what it meant not to work. They stopped only when they physically had to.
Here’s an interesting tidbit – in 1890, nearly everyone died while still employed, and if they were healthy enough not to expire on the job, they retired at age 85.
Boomer parents were retirement pioneers.
The retirement age of 65 was first set in Germany in 1916, adopted by the U.S. in 1935, and in Canada shortly thereafter. It was probably the advent of CPP and OAS benefits that created the mindset to retire at age 65. Then came the lure of Freedom 55 and people were led to believe that 55 was a reasonable retirement age.
Advisors spend a great deal of their time with clients who ask, “Will I run out of money?” As a result, few issues get more attention than the sustainable withdrawal rate in today’s environment.
But new research shows that an equally pressing question is, “How can I enjoy life in my 60s, before health issues creep in?”
“And you will know the truth, and the truth will set you free.” — John 8:32
As I begin my 32nd year in and around the financial arena and soon shall celebrate my 59th entrance onto the stage of one of the magnificent creations of the Master of the Universe, this former Wall Street Whiz Kid (who doesn’t deserve to be called a whiz kid after making and losing millions more than once) has never been more concerned about the economic, social, political and spiritual state of the U.S.A.
While it was nice to receive accolades over the years for forecasting many major tops and bottoms in several different markets, I thankfully concluded no one except Almighty God knows the future and portraying oneself as some soothsayer is an insult to Him and mankind. (Not being able to hit the side of the barn in the last few years as a Soothsayer had something to do with it, also.)
So my comments here are that of just a private citizen, speaking aloud and still caring about this thing called the human race.
My first boss and the man who gave me my start as a stockbroker back in April 1984, said to me on my first day in the office (I think only half in jest), “Peter, don’t do three things if you want to be successful in this business. Don’t talk about politics, religion and other men’s wives.”
While I still believe he was joking about wives, he was deadly serious about politics and religion. The underlying theme of his message was, “sell products, not personal opinions.” Continue Reading…
Here’s an interesting development in the general field of discount brokers, ETF makers and robo advisers.
Last November, Questrade Wealth Management Inc. (QWM, a subsidiary off Questrade Financial Group Inc.) launched an “online wealth management” service called Portfolio IQ that bears a strong resemblance to so-called “robo” advisers.
A fact sheet bearing the slogan “Wealth Management isn’t just for the Wealthy anymore” described Portfolio IQ as “an online wealth management service” delivering professionally and actively managed portfolios at an ultra-low cost. It promised customized portfolios for those with as little as $2,000.
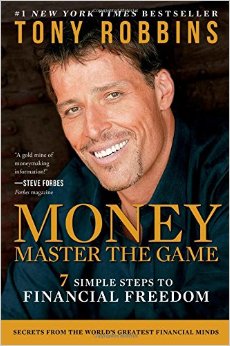
We’ve been reviewing books about financial independence here at the Hub since our launch early in November 2014 and long before that at FindependenceDay.com, as well as the Financial Post, MoneySense and Maclean’s. Up until now, the books reviewed on this site have been read and reviewed by me. But it’s almost impossible to read everything, even if the focus is as narrow as financial independence and the author is someone as prominent as Tony Robbins. So starting with this guest post, we’re going to widen the net with this review of Robbins’ new book by Tea at Taxevity’s Promod Sharma. We will certainly consider reviews of other financial books by objective sources. If you’re an author looking to be reviewed and willing to supply a review copy of your book, contact me at jonathan@findependencehub.com. If you’d like to try reviewing other books at the Hub, contact me at the same email. As for the review of the new Robbins book, you can find the original review on Promod’s site here. You also can find two interviews Promod conducted with me over at Findependence.TV, before and after the site launch. Over to Promod! — Jonathan Chevreau
–
–
Promod Sharma
By Promod Sharma,
Special to Financial Independence Hub
There are many reasons to read a book about money and there are lots of books about money. Tony Robbins has a new one, Money: Master The Game. Unfortunately, not many people read books. Even fewer read nonfiction. Only a small sliver read books about money. Be an exception and join them.
Not Perfect
There are various criticisms of the book, such as:
being an outsider: but being outside the traditional financial community gives Tony a different perspective
contradicting advice: but that’s common in life. He interviews 50 money experts with varying views.
over-simplified: but isn’t that better than over-complicating and confusing? Complexity can be added once the A-B-Cs (or 1-2-3s) are known.
conflicts of interest: Tony recommends companies in which he might have financial interests (see dealing with biased financial advice). That doesn’t mean the choices are bad but they but warrant more investigation.
too long: yes … I got the audiobook, which runs over 21 hours and sped up the playback by 30%
US-centric: yes but the general ideas apply everywhere
Do celebrities give better financial advice? Maybe not but Tony reaches the unreachable: people who get missed by conventional financial education. Even when Tony says things you’ve heard before, you might be more likely to believe them now. For instance, I’ve covered things like
We often know the keys about money (e.g., spend less than you earn, disaster-proof your life, save for the future). That doesn’t mean we do. Tony helps people change. He might get you to change too. He has a knack for making financial education engaging. He explains his terms and uses many examples.
Differently
Instead of writing a book, Tony could have created videos and an app. That’s what I thought before getting the book. I don’t see videos, but he has a free app (if you’re willing to give your contact information).
Instead of using a conventional publisher, Tony could have self-published. He could have made the book cheaper. He could have narrated the full audiobook, rather than portions.
Overall, what he did is fine.
Free Meals
Tony is paying for 50 million free meals. Besides donating all his book royalties, he’s made an additional personal financial contribution. That’s rare. Chances are good that you’ll end up on his mailing list, though. That gives him the opportunity to sell you his other stuff with the money you’re saving.
Caution
Tony tackles tough topics such as the conflicts of interest rampant in the financial sector. He gives solutions too. Think before you leap.
The stories from successes like Richard Branson are interesting but may not provide much practical guidance (e.g., how Honest Ed turned $212 into $100 million). Look for patterns rather than a guaranteed formula to financial independence.
I wasn’t expecting much from Tony’s book but because he’s popular, I knew that I had an obligation to read it. Overall, I’m impressed and highly recommend Money: Master The Game. There’s lots of practical advice.
Money books get stale. Tony’s book is new, which means now is the best time to read it.


 Posted By