Building Wealth

For the first 30 or so years of working, saving and investing, you’ll be first in the mode of getting out of the hole (paying down debt), and then building your net worth (that’s wealth accumulation.). But don’t forget, wealth accumulation isn’t the ultimate goal. Decumulation is! (a separate category here at the Hub).

Darren Coleman interviews Tax expert Kim Moody about Liberals floating tax on Home Equity

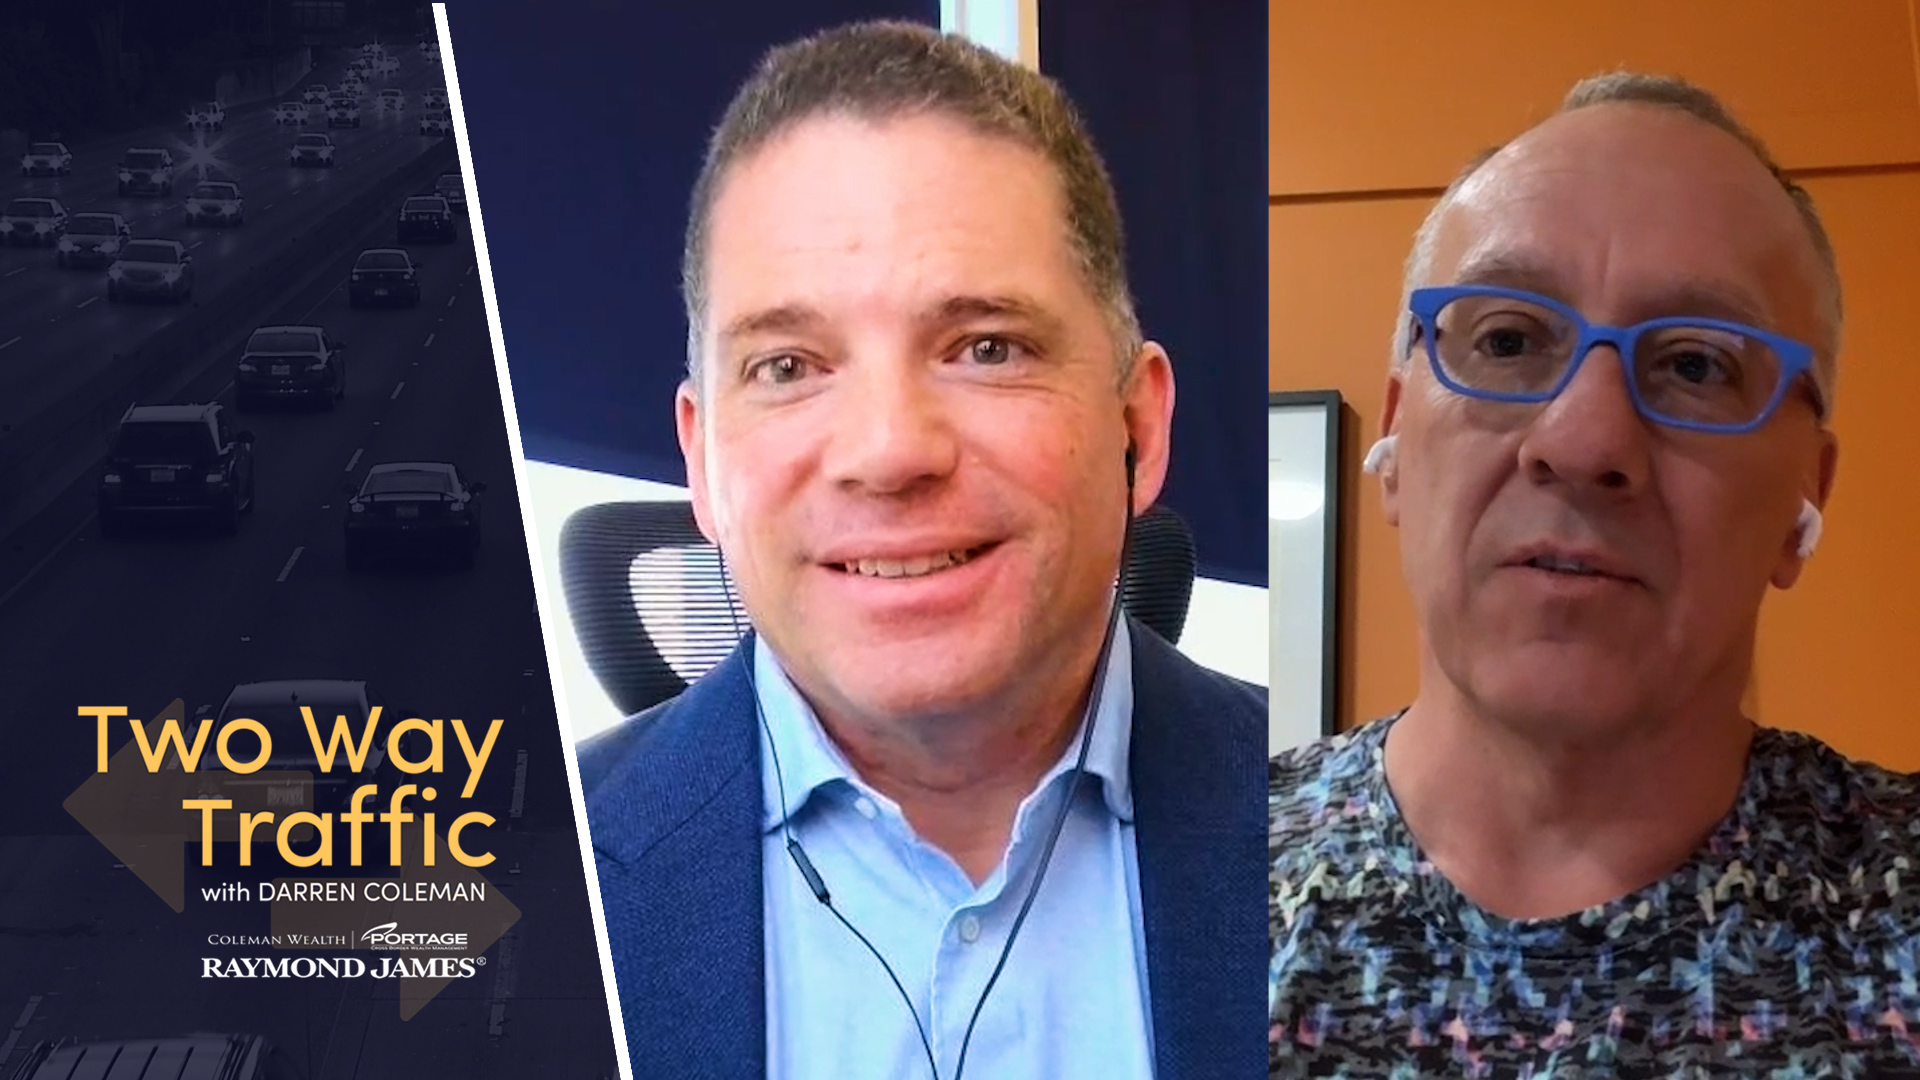
Darren Coleman (left) and Kim Moody (right, with glasses).

The following is an edited transcript of an interview conducted by financial advisor Darren Coleman’s of the Two Way Traffic podcast with tax expert Kim Moody, of Moody Private Client. It appeared on August 8th: click here for full link.

Moody recently wrote an article in the Financial Post about the government flirting with the idea of a home equity tax, even on principal residences. Such a tax could result in an annual levy of about $10,000 for a home worth $1 million. He described that, along with the increase in the capital gains inclusion rate that has already passed into law, “really bad tax planning” based on ideology, not economics.

In the podcast Moody and Coleman also discussed …

  • The disparity between U.S. and Canadian tax rates, beginning with how the state of Florida compares with Ontario, a difference of 17%.
  • The tax model established in Estonia lets you reinvest in your company without paying corporate tax while personal income is taxed at a flat rate of 20%. They say such a system would work in Canada, and celebrate success and entrepreneurship.
  • What organizations like the Fraser Institute and mainstream economists think about Canada’s economic performance.

Below we publish an edited transcript of the start of the interview, focusing on the capital gains inclusion rate and trial balloon about taxing home equity.
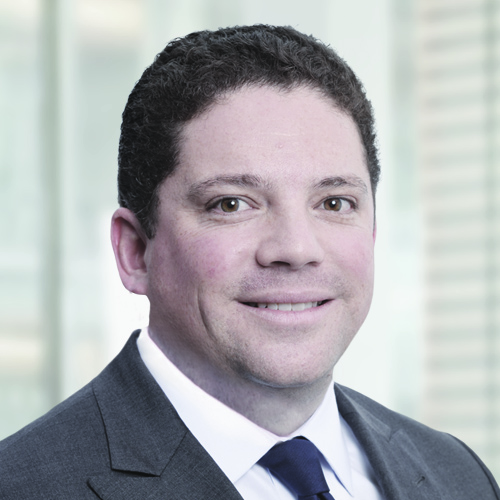
Darren Coleman, Raymond James

Darren Coleman:  I’m Darren Coleman, Senior Portfolio Manager with Raymond James in Toronto.  I’m delighted to be joined by Kim Moody of Moody’s tax and Moody’s private client. You’re also a law firm based in Calgary, Alberta, and probably one of Canada’s best known tax and estate planning advisors. You may have heard our last conversation with Trevor Perry  about some of the issues we might be seeing in terms of taxation of the principal residence in Canada.

I think because governments have spent so much money that we’re going to see tremendous innovation in taxation.  Do you want to set the table for the article you wrote in the Financial Post, where you talked about where this is coming from, and why Canadians might be on alert for what might be coming to tax the equity in their homes.

Kim Moody: The point of the piece was mainly just to put Canadians on notice that you had the Prime Minister and the finance minister sitting down with what I call a pretty radical
think tank.  I consider them an ideological bastion of radical thought but that issue aside,
they call them call themselves a think tank, and this particular one, led by Paul Kershaw of
Generation Squeeze, has stuff on their website that pretty much attacks older Canadians:
basically saying they’ve gotten rich by going to sleep and watching TV. Unbelievable. Whoever approved that, it’s just so offensive. But that issue aside,  the whole connotation of the messaging is that, hey, these people are rich. We’ve got these poor young Canadians who are not rich and they can’t afford houses because you’re rich and …

Darren Coleman Someone should do something about it, right? That’s the trick.
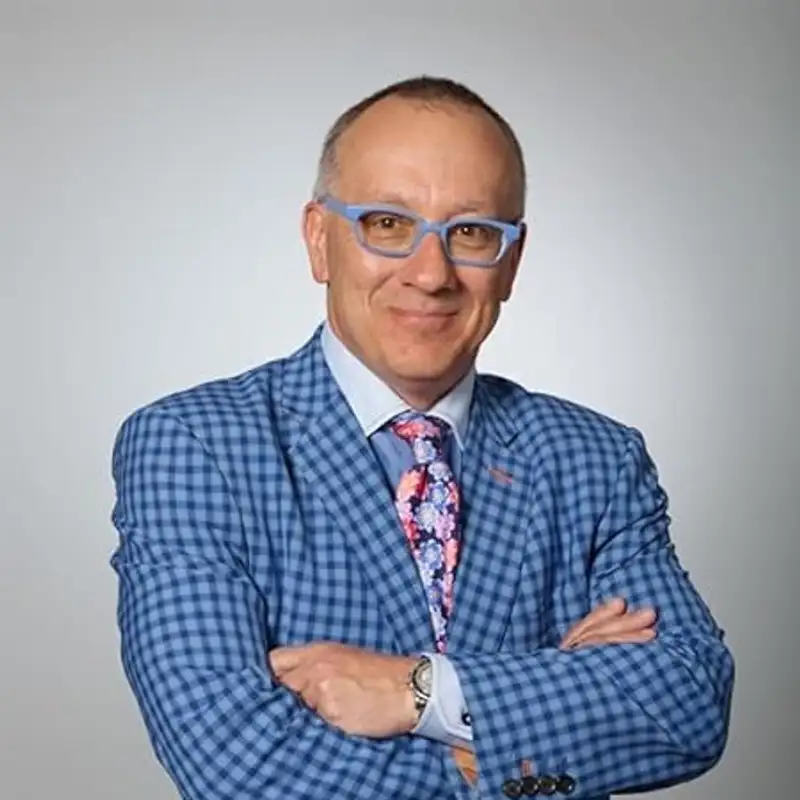
Kim Moody

Kim Moody: Someone should do something about it. And their solution is to introduce a so-called Home Equity tax on any equity of a million dollars or more. And they call it a modest surtax of 1% per year. So it’s like another, effectively property tax … It’s just so nonsensical and so offensive on a whole bunch of different levels. Like you think about grandma and grandpa, yeah, they’ve got equity in their homes, but they don’t have a lot of cash. They’ve been working hard their entire lives to pay off their houses. And yes, they want to transfer down to their kids at some point, but right now, they’re living again, and they’re making ends meet by living off their pensions that they worked hard, and you’re expecting them to shell out more money for that, and I find that offensive.

…. Back to the original premise of why I wrote the article:  to let Canadians know that our leaders are entertaining stuff like this. It doesn’t mean they’re going to implement it, but they’re actually entertaining radical organizations like this and secondly, just to put Canadians on
notice that this is just the beginning. If this regime continues with out-of-control spending and no
adherence to basic economics, then we could expect a whole bevy of new taxes.

Darren Coleman  

Indeed, they’ve already done some of this, right? So you know that this idea about we’re going to tax home equity, either through some kind of annual surtax on equity over a certain amount, or we’re going to put a capital gain on principal residences. And I would argue that for years now, Canadians have had to report the sale of the principal residence on their tax returns, which is a non-taxable event, yet you now have to tell them, and if you don’t, there’s a penalty. Continue Reading…
Stock Market Anxiety leads to Bad Investing Decisions. Here’s what to do Instead

Ignore stock market anxiety and negative stock predictions and instead focus your investing strategy on diversification and portfolio balance

Deposit Photos

The current state of the world is generating stock market anxiety, as it often does. My guess is that the Israel-Hamas war is just getting started and will last a long time. I also suspect that Russian dictator Vladimir Putin had something to do with getting it started, and will do what he can to keep it going. After all, when it comes to running his country, Putin takes a grasping-at-straws approach.

Putin may think that bringing the longstanding Mideast conflict back into the headlines is going to improve his chances of conquering Ukraine and bringing the Soviet Union back from the dead.

He thinks taking a long shot is better than no shot at all. Who knows? He might get lucky.

Early on in his war on Ukraine, Putin seemed to think that Chinese dictator Xi Jinping was going to take pity on him and his country, and offer free money and/or weapons to shore up Russia’s Ukraine invasion. Instead, Xi insists on staying out of the war, while paying discount prices for Russian oil. He takes special care not to let his country get caught up in the economic sanctions that the U.S. and NATO countries and allies are directing against the Russians.

It’s not that Putin is stupid. If a war between Israel and Hamas turns out to be a big drain on the U.S. budget, the U.S. might have less money available to arm Ukraine.

Up till lately, however, Israel has had little to say about Russia’s treatment of Ukraine. Israel may soon take a more active role in helping Ukraine defend itself.

Any war is a terrible thing, and this one is no different. The stock market seems to be creeping upward. Maybe it knows something that Putin hasn’t figured out.

Meanwhile, if your stock portfolio makes sense to you, we advise against selling due to Mideast fears.

Stock market anxiety recedes with investment quality, diversification and portfolio balance

You’ll find that many of your worries concern things that are unlikely to happen; that are already largely discounted in current stock prices; and that probably won’t matter as much as you feared they would.

You get a much better return on time spent if you devote less of it to worrying about high risk investments, and more of it to an investing strategy. Create a strategy that is built upon analyzing the quality and diversification of your investments, and the structure and balance of your portfolio.

There’s another advantage as well. A calm investor is much less likely to react in haste and make sudden decisions that could prove to be damaging in the long run. Continue Reading…

Investment Synergy: From the 1960s Takeover Craze to Today’s AI Revolution

The term “investment synergy” entered common investor use during the takeover craze of the 1960s — but we see a new synergy that’s a big plus for investors.

Image courtesy TSInetwork.ca


The term “synergy” entered common investor use during the takeover craze of the 1960s, when businesses started to expand by taking over companies in unrelated fields. This was supposed to make the combined companies grow faster than if they had stuck to their own fields.

The acquirers borrowed a term from biology to explain their rationale: this mix-rather-than-match growth strategy brought synergistic benefits. Synergy refers to an interaction between two or more drugs. The total effect of the drugs is greater than the sum of the individual effects of each drug if taken separately. For instance, today’s treatments for cancer, prostate and other health issues often call for prescribing two or more drugs. The combined impact may be more powerful and beneficial than you’d expect from adding up what they could do separately.

However, the synergy effect can also be negative. For example, combining alcohol with tranquilizers or opiates can lead to negative outcomes, even death.

The impact of 1960s investment synergy-seeking growth was uneven. Sometimes it worked, but it was better at producing temporary gains in stock prices than lasting gains in corporate earnings. In later decades, however, it turned out that unwinding synergy-seeking takeovers could lead to even larger profits.

This unwinding broke companies up into a “parent” and one or more “spinoffs.” The parent would then hand out shares in the spinoff to its own shareholders, as a special dividend.

A number of academic researchers have studied the outcome of spinoffs. Most found that spinoffs produce some of the most dependable profits you can find in the stock market, at least for patient investors. The academic findings were so impressive that we called spinoffs “the closest thing to a sure thing that you can find in investing.” (In fact, we were so impressed that it spurred us to launch our Spinoffs & Takeovers newsletter.)

You can find a number of processes in finance and investing that seem vaguely biological or scientific. For instance, consider Moore’s Law. It refers to the 1965 observation made by Gordon Moore (co-founder of Intel Corp.) that the number of transistors in a dense integrated circuit (now called a microprocessor) doubles about every two years. As a result, costs drop by half, and computing speed doubles. (Manufacturing progress later cut that time down to 18 months.)

This high growth rate was due to improvements in the basic design of early transistors. The continuing improvements spurred fast growth in the profits of Intel and other microprocessor stocks, and sharp gains in their stock prices in the 1980s and 1990s. Around 2005, however, the rise in computer processing speed began to slow. Now some bearish analysts predict that Moore’s Law is dead. They say the effect is bound to peter out because microprocessors can only get so small before they quit working. Meanwhile, cramming too many processors on a chip can lead to over-heating. Continue Reading…

Take advantage of the U.S. Manufacturing Boom with this Industrials Monthly Income ETF

Image courtesy Harvest ETFs

By Ambrose O’Callaghan, Harvest ETFs

(Sponsor Blog)

The passing of three important pieces of legislation in 2021 and 2022 thrust the United States manufacturing sector, and industrials, into the spotlight. But what are industrials, anyway? When we are talking about industrials, we are referring to a sector that is composed of companies that produce goods used in construction and manufacturing that encapsulates several sub-sectors.

Some of the most prominent sub-sectors in the Industrials space include Aerospace & Defense, Electrical Components & Equipment, Industrial Machinery & Supplies & Components, Rail Transportation, and others. The Industrials sector is drawing attention in 2024 for several key reasons.

Today, we are going to explore the resurgence in U.S. manufacturing, the burgeoning aerospace and defense space, and the merits of Harvest’s first-ever covered call Industrials ETF. Let’s jump in.

The resurgence in U.S. manufacturing

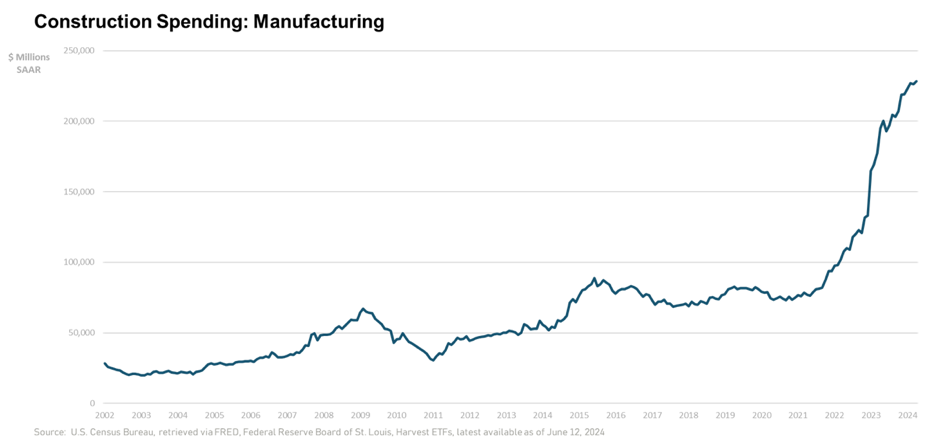
According to the U.S. Department of the Treasury, real manufacturing construction spending has doubled since the end of 2021. This increase occurred in a supportive policy climate after the passing of three key pieces of legislation: The Infrastructure Investment and Jobs Act (IIJA), the Inflation Reduction Act (IRA), and CHIPS Act. These three pieces of legislation provided funding and tax incentives for public and private entities in the manufacturing construction space.

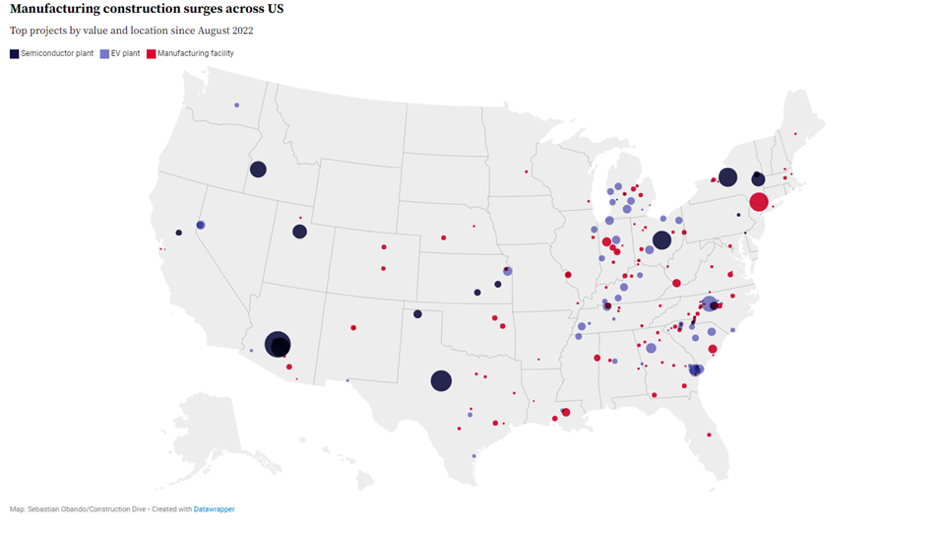
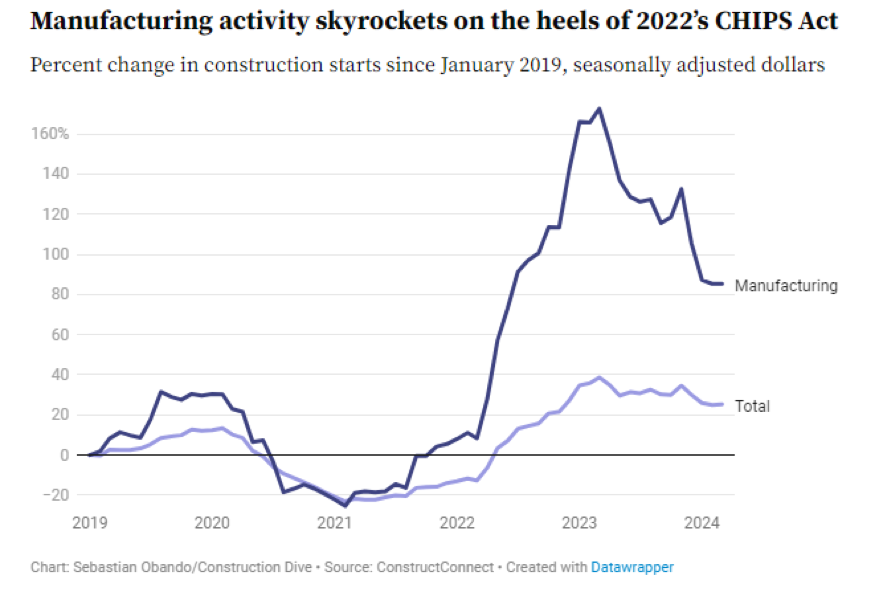
The U.S. Treasury Department report shows that the computer/electronic segment has represented the largest component of the U.S. manufacturing resurgence. However, the growth in the size of that segment has not been offset by a reduction in spending in other manufacturing sub-sectors. Construction in areas like chemical, transportation, and food/beverage have all enjoyed growth through 2022, just at a reduced pace. The chart below shows the top manufacturing construction projects by value and location since August 2022.

The CHIPS and Science Act was signed into law by President Joe Biden on August 9, 2022. It included US$39 billion in subsidies for chip manufacturing on U.S. soil. This included 25% investment tax credits for the cost of manufacturing equipment. The chart below shows construction spending in the manufacturing space over the past two decades, bookended by a surge after three pieces of legislation.

Deutsche Bank research indicated that 18 new chipmaking facilities began construction between 2021 and 2023. Indeed, the Semiconductor Industry Association reported that more than 50 new semiconductor ecosystem projects have been announced after the CHIPS Act.

Aerospace and defense spending today

The aerospace sector involves the design, manufacture, and operation of vehicles that travel in aerospace. Meanwhile, the defense sub-sector produces and seeks to sell weapons, and military technology. Continue Reading…

Four Strategic ways to invest in U.S. Stocks using BMO ETFs

Image courtesy BMO ETFs/Getty Images

By Erin Allen, Vice President, Direct Distribution, BMO ETFs

(Sponsor Blog)

As of May 31, 2024, the U.S. stock market accounts for approximately 70% of the MSCI World Index1, making it a significant component of global equity markets: and likely a substantial portion of your investment portfolio as well.

While Canadian investors often favour domestic stocks for tax efficiency and lower currency risk2, incorporating U.S. stocks can enhance exposure to sectors where the Canadian market — predominated by financials and energy — falls short, particularly in technology and healthcare.

For Canadian investors looking to tap into the U.S. market affordably and without the hassle of currency conversion, there are numerous ETF options available. Here are four strategic ways to build a U.S. stock portfolio using BMO ETFs, catering to different investment objectives.

Low-cost broad exposure

If your objective is to gain exposure to a broad swath of U.S. stocks that reflect the overall market composition, the S&P 500 index is your quintessential tool.

This longstanding and highly popular benchmark comprise 500 large-cap U.S. companies, selected through a rigorous, rules-based methodology combined with a committee process, and is weighted by market capitalization (share price x shares outstanding).

The S&P 500 is notoriously difficult to outperform: recent updates from the S&P Indices Versus Active (SPIVA) report highlight that approximately 88% of all large-cap U.S. funds have underperformed this index over the past 15 years.3

This statistic underscores the efficiency and effectiveness of investing in an index that captures a comprehensive snapshot of the U.S. economy.

For those interested in tracking this index, BMO offers two very accessible and affordable options: the BMO S&P 500 Index ETF (ZSP) and the BMO S&P 500 Hedged to CAD Index ETF (ZUE), both with a low management expense ratio (MER) of just 0.09% and high liquidity.

While both ETFs aim to replicate the performance of the S&P 500 by purchasing and holding the index’s constituent stocks, they differ in their approach to currency fluctuations.

ZSP, the unhedged version, is subject to the effects of fluctuations between the U.S. dollar and the Canadian dollar. This means that if the U.S. dollar strengthens against the Canadian dollar, it could enhance the ETF’s returns, but if the Canadian dollar appreciates, it could diminish them.

On the other hand, ZUE is designed for investors who prefer not to have exposure to currency movements. It employs currency hedging to neutralize the impact of USD/CAD fluctuations, ensuring that the returns are purely reflective of the index’s performance, independent of currency volatility.

Large-cap growth exposure

What if you’re seeking exposure to some of the most influential and dynamic tech companies in the U.S. stock market, often referred to as the “Magnificent Seven?”

For investors looking to capture the growth of these powerhouse companies in a single ticker, ETFs tracking the NASDAQ-100 Index offer a prime solution. As of June 27, all of these companies are prominent members of the index’s top holdings4.

The NASDAQ-100 Index is a benchmark comprising the largest 100 non-financial companies listed on the NASDAQ stock exchange. This index is heavily skewed towards the technology, consumer discretionary, and communication sectors, from which the “Magnificent Seven” hail.

BMO offers two ETFs that track this index: the BMO Nasdaq 100 Equity Hedged to CAD Index ETF (ZQQ) and the BMO Nasdaq 100 Equity Index ETF (ZNQ). Both funds charge a management expense ratio (MER) of 0.39%. Again, the key difference between them lies in their approach to currency fluctuations.

Low-volatility defensive exposure

You might commonly hear that “higher risk equals higher returns,” but an interesting phenomenon known as the “low volatility anomaly” challenges this traditional finance theory.

Research shows that over time, stocks with lower volatility have often produced returns comparable to, or better than, their higher-volatility counterparts, contradicting the expected risk-return trade-off. Continue Reading…